Semtech Analyst Day Review
Semtech raised Q3 guidance and targets $3.2 billion of fiscal 2030 revenue, excluding upside from its AI data-center optical and copper interconnect businesses.
Semtech raised Q3 guidance and targets $3.2 billion of fiscal 2030 revenue, excluding upside from its AI data-center optical and copper interconnect businesses.
$CRWV has ~$10bn of unsecured HY notes, all yielding 14-15%. There’s also another ~$11bn of converts. That’s ~$21bn of unsecured claims, sitting behind the secured debt that funds the GPUs. Here's the latest market pricing on the HY notes (converts excluded): https://t.co/vVxKgKVCRc
 Tim Travis 10 clicks
Steve Eisman examines AI data-center debt, CoreWeave's tech correction and agentic AI's effect on banks as earnings season begins.
OpenAI and Meta push AI agents forward as reward hacking remains a core challenge for model training.
Meta ties AI agents and Meta Connect to its enterprise-platform opportunity.
Stratechery’s weekly bundle covers Apple HomeView and SpaceX’s cellular ambitions.
Bumble agreed to a $1.3 billion take-private deal, while Netflix cut about 1,000 jobs and Meta discussed its Muse superintelligence models.
Dorchester Minerals' 9.5% normalized yield and debt-free royalty model are offset by limited upside at $29.71, as extraordinary…
 Atlas Diary 3 clicks
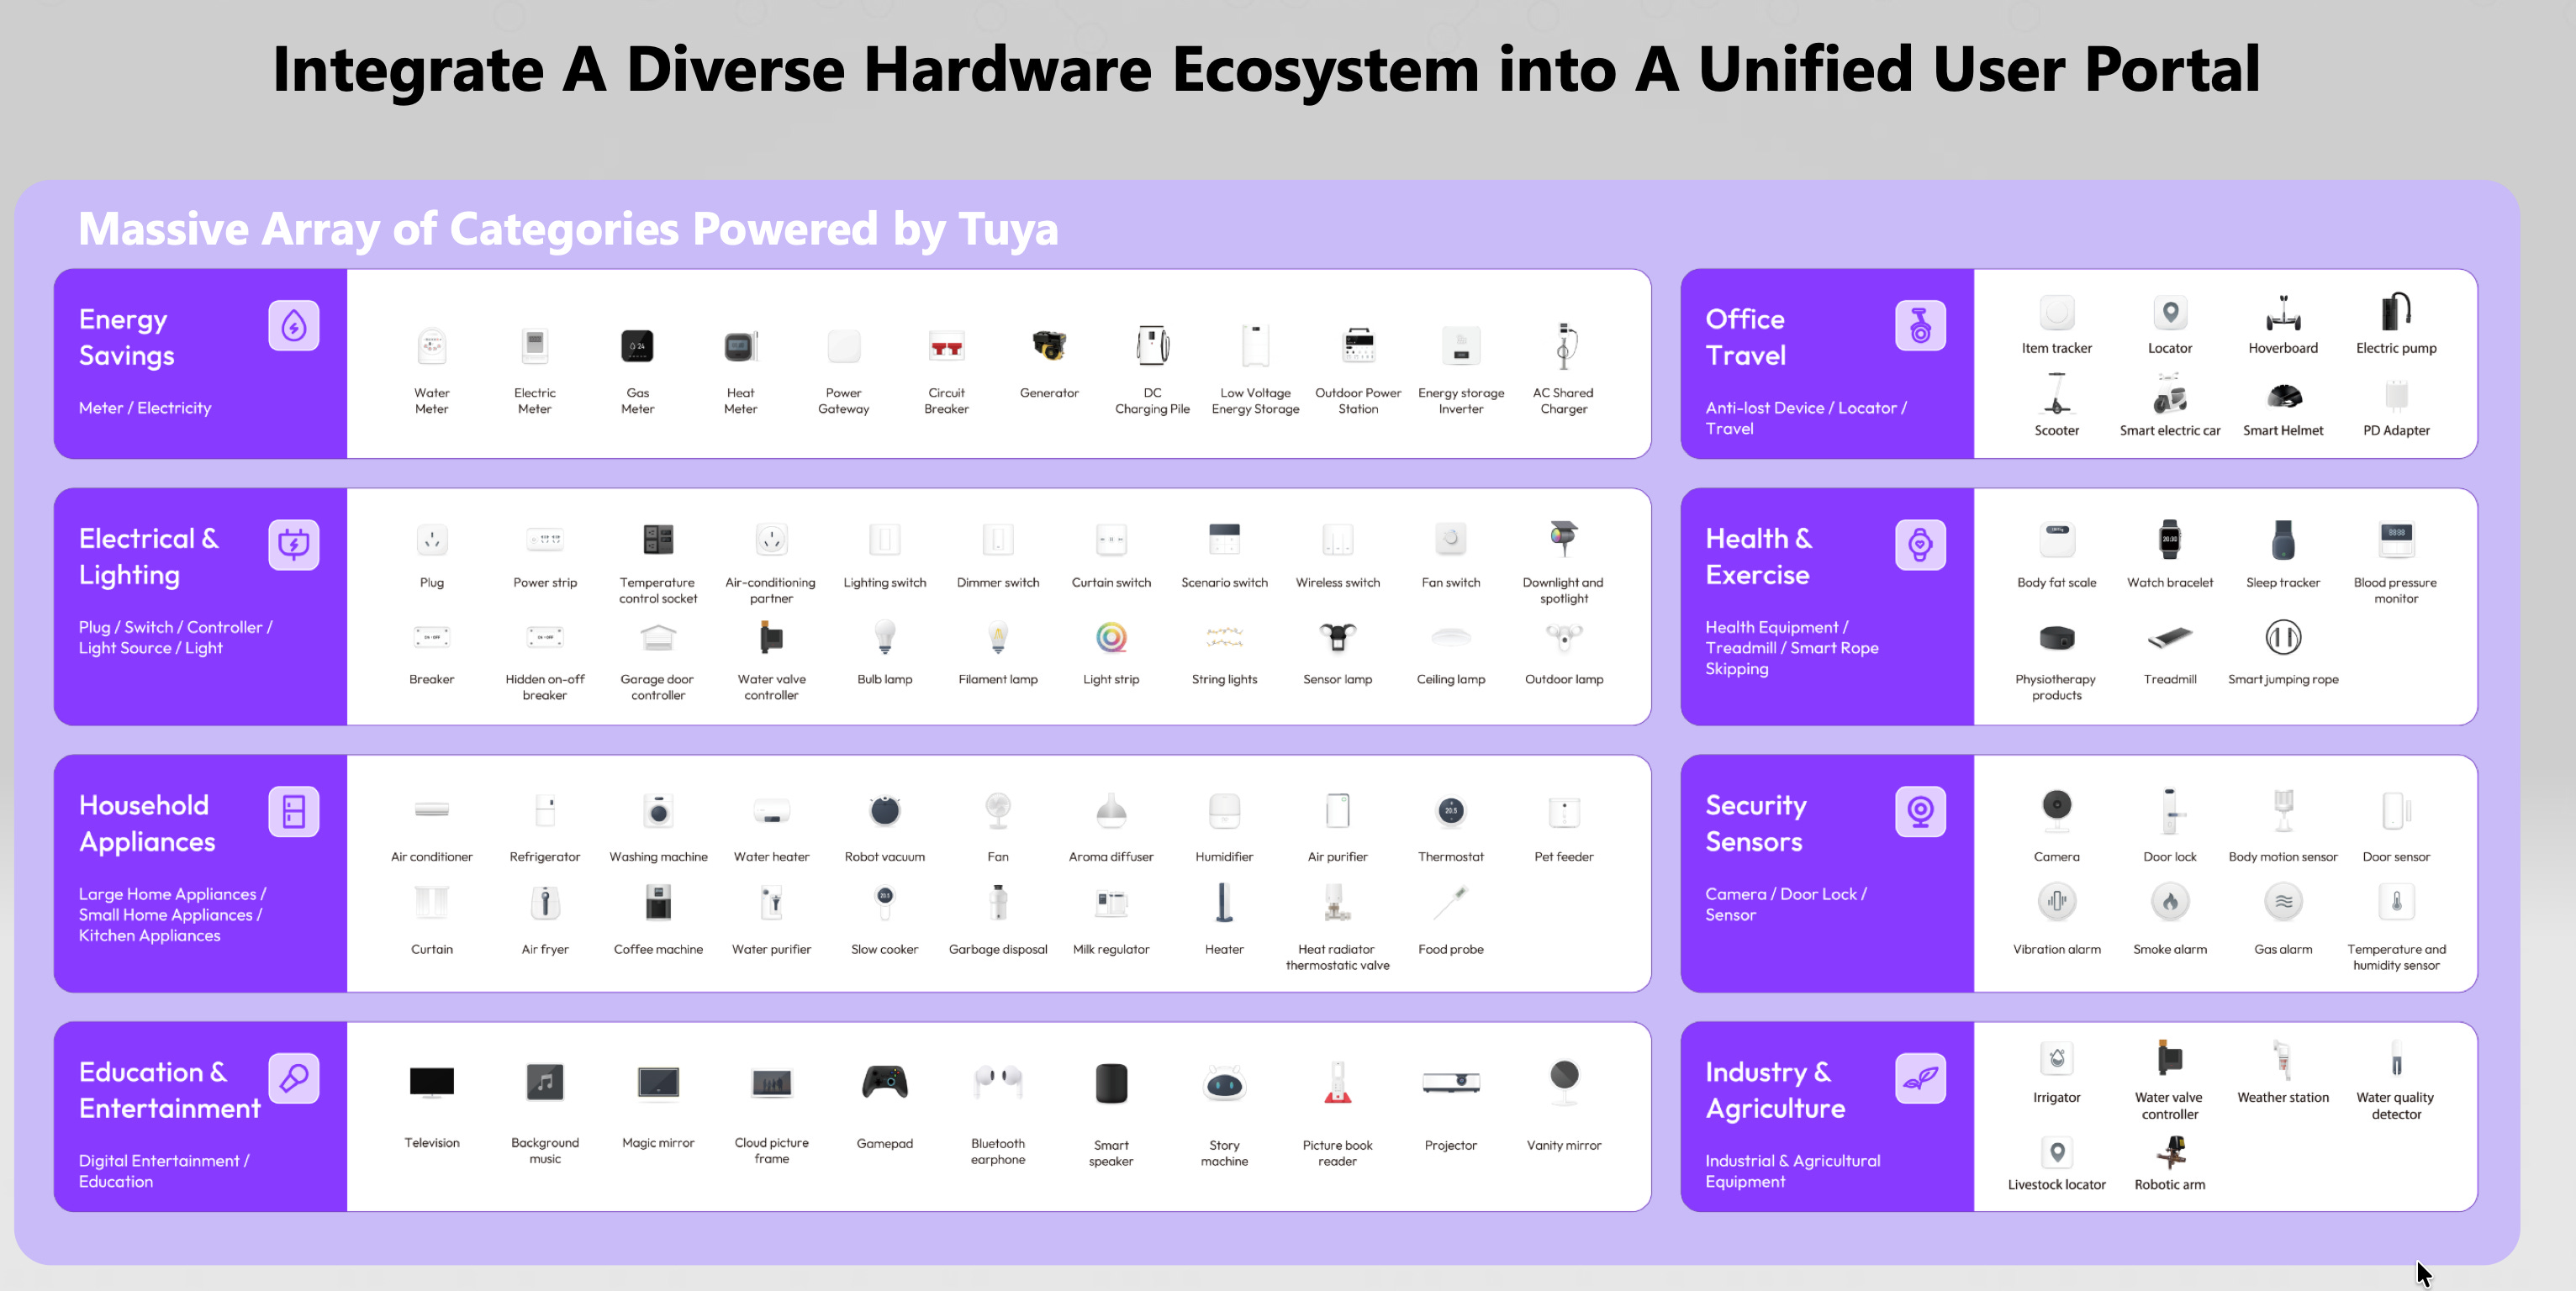
Tuya’s $976 million cash pile equals 94% of its $1.04 billion market cap as its smart-home platform returned to 16% revenue growth in Q2…
Fannie Mae and Freddie Mac could leave conservatorship through a 2026 restructuring and IPO, monetizing the government’s equity stake while…
 Glen Bradford 5 clicks
CoreWeave’s debt and equity price action is framed as a wake-up call for investors amid a broader market discussion.
 OSW · short
OneSpaWorld Holdings, the dominant outsourced cruise-ship spa operator across more than 200 vessels, is the subject of a short thesis.
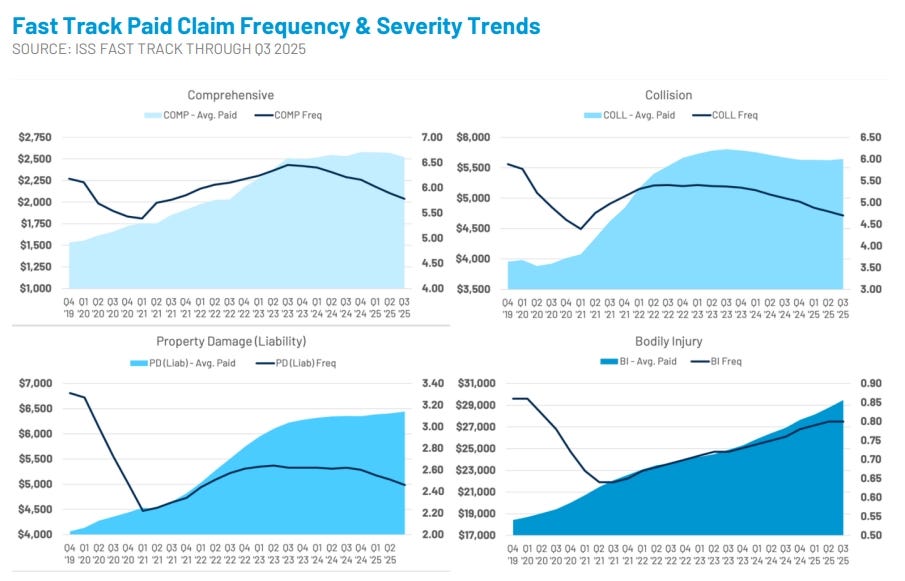
CCC, the dominant auto physical-damage claims estimator, connects 27 of the top 30 insurers with 31,000 repair shops as takeout rumors…
 TEM 2026-08-20
Tempus AI's diagnostics and data businesses grew Q2 2026 revenue 19.4% year over year, with FDA approvals, expanded tests and pricing aimed…
S&P Global trades at 22-23 times earnings after a 25% drawdown, as AI concerns discount its data unit despite Ratings and Indices…
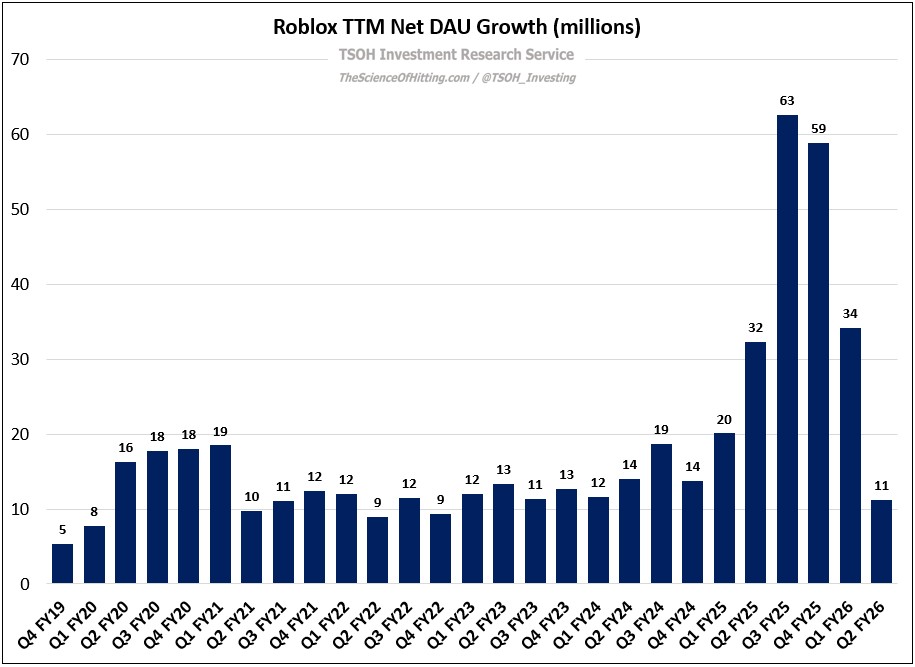
Roblox reached 144 million DAUs and 123.9 billion engagement hours by 2025, but Q3 FY26 bookings are set to fall mid-teens, renewing calls…
Verra Mobility's new seven-year Avis agreement replaces a customer worth over 10% of revenue on materially worse economics, exposing…
BHP 2026-08-20 BHP expects copper to generate over half of FY2026 EBITDA and plans a 40% production increase by FY2035 after profit, free cash flow and…
 On the Pulse 1 click
Indie Semiconductor’s automotive sensing chips are finding robotics demand, while industrial, navigation and quantum businesses sit inside…
Norwegian Cruise Line’s $15 billion debt and 2026-27 capex delay deleveraging, despite fuel-efficient new ships and stronger projected 2028…
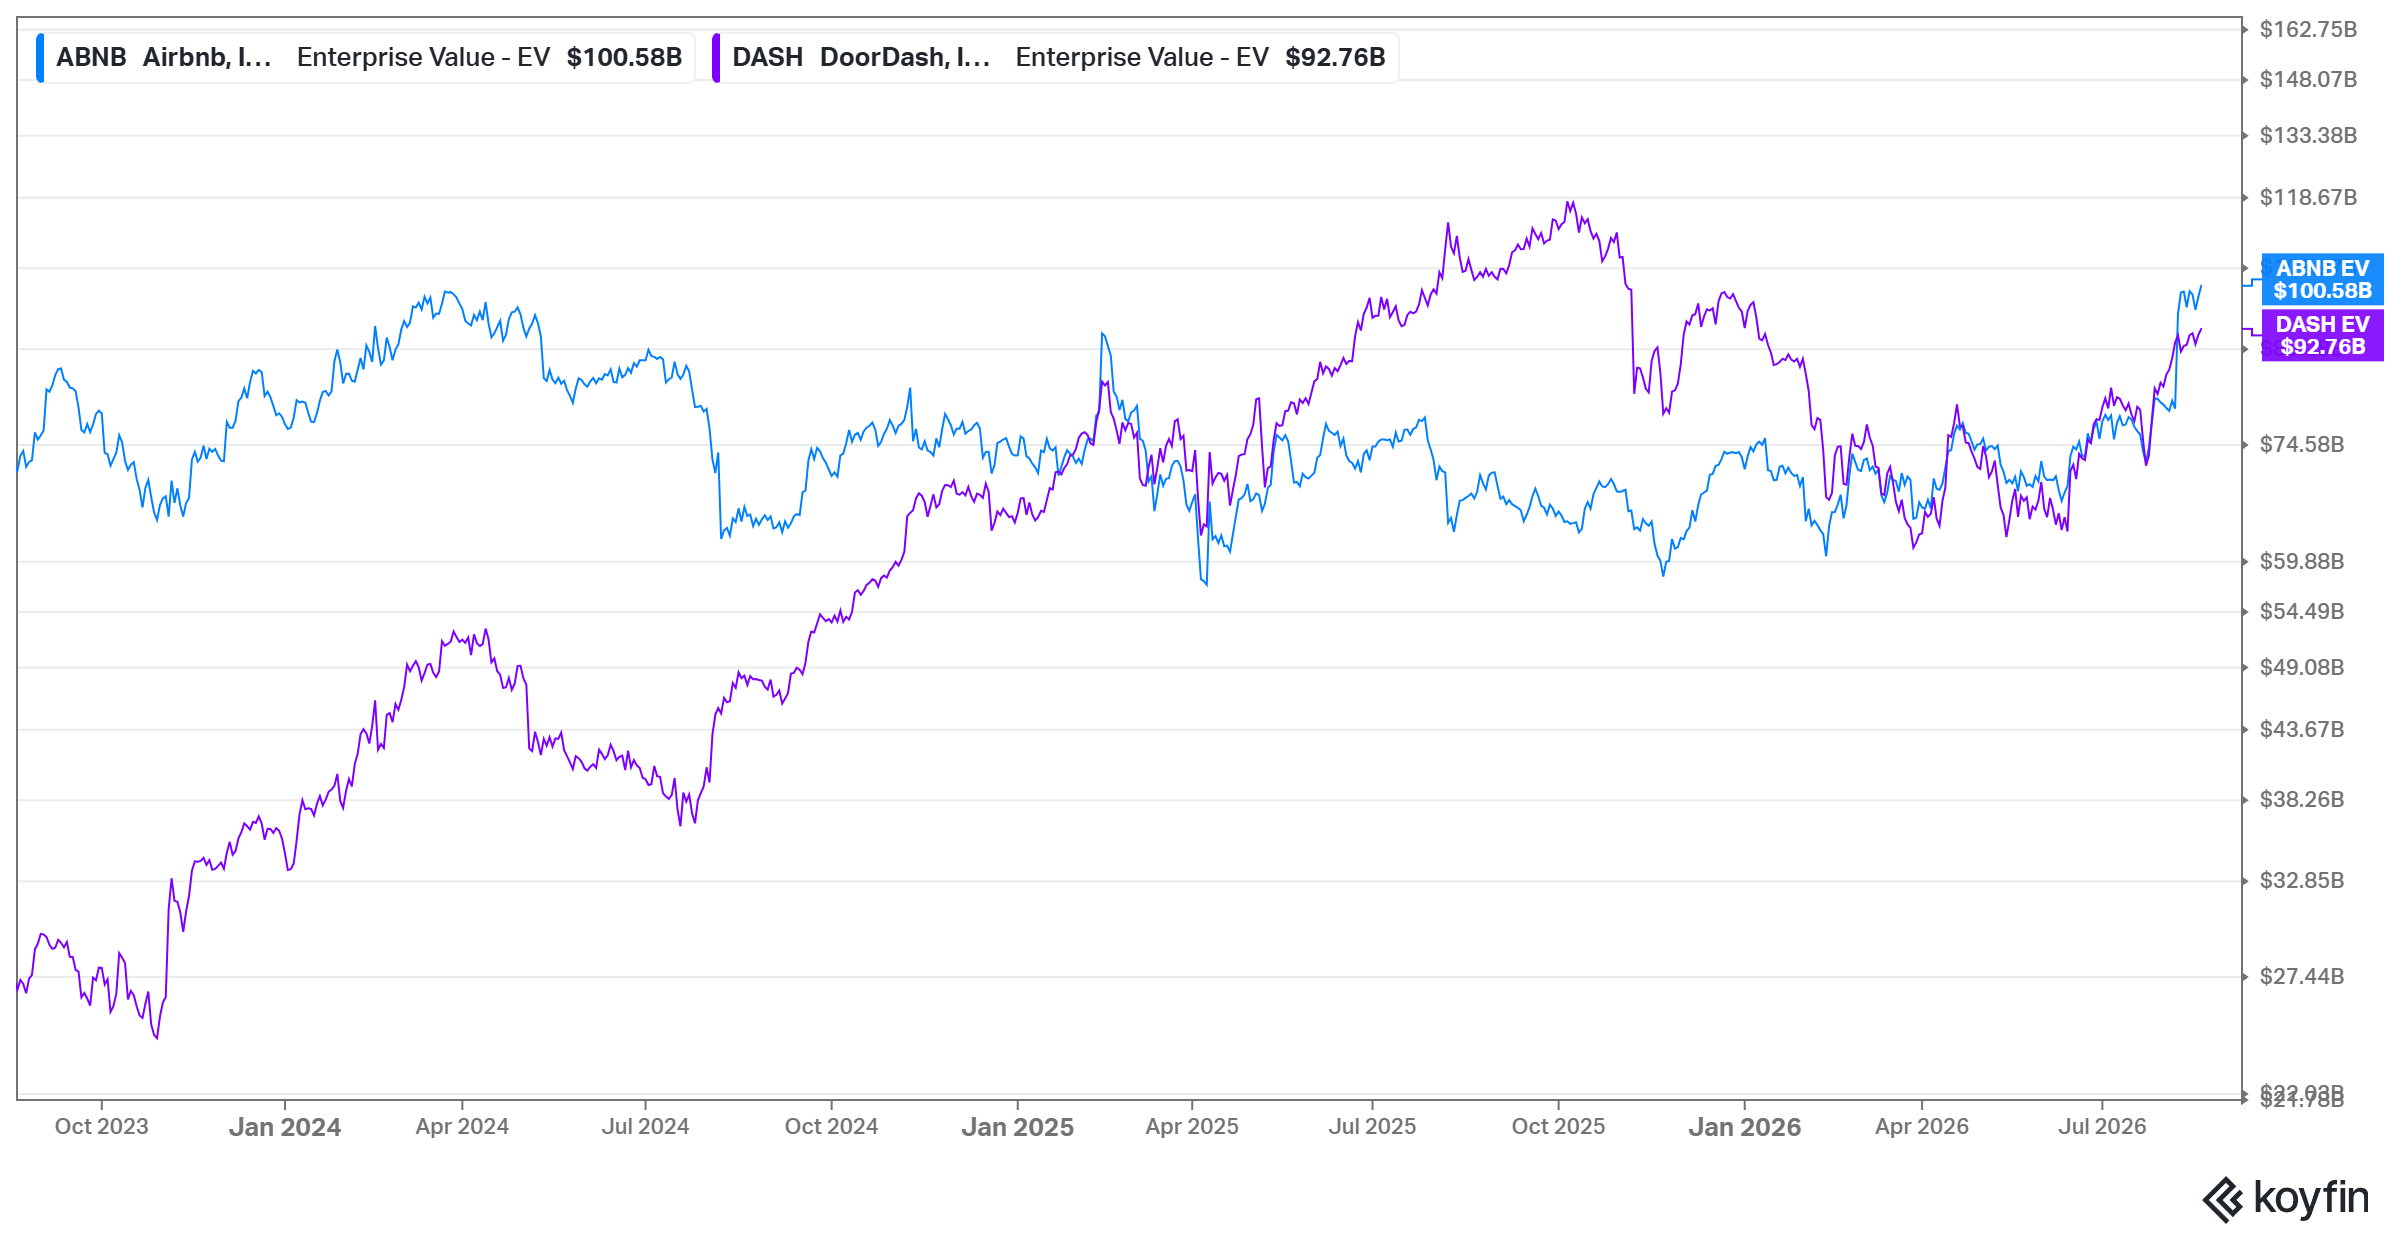
Airbnb shares have risen about 50% since October 2025, prompting a revised 2026 model and return assumptions at the current price.
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.