Semtech Analyst Day Review
Semtech raised Q3 guidance and targets $3.2 billion of fiscal 2030 revenue, excluding upside from its AI data-center optical and copper interconnect businesses.
Semtech raised Q3 guidance and targets $3.2 billion of fiscal 2030 revenue, excluding upside from its AI data-center optical and copper interconnect businesses.
$CRWV has ~$10bn of unsecured HY notes, all yielding 14-15%. There’s also another ~$11bn of converts. That’s ~$21bn of unsecured claims, sitting behind the secured debt that funds the GPUs. Here's the latest market pricing on the HY notes (converts excluded): https://t.co/vVxKgKVCRc
The asset base is too large and diversified to ever underwrite loan by loan. The thesis is that the private credit apocalypse is exaggerated, $OWL became the poster child given its reliance on the HNW channel, and the market is assigning far too little value to its non-credit assets and durable fee-generating franchise.
@FrenchV33921 Already there with $CRWV and $IREN IS $NBIS worse?
@sidecarcap This is exactly what I think is happening with $SLM $KSPI and maybe $YB. $KNSL too
@Pembrokestcap But isn’t $OWL reputation, and by extension their ability to raise capital, permanently impaired? Who cares if they own valuable GP stakes and real estate businesses that never tapped the high-net-worth channel? Isn’t the entire franchise structurally compromised?
My favorite part of this $OWL article… What possible value could investment bankers see in a full or partial sale of the business that the public market is apparently missing? https://t.co/5rjY1IZQv1 https://t.co/yWPrLNBD21
Wall Street finally started to see the GameStop $GME transformation. Dan Ives just made a comment on the company. Wait until other sheep start piling into the story. https://t.co/PsHMLM94Tv
RELX’s 13-petabyte fraud and identity data moat supports its high-margin Risk segment as its valuation falls to roughly half its peak P/E.
 LA Capital 8 clicks
CoreWeave’s debt and equity price action is framed as a wake-up call for investors amid a broader market discussion.
CoreWeave’s 2032 notes yield over 15%, signaling a 54% default probability as borrowing costs exceed rental yields on AI infrastructure…
 Dustin Quasney 24 clicks

AppLovin rebuilt its ad model with AXON 2.0, lifting LTM revenue to about $7 billion and margins to 77% as Unity competition threatens…
Brookfield Asset Management's fee revenue rose 16.2% and distributable earnings 15.8%, but its 18% five-year target relies on AI-led growth…
 Daniel Schönberger 3 clicks
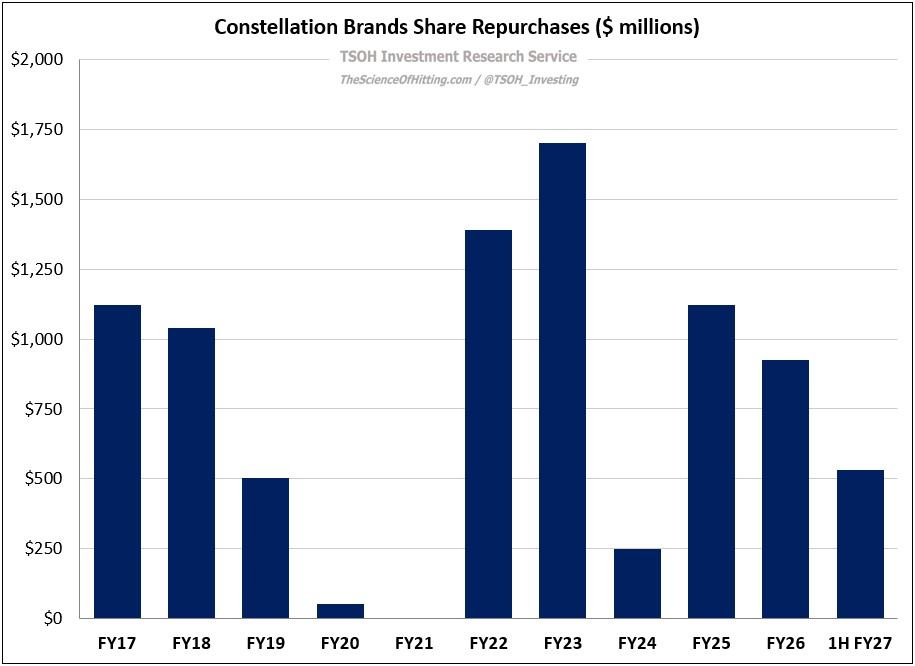
Constellation Brands trades near $127 at roughly 11x next-twelve-month EV/EBIT, with recent business results offsetting concerns over…
October 2026 market commentary covers SOLS’s cancelled merger, a hypothetical Starbucks-Chipotle deal, Russell 2000 weakness and AI…
CoreWeave faces fresh skepticism as another AI trade selloff collides with bullish defenses of the company.
Ari Emanuel discusses AI’s impact on Hollywood, live events, social networks and the future of advertising.
 ZTS · long
Zoetis, the animal prescription-medicines company, is presented as a long investment despite concerns around its 2026 and 2027 outlook.
Fiserv trades below 7 times 2026 earnings after a 60% decline, as new management resets guidance and seeks to stabilize its banking…

Tyler Technologies’ moat rests on something more durable than code, even as AI-driven fears have cut SaaS valuations.
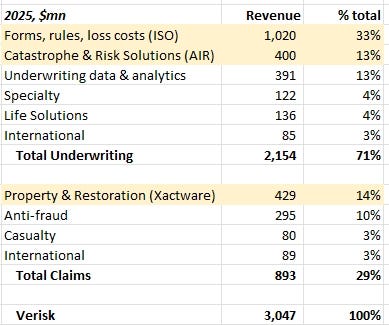
Verisk’s exit from healthcare, financial-services and energy data restored a pure-play insurance analytics model, but D.E.
Brown & Brown compounded revenue 14.4% annually since 1998 through more than 650 acquisitions, capped by its nearly $10 billion Accession…
Ford’s 1956 IPO sold 10.2 million shares at $63 each after Goldman Sachs helped resolve the Ford Foundation’s voting-rights problem.
Lawrence Hamtil discusses the farmer mentality, software’s cycle and investing with irreplaceable capital.
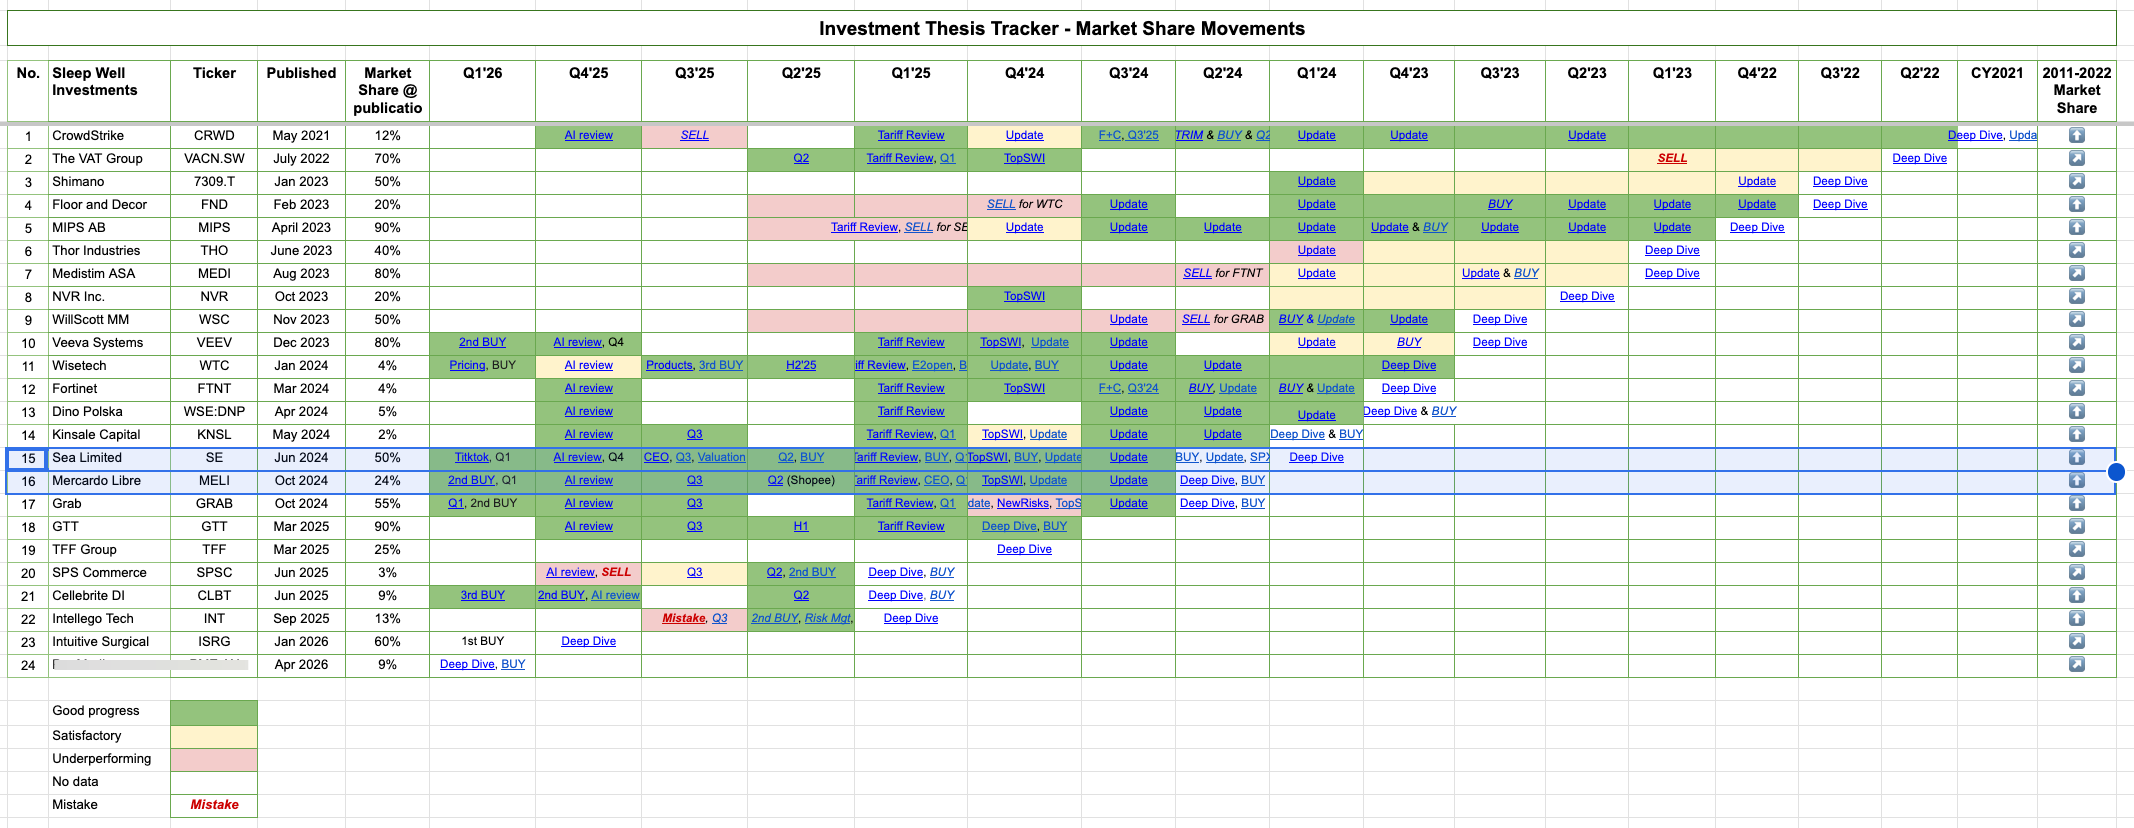
Sea and Mercado Libre defend Brazilian e-commerce share with logistics, cross-border trade, VIP programs and financial services, accepting…
Infineon’s power semiconductors stand to benefit from AI data centers shifting to 800VDC power delivery, though its sharp rerating to…
Universal Health Services faces a $432 million–$480 million annual Medicaid supplemental-payment hit by 2032, offset by behavioral-health…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.