Friday, October 16, 2026

Back to today

From X

@StableBread

Fajasy on X

The Department of Energy conditionally committed $17.5B in loans in June 2026 for long-lead equipment for up to 10 AP1000 reactors (Westinghouse’s large U.S. design), and only “a limited number of heavy engineering plants” can make the components, per World Nuclear News. BWX Technologies $BWXT bought Precision Components Group (PCG) in July 2026 to get a U.S. foothold. PCG makes heat exchangers and other heavy components at plants in York, Pennsylvania, and Florence, New Jersey, but it can’t make the largest parts, like an AP1000 reactor pressure vessel, CEO Rex Geveden said on the Q2 call. So $BWXT is weighing New Jersey, Indiana, and one other location for a new U.S. large-component plant, and Geveden expects “a final investment decision in the coming months.” He also expected at least one new-build equipment order by the end of 2026, from the three additional small modular reactors (SMRs) planned at Darlington in Ontario, the AP1000 projects, or BWRX-300 SMR projects in the U.S. John MacQuarrie, president of Commercial Operations, widened that window at $BWXT’s Investor Day on September 29, 2026, saying awards should start “either later this year or early in 2027.” $BWXT’s Investor Day targets call for high-teens annual revenue growth in the commercial segment through 2030, with adjusted EBITDA margins rising to the high teens from 13% in 2026. Reading “high teens” as 16-19%, commercial revenue would grow from ~$1.1B in 2026 to ~$2.0-2.2B by 2030, and adjusted EBITDA from ~$140M to ~$320-420M. That would make commercial about a third of $BWXT’s adjusted EBITDA, up from about a fifth.
@convequity 2 clicks

Convequity on X

A laser that only one company can supply will not scale to the volumes AI needs. That is the main reason $LITE is a less attractive investment to us than it was a few quarters ago. Our post on Lumentum got more attention than we expected, so we want to set out the argument in plain terms, including what we think about microLED. We did not say microLED will certainly happen. 1. The part in question is Lumentum's ultra-high-power external laser source. In co-packaged optics, the optical parts sit inside the chip package. The laser sits outside, in its own module, and its light is carried into the package by fibre. That outside module is the external laser source. Ultra-high-power means one laser produces enough light to feed many optical channels at once. 2. If only one vendor can make that laser, it has little chance of reaching meaningful volume. One supplier cannot carry a part the whole industry needs. So the industry has to find other paths around that bottleneck. 3. The first likely path is micro-VCSELs. A VCSEL is a vertical-cavity surface-emitting laser: a tiny laser that sends light out of the top of the chip rather than out of its edge. They are made many at a time on a wafer, and each one is low power. A micro-VCSEL is a very small version. Many small lasers do the job of one very powerful one. 4. The second path is a less powerful laser packed inside the NPO package. CW stands for continuous wave: the laser emits a steady beam, and a separate part, the modulator, switches that light on and off to carry data. NPO is near-packaged optics: the optical engine sits on the board right next to the chip, rather than inside the chip package or in a pluggable module at the front of the switch. In this path the CW laser is still fairly high power, but not ultra-high power, and it sits inside the optics package instead of in a separate external module. 5. The third path is microLED. A microLED is a very small light-emitting diode, the same kind of device as in a display, not a laser. Each one is switched directly to carry data, and many of them run in parallel over short distances. 6. On microLED, the consensus on X is that it will not work for AI interconnects. We are not saying it will certainly happen. It is one of several alternatives. But there is good research work on it, and it has a chance. Most of the criticism we see is aimed at one architecture. The research we rate uses microLEDs in a different architecture, and the criticism does not address it. 7. Lumentum will still grow. But compared with the previous few quarters it is a less attractive investment, because its ultra-high-power laser is the part the industry has to find a way around. We trimmed most of our Lumentum position earlier this year, around when the share price began to flatten.
@StableBread 1 click

Fajasy on X

Neither of the two commercial prospects BWX Technologies $BWXT has named for its BANR microreactor is a data center. 1) Prodigy Clean Energy, a Montreal-based developer of factory-built nuclear plants: Two BANRs for a transportable pilot plant in Belledune, New Brunswick, built mainly at $BWXT’s Ontario plants and running in the early 2030s. New Brunswick’s government signed a letter of intent (LOI) to buy the power. $BWXT and Prodigy are still negotiating a definitive agreement, and the release provides no dollar value. 2) Tata Chemicals Soda Ash: A Wyoming soda ash producer that signed an LOI to explore deploying up to eight BANRs. $BWXT also markets BANR to data centers. However, I found no data center contract, customer, LOI, or revenue in any $BWXT press release from January 2025 through October 2026, in the FY2025 10-K, or in the 2026 10-Qs. $BWXT’s own mentions stop at a product page saying BANR can provide “clean electricity for municipalities, data centers and campuses,” and slides 11 and 25 from its Investor Day on September 29, 2026, which list “AI/data center demand” as a driver of nuclear demand in general. I didn’t hear the phrase “data center” mentioned once during Investor Day, and slide 49 lists data centers in the third phase of $BWXT’s microreactor plan. CEO Rex Geveden said at Investor Day that “the incremental demand from AI right now is 60 GW” and “winning at AI means winning at power, and winning at power probably means having a nuclear solution.” If he’s right, $BWXT benefits by supplying components, fuel, and services to more reactors, not by selling microreactors to data centers. Advanced Reactor Design and Engineering, the product line that includes Project Pele (its prototype microreactor for the Pentagon) and $BWXT’s other microreactor programs, brought in $203.8M in 2024 and $147.1M in 2025, then $52.6M in H1 2026, down from $69.8M a year earlier. At 3.0% of $BWXT’s $1,761.8M of H1 2026 revenue, microreactors are still a small, early business.
@aleabitoreddit

Serenity on X

I think almost everything about my $AXTI thesis from 2025 was validated? From AXT's position in the InP substrate bottleneck... Being able to threaten the hyperscaler buildout (per Reuters)... $IQE has been flagging this as a major risk, VPEC and Taiwan epiwafer foundries have been crying over InP substrate bottlenecks. And there's even AXT direct confirmation of partnerships with $LITE and $COHR as the InP substrate supplier. AXT also stated $130m/quarter InP revenue capacity exiting 2027 (~$520m annualized) so that's a massive revenue inflection compared to previously. Now... the biggest question is: How much can AXT price hike? The substrates they make are just such a tiny part of the BOM... but can threaten hyperscaler buildouts with optics. So if they manage to price hike to $SNDK NAND degrees (which they can), then I think AXT could get re-rated a ton from here. But if they end up like Japanese ABF suppliers that are less willing to abuse their position, that's a different story. Will need to do more channel checks to see how that's coming along. But at the very least, I would argue there should be some valuation baseline just due to their critical importance (eg. upstream refinery ownerships, crucible processing, etc) + existing capacity revenue without hikes. TLDR: - Bottleneck thesis was at like ~$500m MC - Upside now comes from price hikes due to duopoly position + ownership of upstream bottlenecks in the InP substrate manufacturing process. (which they can due to low cost of InP substrates in overall costs) - Uncharted territory, we'll see (also a central part of geopolitical tensions so there's always risk there).
@aleabitoreddit

Serenity on X

Good question! Just some informal thoughts... there's three "moats" to look at for $SIVE: - Capacity - Qualifications (especially for custom DFB lasers) - Technological 1. For capacity, they're coming online with 100M+ CW DFB lasers Q4 2027 (global supply is roughly ~608M EML/CW lasers currently per Trendforce). Obviously by 2027 global capacity is going to grow a lot, with $AAOI, $AVGO (3x expansion), and others coming online. But if you extrapolate their 2:1 statement, that implies 300m lasers/year long term coming from their own supply + external foundries. This is incredibly valuable during a shortage that was quoted to be 3-5 years, and $LITE stating they already have demand visibility into 2031... And when suppliers have started to qualify many more (eg. 5-7 vendors vs. 2-3 earlier) due to bottlenecks. I'm sure a lot of how they achieve that staggering amount is due to their manufacturing process/yields (which is a moat). 2. For qualifications, if you look at 70mW/100mW pluggable lines with Chinese players, I'd argue this is more generic and moreso reverting back to a capacity argument and manufacturing process to achieve those numbers. Custom DFB arrays that they've been working on with Ayar (they hinted at 2-3 others back in 2023 like Celestial) take years for optical i/o related things and would be a moat if they finish quals. So it's not quite something you can hot swap or design out really easily for $MTSI or another company. But of course cpo scale up and such is mass volume in 2028, and we're still H2 2026. 3. People can always compare raw specs like power output, but it's probably way way more nuanced so easier to just point toward customer statements. With $JBL 1.6T LRO: "I think that there's the potential for a relatively dramatic moat with our LRO part…" from Jabil's EVP, especially related to power consumption. And $SIVE is my guess sole source in this line. Jabil is probably the most important testament to how their lasers perform in mass production scenarios maybe around Q2 next year. Ayar said something similar along the lines of "we couldn't do it without Sivers" for custom implementations.

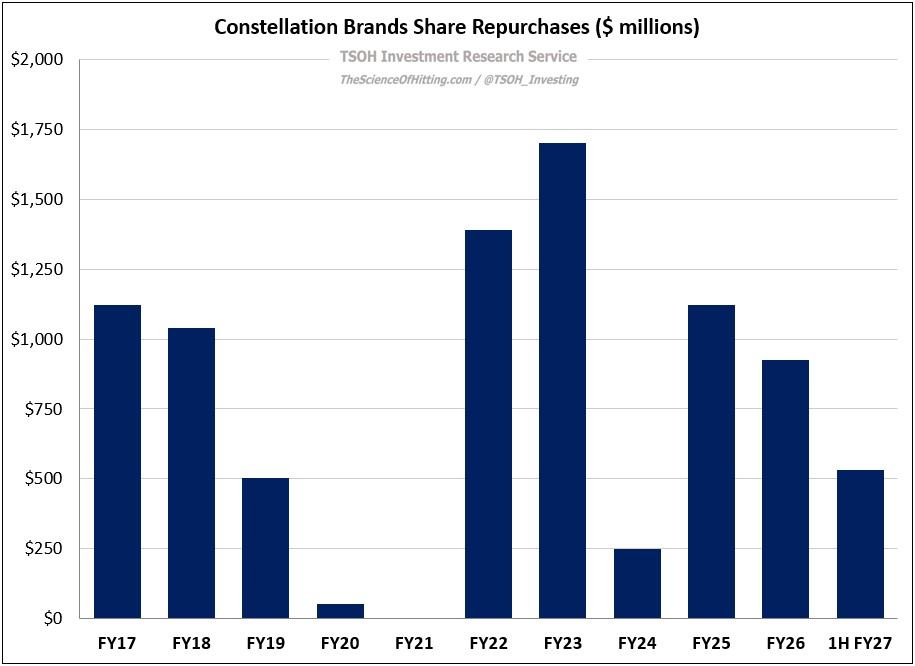
Constellation: Stars Aligning?

Constellation Brands trades near $127 at roughly 11x next-twelve-month EV/EBIT, with recent business results offsetting concerns over…
October 2026 Random Ramblings

October 2026 market commentary covers SOLS’s cancelled merger, a hypothetical Starbucks-Chipotle deal, Russell 2000 weakness and AI…
Lennar, Part One: The Story

Lennar grew from a Miami builder into one of America’s two largest homebuilders, controlling land largely through options and land banks…
Lennar, Part Two: The Deep Dive

Lennar’s second audio program examines the homebuilder’s business for professional investors and housing analysts.
Insider activity September 2026

Asian insider buying rose 19% to US$2.4 billion across 930 September transactions, led by Grab CEO Anthony Tan’s US$30 million purchase…
AMADF · long

Amadeus It Group SA

Amadeus IT Group turns long after shares fell more than 20% since a November short call.
Vicor Update, Part Two

Vicor uses ITC exclusion-order cases to license power-module patents, with published royalty multipliers rising from 1.0x before filing to…
Expert Call | Nebius

Nebius’s 1 GW annual active-capacity target from 2027 is realistic, according to a former product manager, with greenfield data centers…
Publications we follow

Every publication on this site, hand-picked.

129 publications

Newsletters 107

X accounts we follow

Every account on this site, hand-picked.

88 accounts

Investor letters we follow

189 firms

Sectors

Ordered by how often our editor reaches for them.