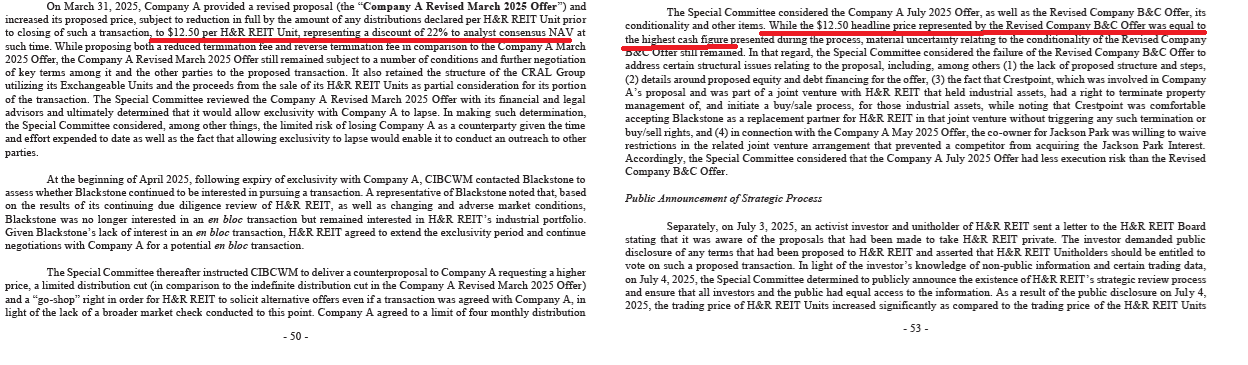
H&R REIT's proposed GO Residential transaction faces investor opposition over rejected $12.50 cash bids, insider benefits and tax…
S Nugget Capital Partner's Substack 2 clicks
Helus Pharma's HLP003 Phase 3 depression data is due in 4Q26, with $166.4 million in cash and dilution risk from a $100 million ATM…
SA  Petri Dish Reports 3 clicks
Hippo’s insurance platform posted 61% premium growth, a 95.8% combined ratio and a fifth profitable quarter as it shifted toward carrier…
S Substack von Philipp 8 clicks
Brazil Potash has secured court support and a power agreement, but financing, dilution and potash-price-sensitive EBITDA remain central…
SA  Wolf Report 3 clicks
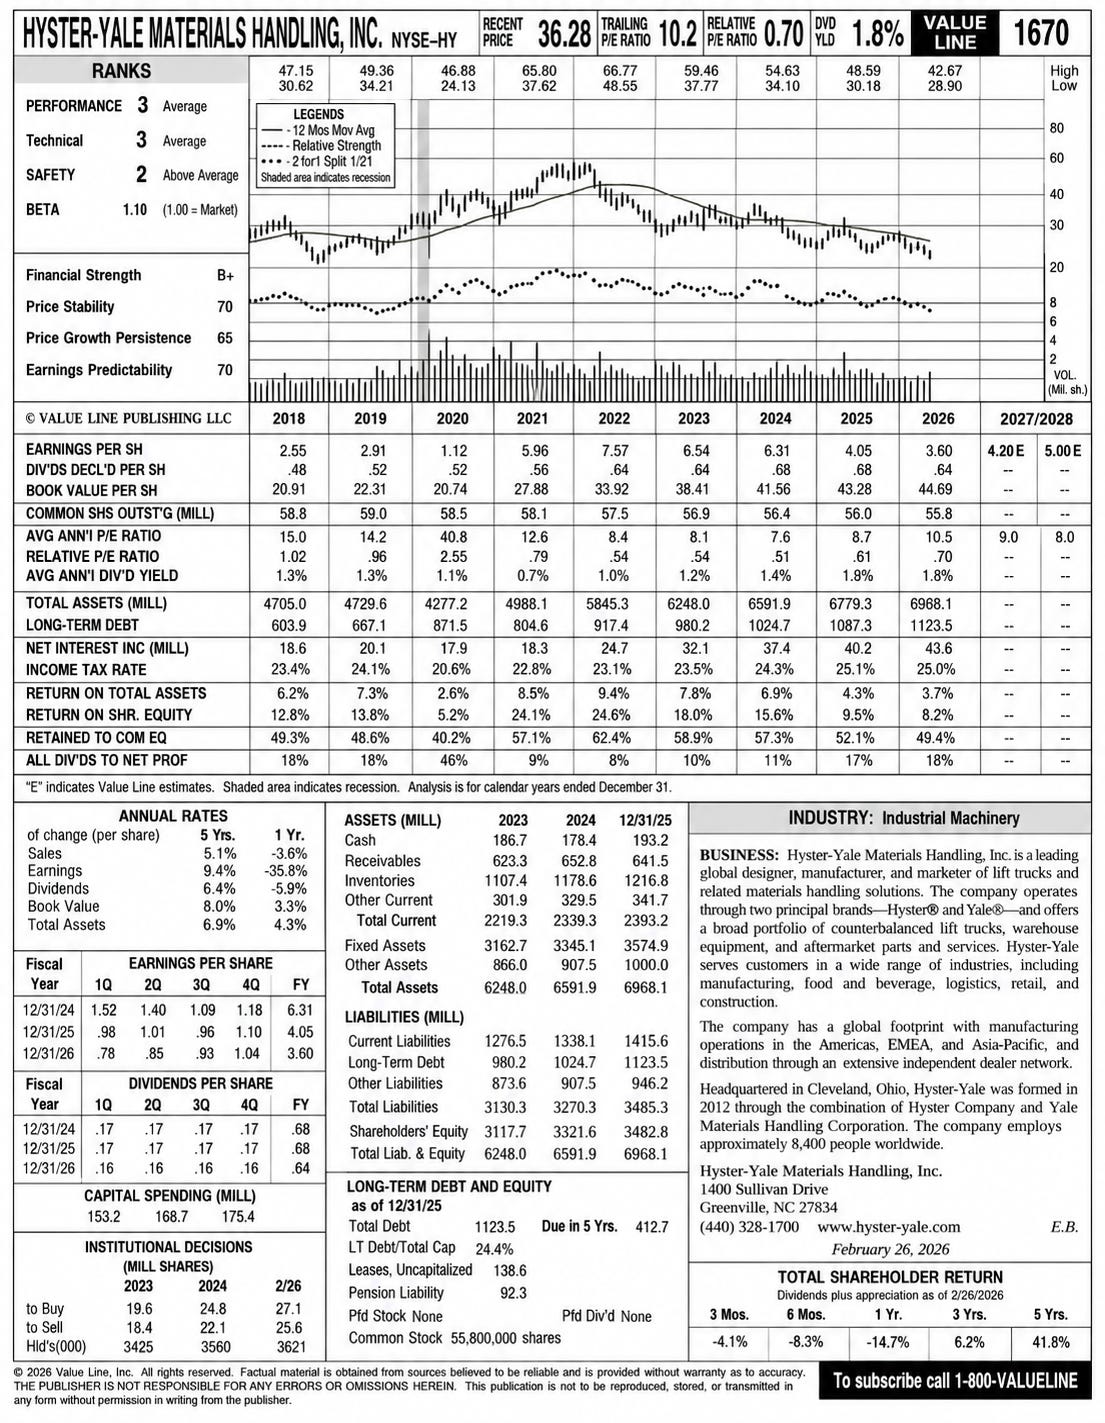
Hyster-Yale trades at 0.16 times sales as lift-truck bookings rebound and restructuring targets $85 million to $100 million in annual…
S Calvin Blissett 3 clicks
Namib Minerals posted H1 adjusted EBITDA of $19.0 million, up 76%, as higher gold prices offset lower production.
BL Atrium Research - Equity Research 2 clicks
Lesaka CEO Ali Mazanderani has bought more than $10 million of stock while pursuing a $20 to $30 valuation case through targeted…
S Mispriced Assets 5 clicks
Cogent Communications and AI data-center bottlenecks feature in a newsletter update on recruiting, financial media and conference takeaways.
S Stock Thoughts 3 clicks
Lesaka’s executive chairman has invested more than $10 million personally and targets EPS compounding above 40% through consumer, merchant…
S Mispriced Assets 2 clicks
VersaBank's Q3 revenue rose 23% and adjusted net income 27%, while a 2.19% net interest margin and 19.15x forward earnings temper its 2027…
SA  Grassroots Trading 1 click
 SRTA · long
Strata Critical Medical, SRTA, supplies organ-transport products tied to U.S. transplant growth.
BL Value Investors Club 3 clicks
MGP Ingredients trades at 0.74 times tangible book after whiskey oversupply drove sales declines and more than $400 million of impairments.
S Dismissed & Asset-Backed 1 click
Solid Power reported a $0.11 Q2 loss and $419.3 million of cash, with its electrolyte pilot line and BMW and SK On validation central to…
SA  Quad 7 Capital 2 clicks
Digimarc’s gift-card watermark pilot found zero fraud at Schnucks, while its retailer pipeline rose to 31 from one in 2025 despite…
Nyxoah's Genio implant could reach CCC patients after an FDA label expansion, targeting 30% of the obstructive sleep apnea device market by…
SA  Stephen Tobin 3 clicks
OMSE 2026-10-05 Latticework’s briefing questions AI capex returns while featuring Close Brothers, Green Landscaping and OMS Energy Technologies.
S Latticework by MOI Global 2 clicks
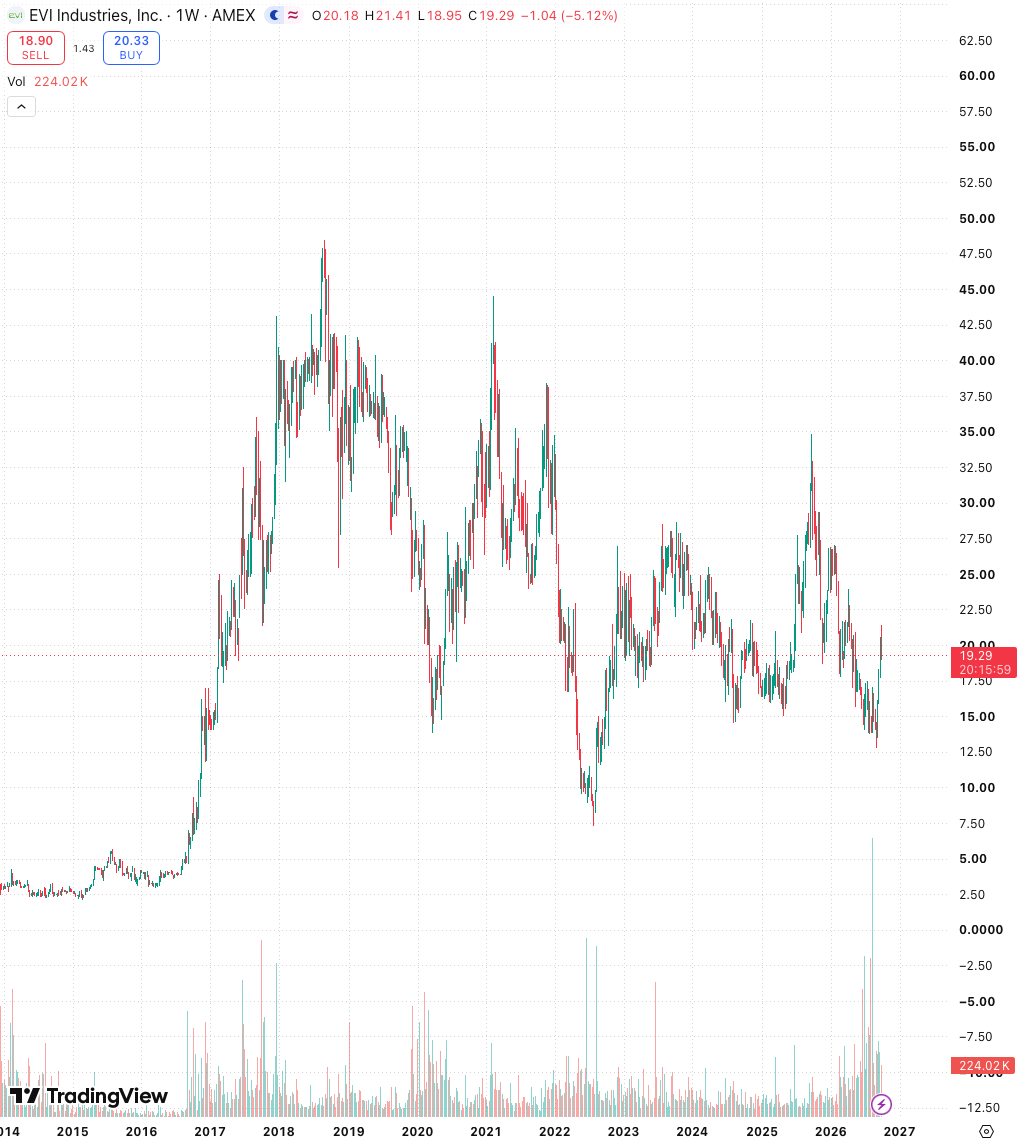
EVI Industries says its ERP and service-platform build is largely complete, testing whether 10.8% revenue growth can finally outpace…
S Kairos Research 2 clicks
Huckleberry.AI trades near $3.30 against $221 million of cash and $900 million-plus of NOLs after selling its operating business, creating…
S Hidden Rock Capital's Newsletter 5 clicks
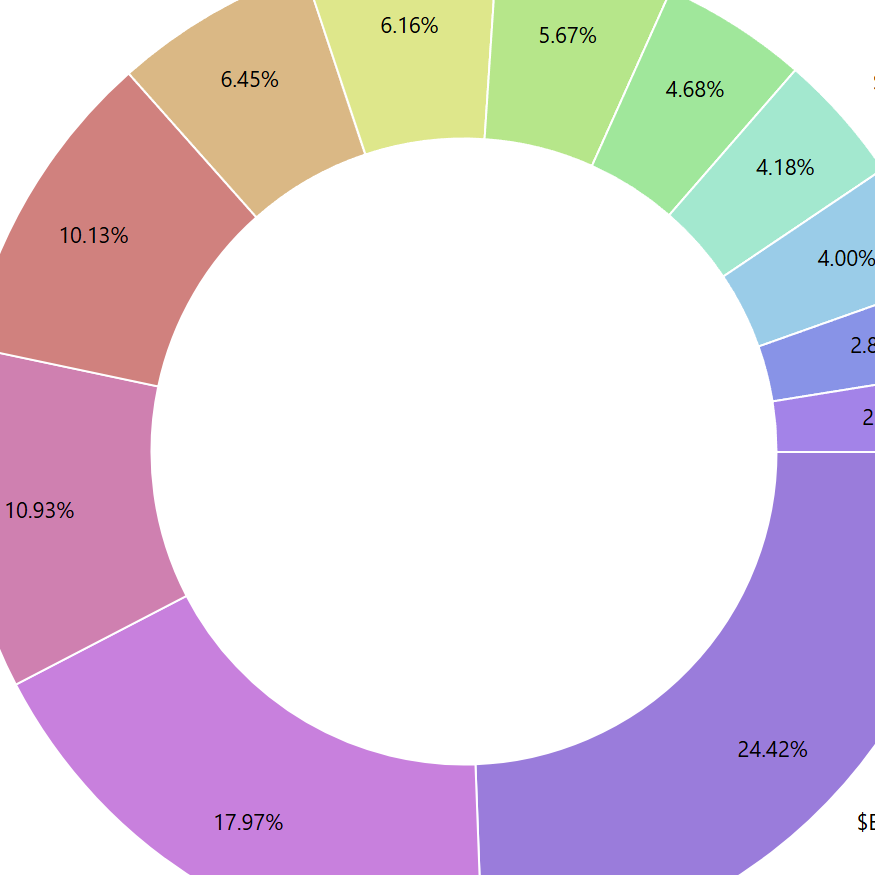
Entravision, the portfolio’s largest position, fell more than 40% from its highs as Q3 returns dropped to 37.8% YTD.
S The Mikro Kap 3 clicks
Washington Trust Bancorp offers a 5.8% dividend yield, with C&I loan growth supporting ROE despite 40% commercial real estate loan…
SA  Sorrento Research