Liquidia’s Yutrepia sales reached $170.4 million in Q2 2026, while a patent ruling threatens its PH-ILD label but leaves PAH sales and a…
S Trade Ideas Flow Oct 12 4 clicks
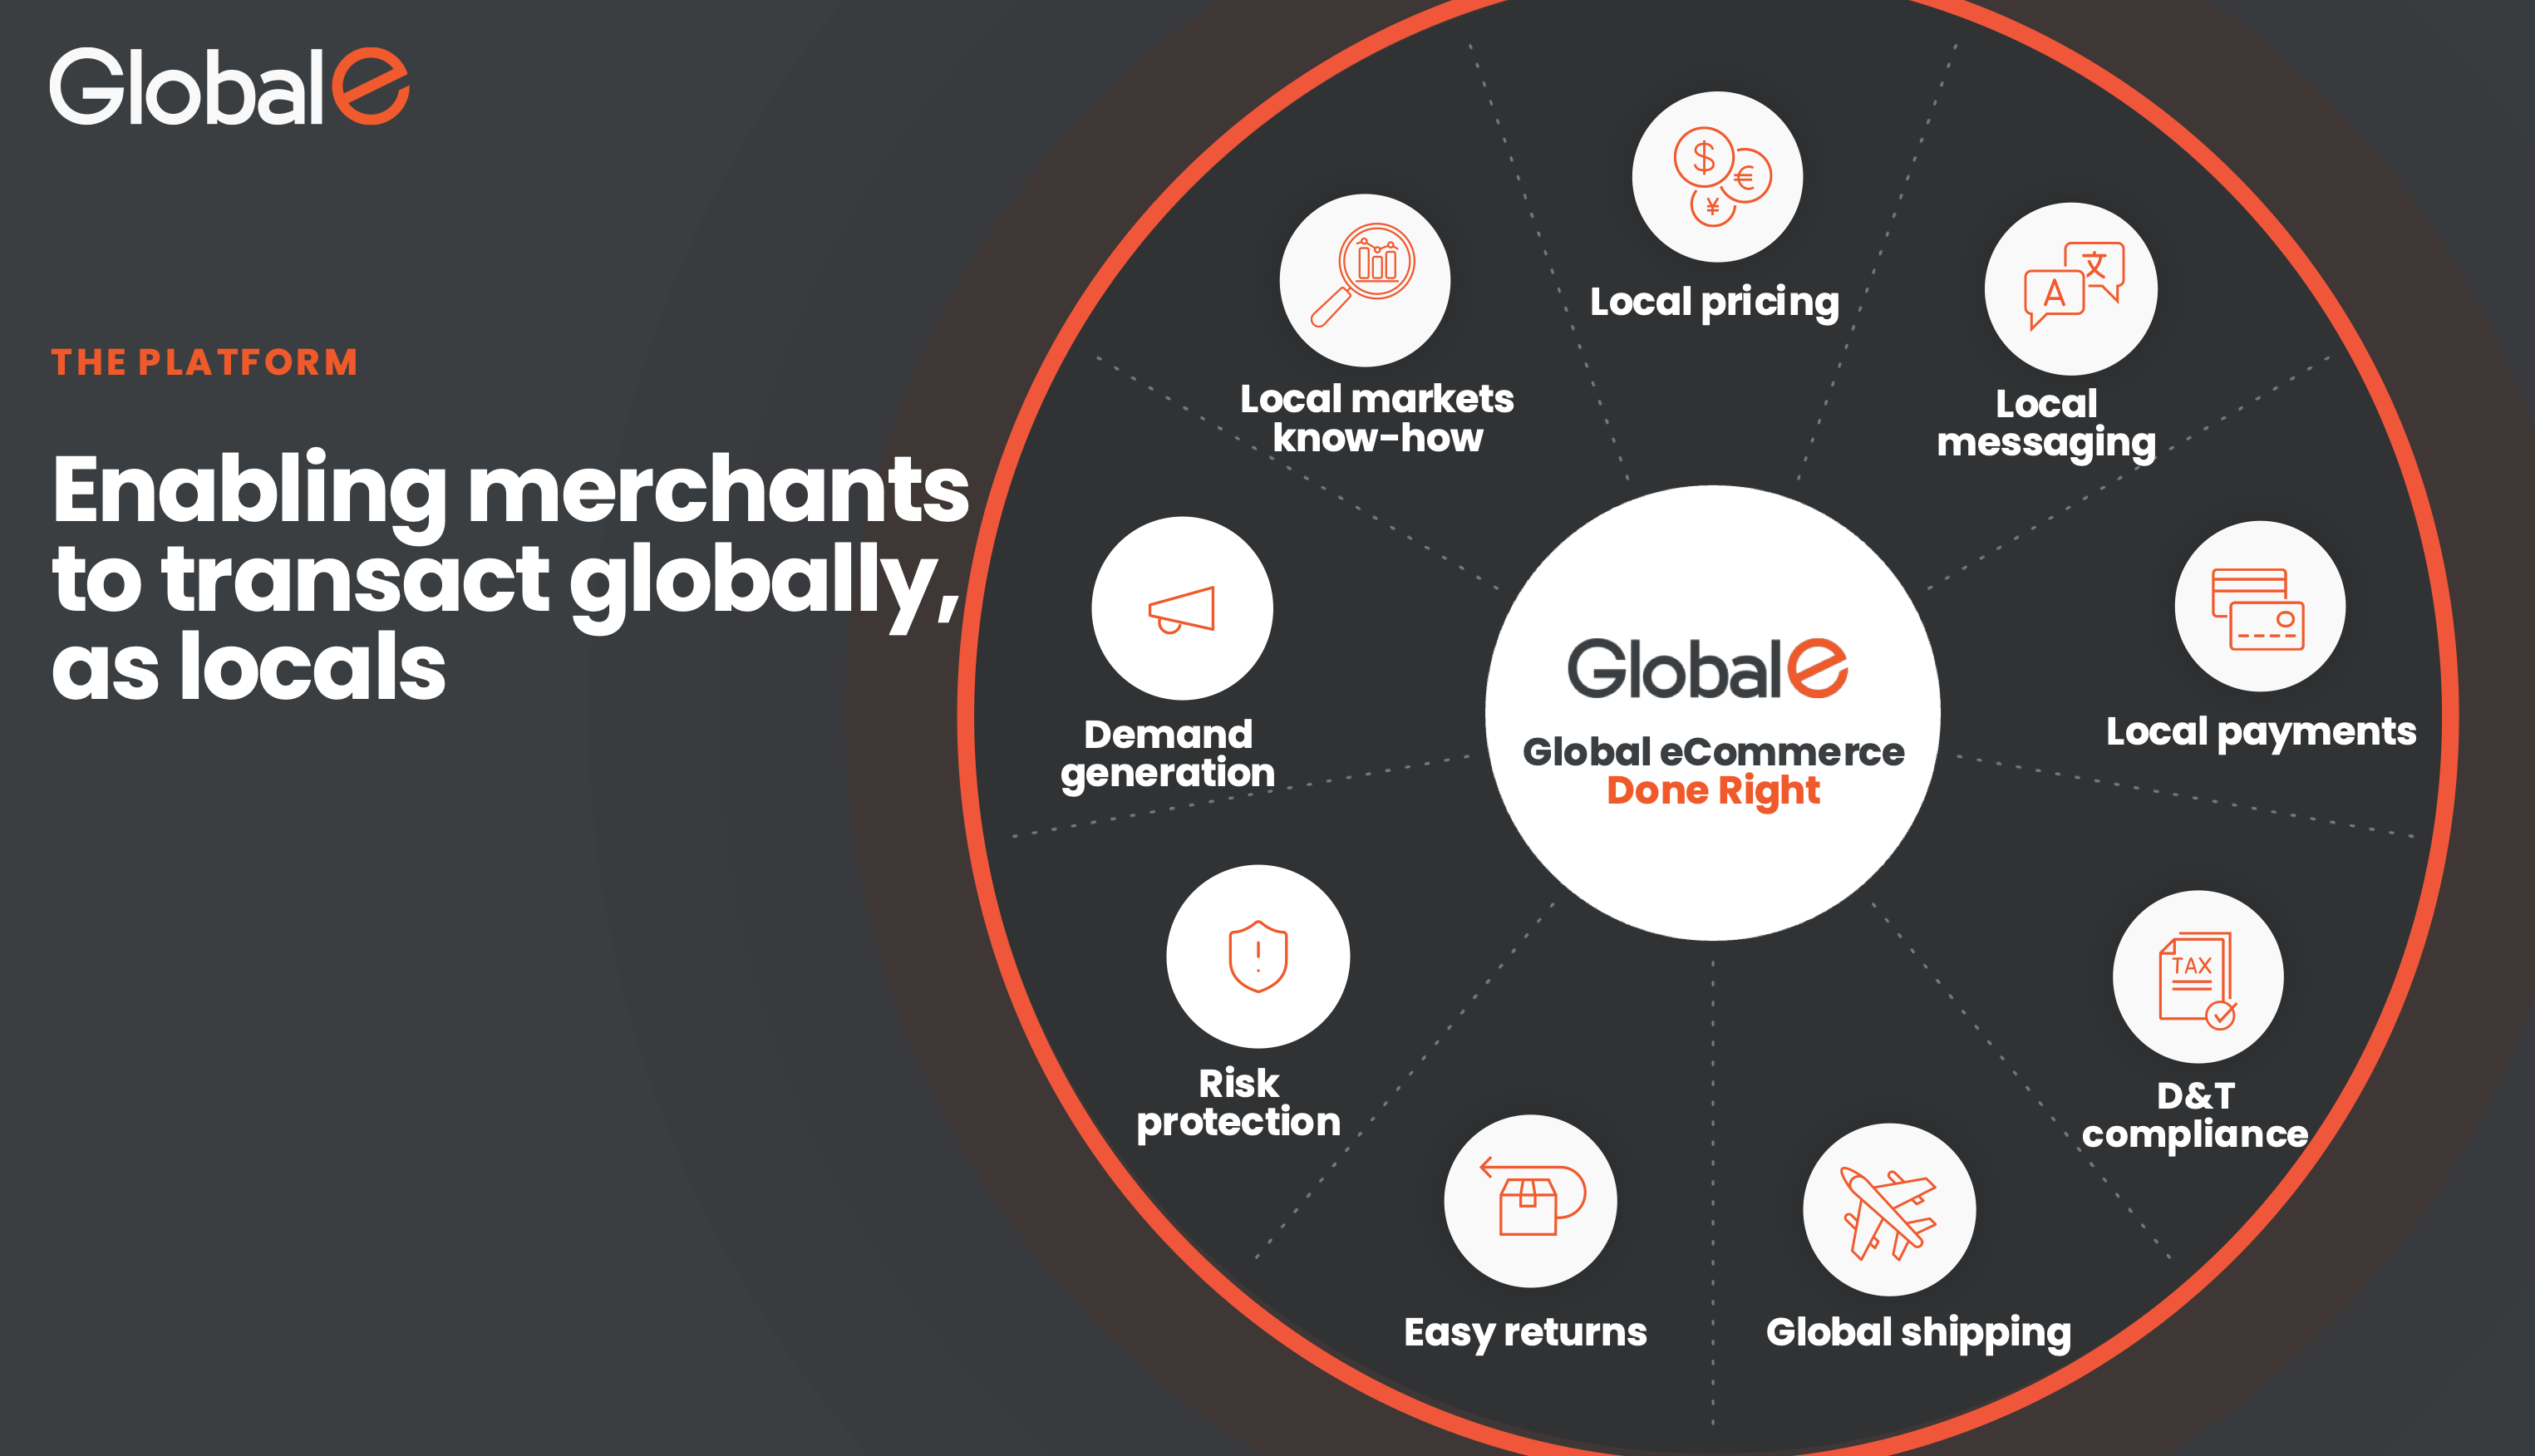
Global-e provides cross-border merchant-of-record, payments, tax and fulfillment services to more than 1,500 brands, including Shopify…
S Substack von Philipp Oct 12 6 clicks
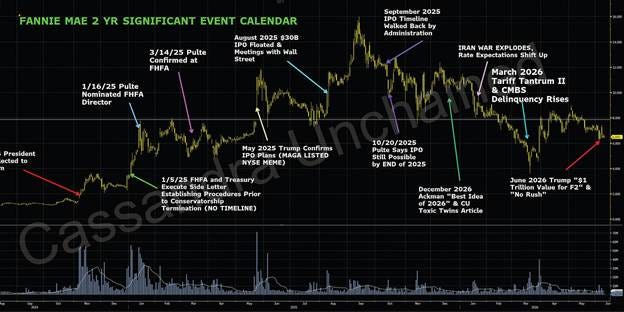
Fannie Mae and Freddie Mac common shareholders face at least 90% dilution if Treasury converts its growing senior preferred stakes into…
S Cassandra Unchained Oct 11 5 clicks
Inter & Co, Brazil’s second-largest neobank, grew over 20% with controlled delinquencies and 15% book-value compounding while trading at…
S Capitalist Letters Oct 11 7 clicks
Glaukos is expanding from glaucoma devices into sustained drug delivery and corneal cross-linking, but GKOS's premium valuation leaves…
SA Myriam Alvarez Oct 11 4 clicks Brazil’s October 25 runoff puts Bolsonaro’s likely victory at the center of a bullish regional-stock case; Golar LNG (GLNG) also reports…
S WHAT ARE WE DOING? “Contrarians At The Gate” Oct 9 3 clicks
Blackstone Secured Lending Fund faces a likely dividend cut after its first shortfall in 28 quarters, despite 1.8% non-accruals, $2.8…
SA Rubicon Associates Oct 9 1 click Legence trades at 10.4x EV/aEBITDA with a $5.7 billion backlog, as AI data center installations drive growth and expand its maintenance…
S Monte Independent Investment Research Oct 9 2 clicks
OceanaGold trades below its mine value despite US$655 million of cash and no debt, with production set to dip before Wharekirauponga begins…
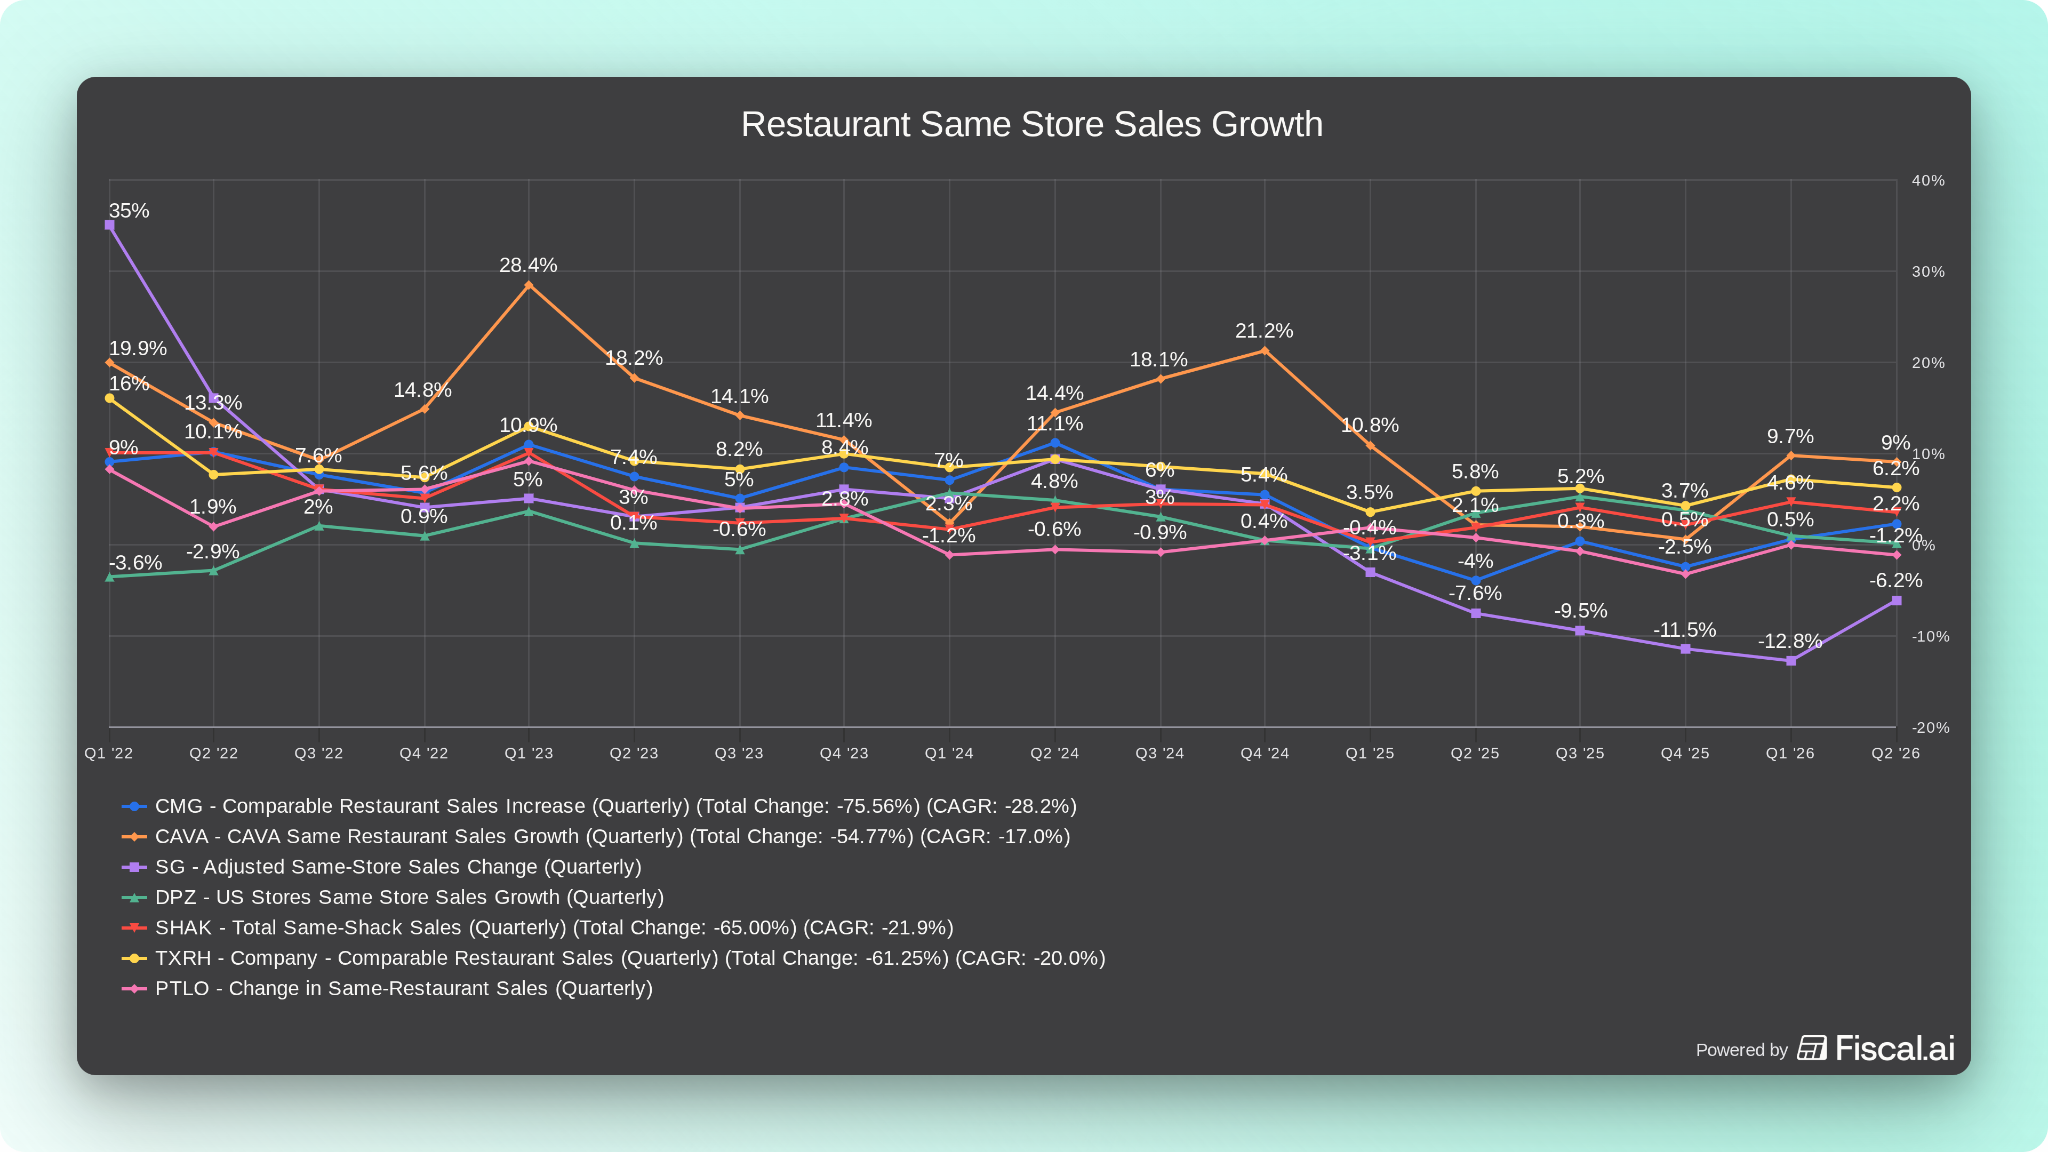
SA The Bullionaire Oct 9 1 click Cava’s $3 million AUVs, 25.1% restaurant margins and sector-leading same-store sales support its expansion case as awareness rose from 40%…
S Emerging Moats Research Oct 9 6 clicks
PTRN · short Pattern Group is a fragile consumer business targeted on the short side.
BL Value Investors Club Jul 15 3 clicks
Penguin Solutions grew FY2026 revenue 26% as AI data-center and memory demand expanded, while negative free cash flow and cyclical memory…
SA Investor Overview Oct 12 4 clicks Special-situations survey profiles 26 activist, capital-return, M&A and strategic-alternative catalysts, led by buybacks at Under Armour,…
S Latticework by MOI Global Oct 8 2 clicks
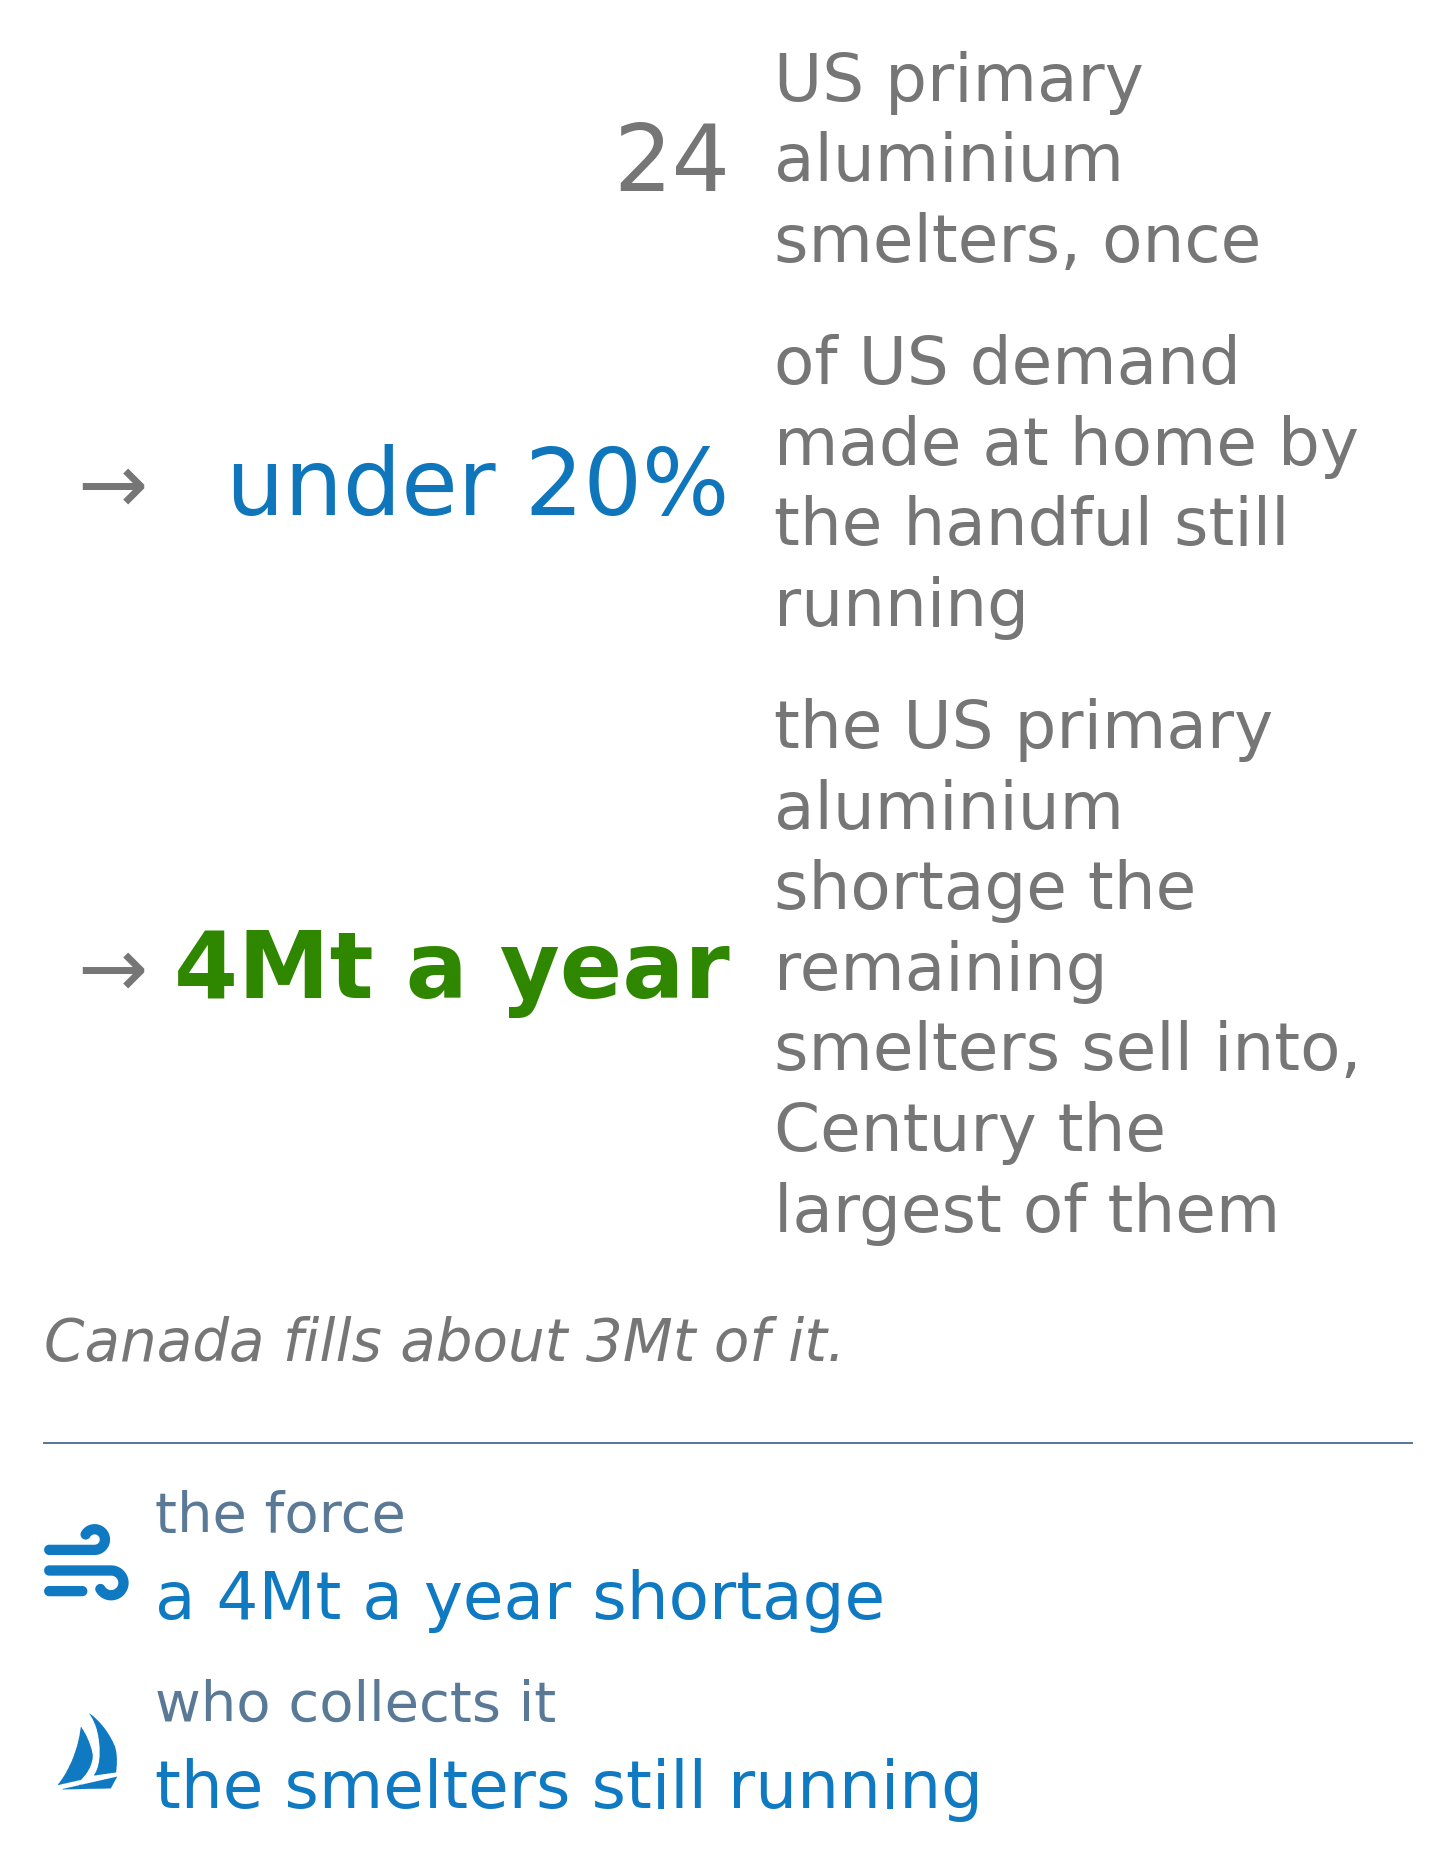
US aluminium tariffs, European glass automation and Foraco’s constrained drilling fleet create multi-year pricing tailwinds, with Century…
Millrose told Goldman its Lennar purchases had rent-to-own tenants lined up, but most analyzed homes were advertised for rent and showed…
BL Hunterbrook Oct 8 4 clicks
Golar LNG ordered a $2.45 billion fourth FLNG vessel, targeting 3.5MTPA of capacity and $400 million in annual EBITDA under a 20-year…
S Monte Independent Investment Research Oct 8
Maase, a $5B AI infrastructure company with sub-$50M annualized revenue and persistent losses, faces governance concerns over super-voting…
SA Wolf Report Oct 8 1 click Salad and Go filed Chapter 11 after its Texas and Oklahoma expansion failed, seeking to sell 65 leases to Dutch Bros for $105 million as 7…
S PETITION Oct 7 3 clicks
Astronics targets $1.02 to $1.04 billion in 2026 revenue after adjusted operating margin reached 20.3%, with Boeing representing 12% of…
SA Jordan Aquilina Oct 6 Golar LNG’s fourth FLNG vessel targets 3.5MTPA capacity and a 2029 delivery, supporting projected adjusted EBITDA above $1 billion in…
S Monte Independent Investment Research Oct 6 1 click