Vicor uses ITC exclusion-order cases to license power-module patents, with published royalty multipliers rising from 1.0x before filing to…
S CV's Substack Oct 12 5 clicks
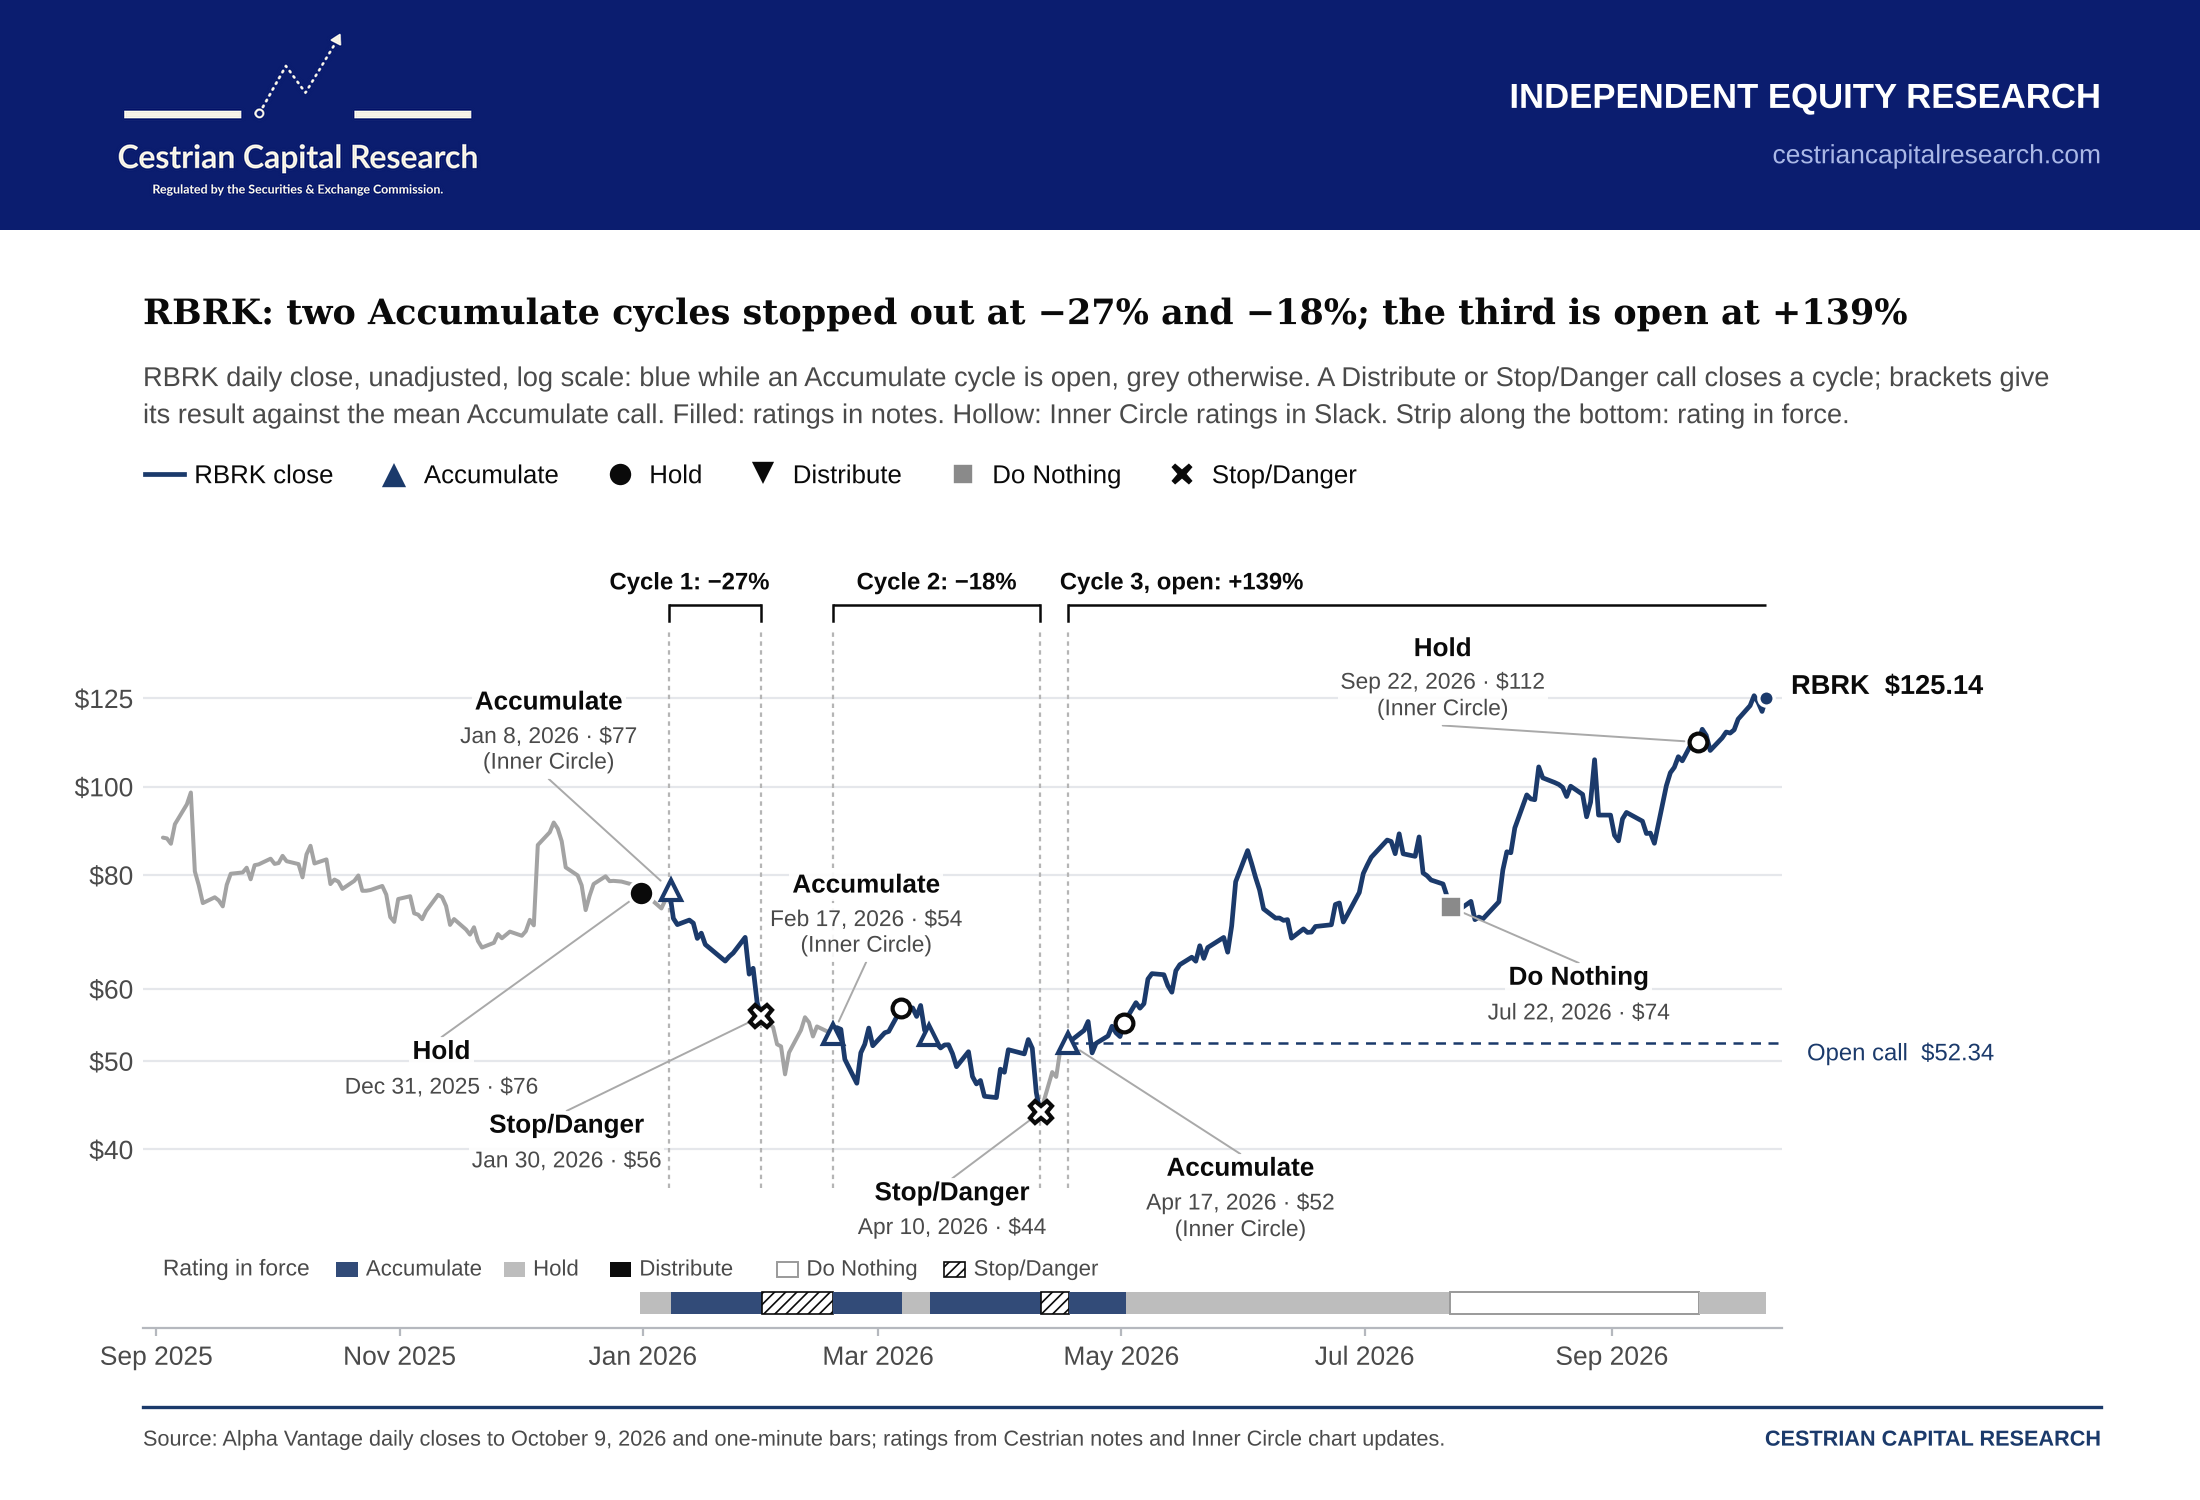
Rubrik posted 38% Q2 revenue growth to $427.3 million, but Cloud ARR growth slowed to 39% and its enterprise value reached 15.7 times…
BL Cestrian Capital Research Oct 12 4 clicks
Nebius’s 1 GW annual active-capacity target from 2027 is realistic, according to a former product manager, with greenfield data centers…
S P Equity Research Oct 12 5 clicks
Charles Lemonides argues the 18-year bull market has not reached its late-stage liftoff, pairing value-oriented semiconductor longs with…
YT The Monetary Matters Network Oct 12 9 clicks
Bristlemoon Global Fund lost 8.4% in the September quarter and added shorts in Campbell’s, REA Group, MasterBrand and Polaris amid narrow…
S Bristlemoon Capital Oct 12 11 clicks
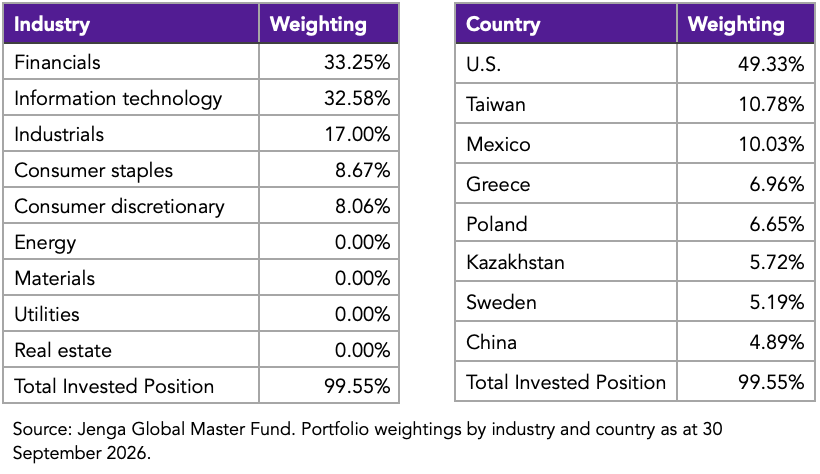
Jenga Global Master Fund returned 8.10% in Q3 2026, added Adobe and Mexican airports, and later initiated S&P Global.
S Global Outperformers Oct 12 3 clicks
Howmet Aerospace posted 24% Q2 revenue growth and 46% adjusted EPS growth, but HWM trades about 87% above a $120.69 DCF fair-value estimate.
SA Alexander I. Velasquez Oct 12 2 clicks Liquidia’s Yutrepia sales reached $170.4 million in Q2 2026, while a patent ruling threatens its PH-ILD label but leaves PAH sales and a…
S Trade Ideas Flow Oct 12 4 clicks
Magna International’s gross margin reached 14.7% and operating margin 5.6%, supporting double-digit earnings growth alongside EV investment…
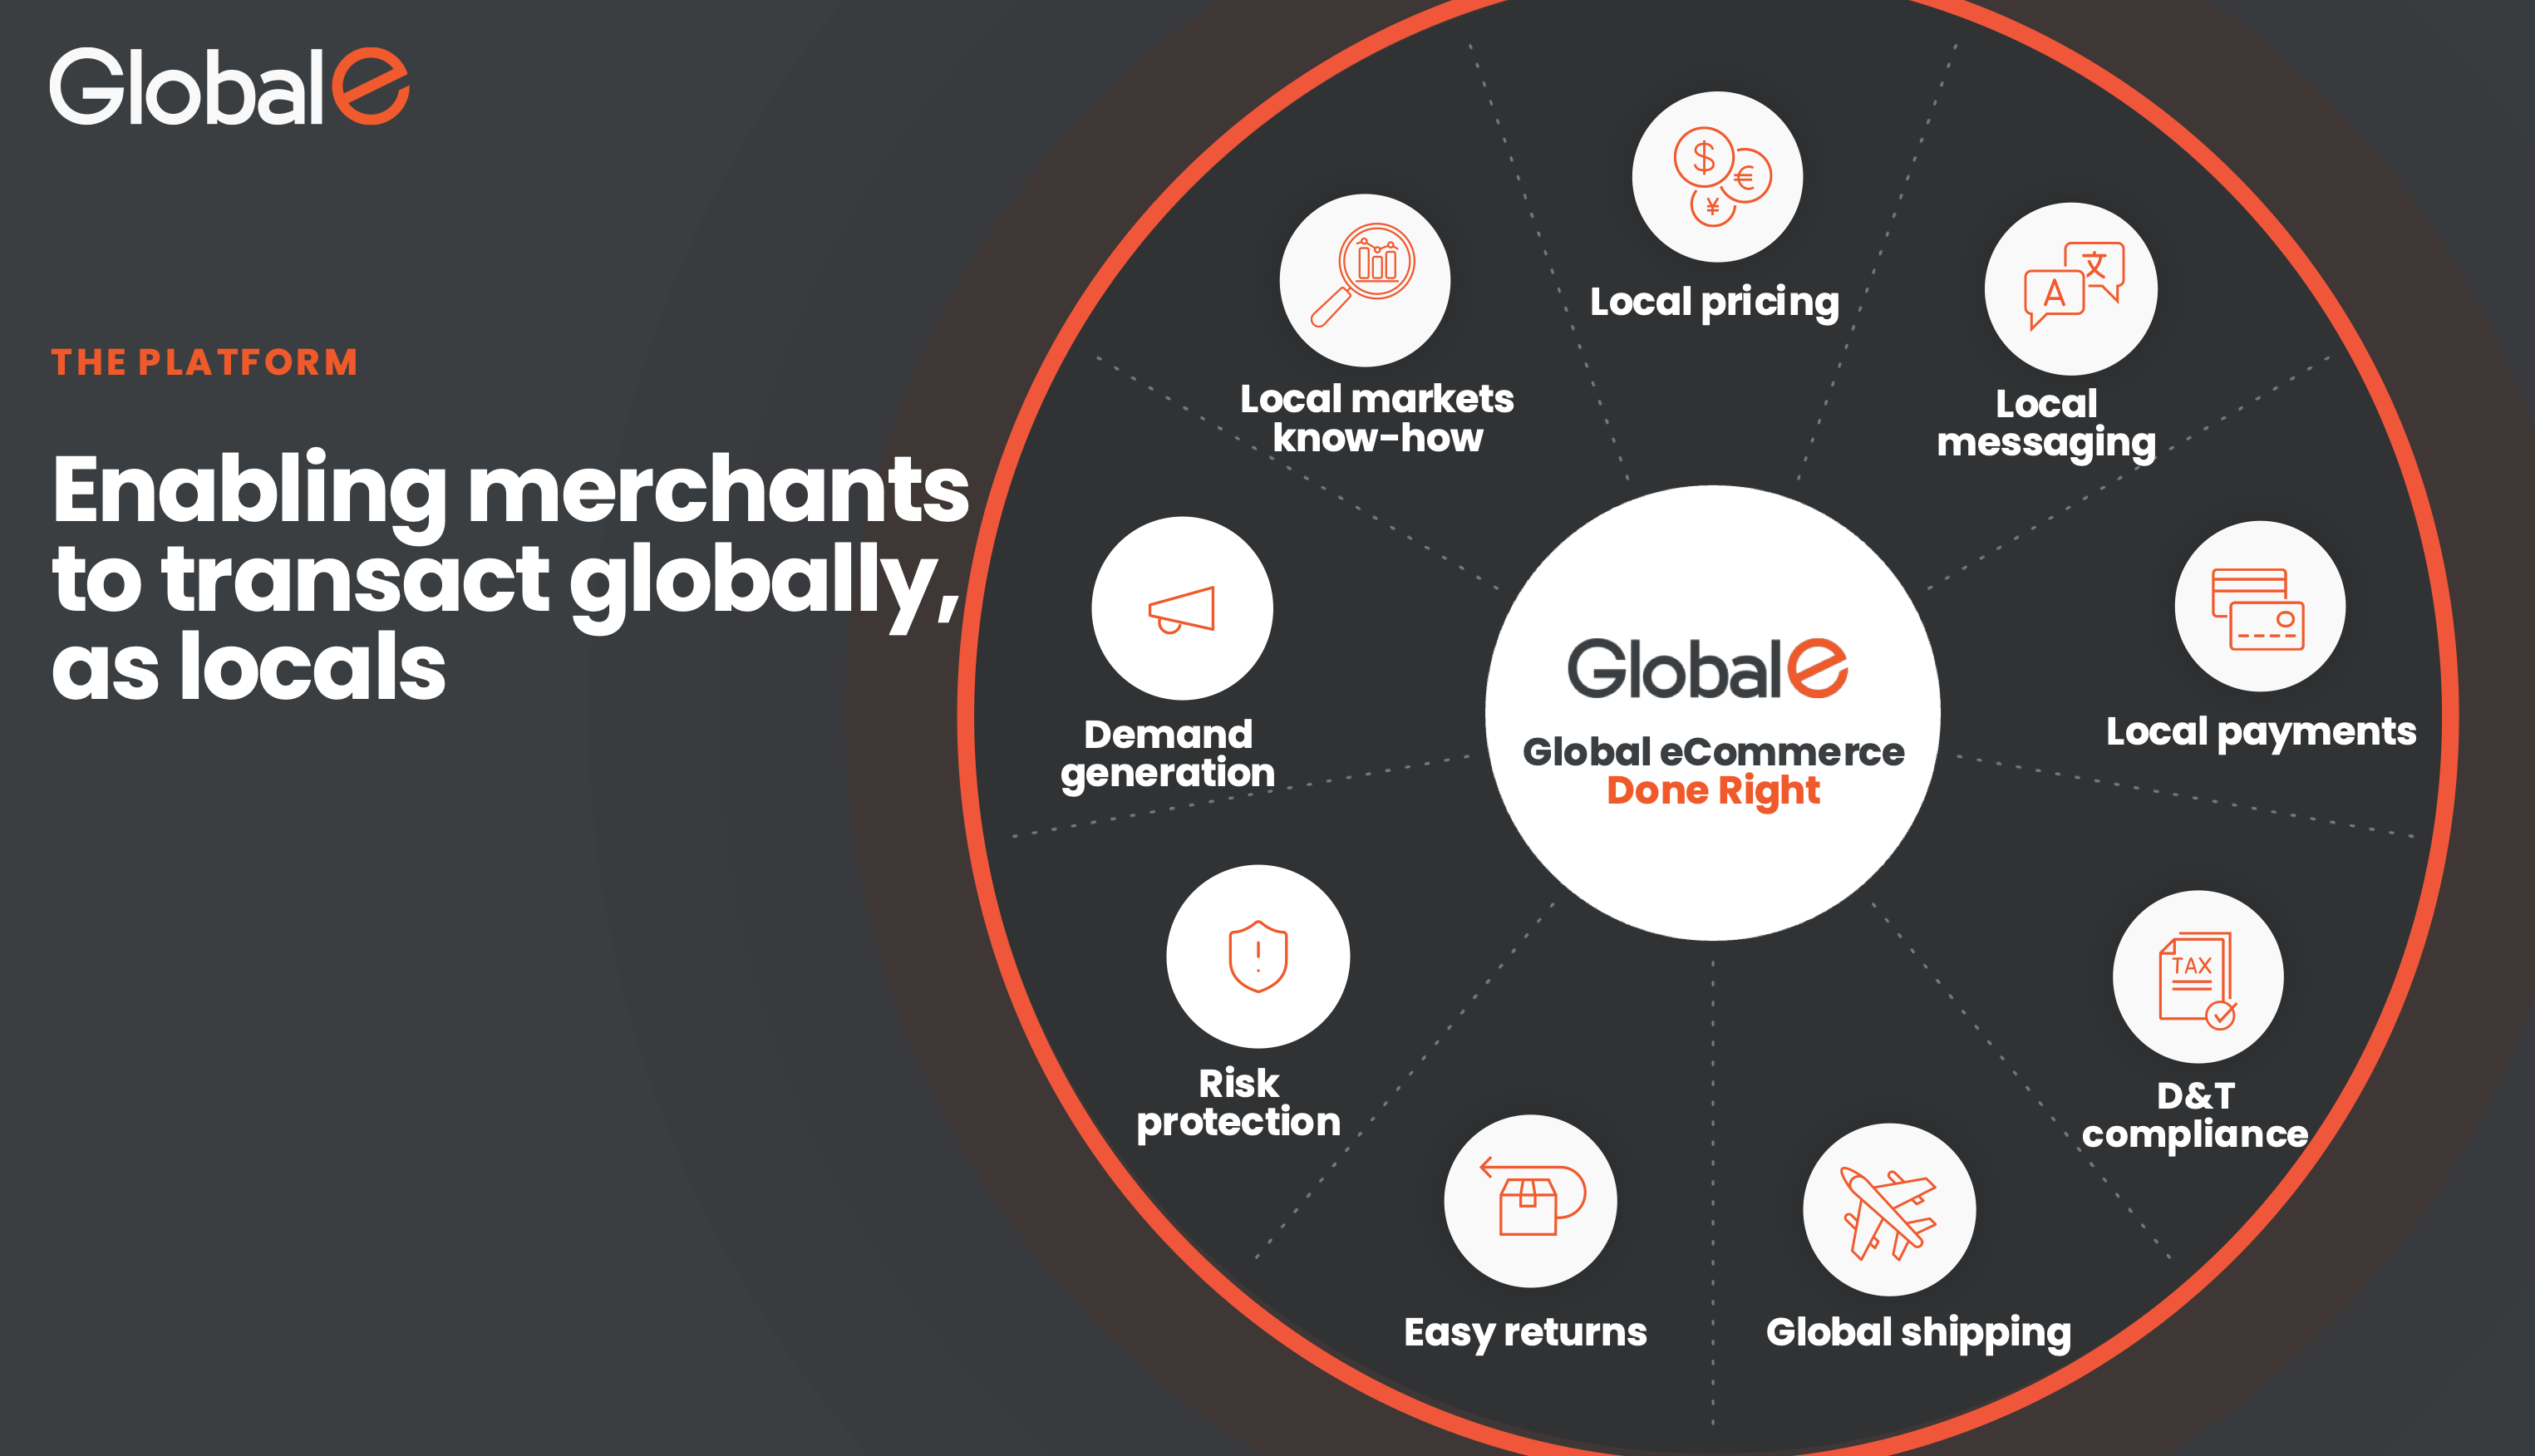
SA David Zanoni Oct 12 1 click Global-e provides cross-border merchant-of-record, payments, tax and fulfillment services to more than 1,500 brands, including Shopify…
S Substack von Philipp Oct 12 6 clicks
PTRN · short Pattern Group is a fragile consumer business targeted on the short side.
BL Value Investors Club Jul 15 3 clicks
Cognex expects 15% revenue growth this year as its RealSense acquisition expands machine-vision exposure to robotic perception, logistics,…
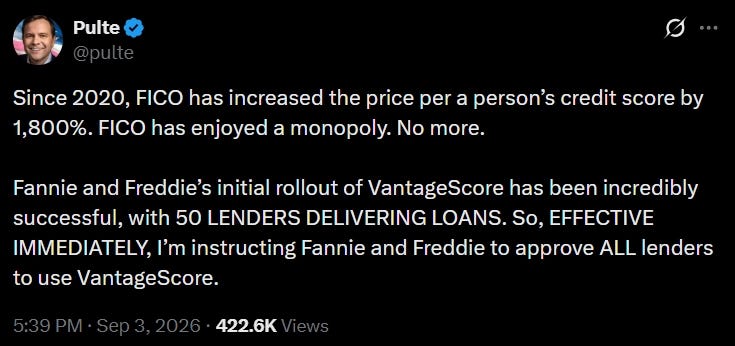
SA Fountainhead Oct 12 2 clicks FICO’s mortgage credit-score monopoly sits at the center of a GSE-dominated U.S.
S scuttleblurb Oct 12 4 clicks
Penguin Solutions grew FY2026 revenue 26% as AI data-center and memory demand expanded, while negative free cash flow and cyclical memory…
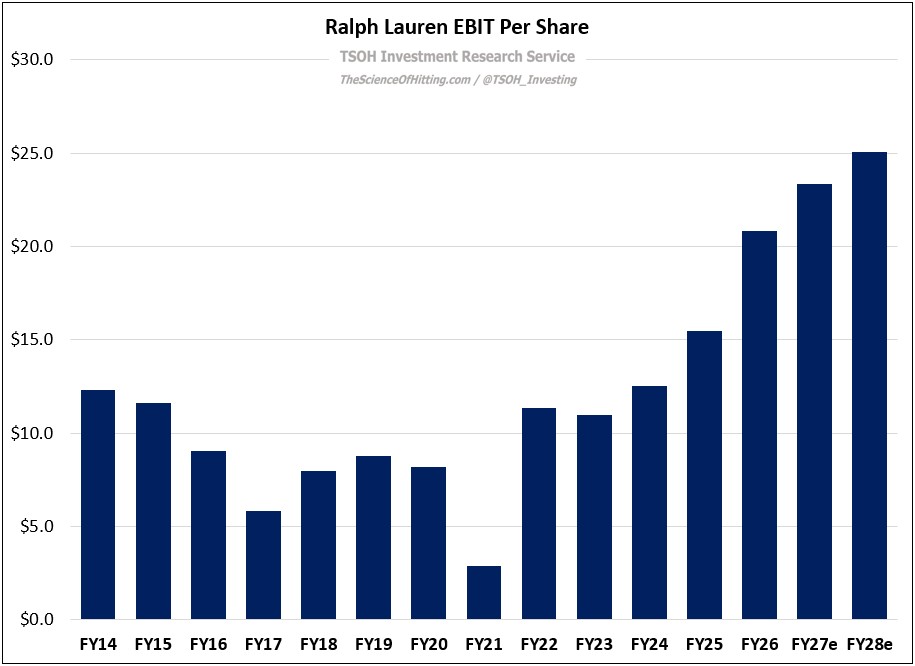
SA Investor Overview Oct 12 5 clicks Ralph Lauren’s 2017 CEO change put Patrice Louvet in charge of reversing nine quarters of same-store sales declines and restoring the…
S TSOH Investment Research Oct 12 1 click
Dassault Aviation leads a 53-pitch roundup with a €45 billion order book against €7.4 billion of sales and a 26.6% Thales stake.
S Capital Employed Oct 12 4 clicks
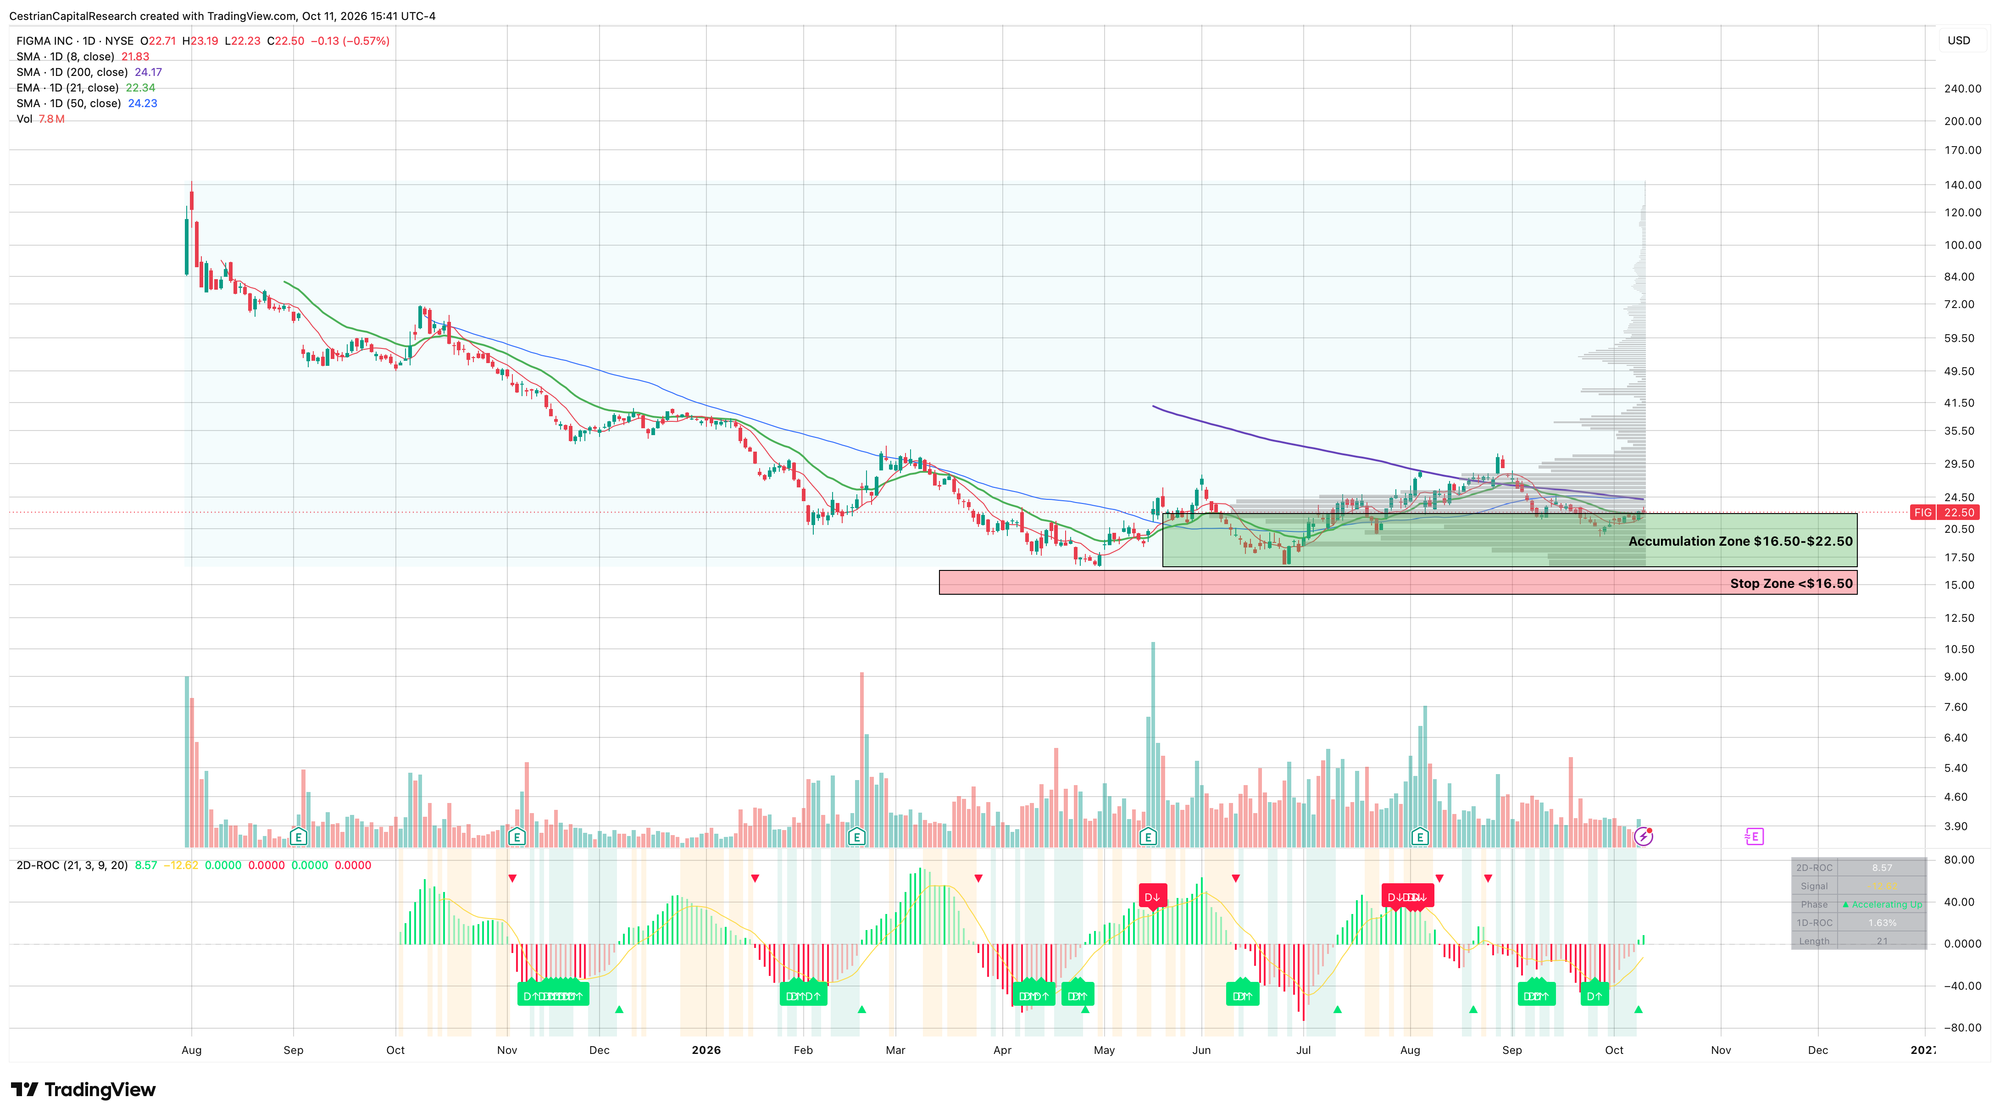
Figma’s Q2 revenue rose 48% to $370.1 million as AI credit adoption lifted retention to 136%; FY2026 revenue guidance increased to $1.463…
BL Cestrian Capital Research Oct 11 2 clicks
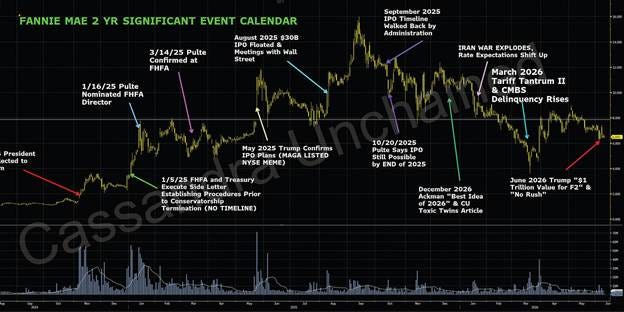
Fannie Mae and Freddie Mac common shareholders face at least 90% dilution if Treasury converts its growing senior preferred stakes into…
S Cassandra Unchained Oct 11 5 clicks
Rocket Lab’s $2.36 billion backlog and Iridium acquisition support growth, but delayed Neutron testing, dilution and losses leave RKLB…
SA Bohdan Kucheriavyi Oct 11 7 clicks Inter & Co, Brazil’s second-largest neobank, grew over 20% with controlled delinquencies and 15% book-value compounding while trading at…
S Capitalist Letters Oct 11 7 clicks