H&R REIT, an opportunity in a corrupt process
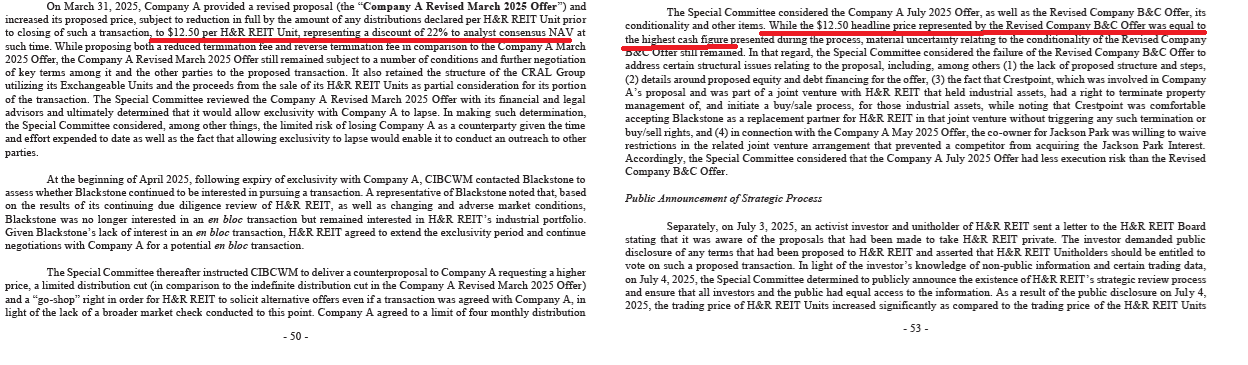
H&R REIT's proposed GO Residential transaction faces investor opposition over rejected $12.50 cash bids, insider benefits and tax allocation, with critics seeking to block the deal.
H&R REIT's proposed GO Residential transaction faces investor opposition over rejected $12.50 cash bids, insider benefits and tax allocation, with critics seeking to block the deal.
likely to return to $3 imo $CD https://t.co/0ff0aX4f7D
@Imperium1136 @DeepSailCapital agree, though think $MRNX is the better vehicle
@finphysnerd Ackman's been on a real heater lately with his smallcap pumps. Remember $HTZ?
Dating-App Company Bumble in Advanced Talks to Go Private at $1 Billion Valuation $BMBL https://t.co/lTRHp5bYTo
Too small, you could buy for triple the stock price and do beautifully as a private equity firm even given the worst case outcome due to cybersecurity which is loss of momentum in sales and a bit of churn. Would be more than made up for by the amount of leverage $CCLD could withstand, how many acquisitions they could do with a deeper and cheaper cost of capital
Namib Minerals posted H1 adjusted EBITDA of $19.0 million, up 76%, as higher gold prices offset lower production.
Lesaka CEO Ali Mazanderani has bought more than $10 million of stock while pursuing a $20 to $30 valuation case through targeted…
Cogent Communications and AI data-center bottlenecks feature in a newsletter update on recruiting, financial media and conference takeaways.
Lesaka’s executive chairman has invested more than $10 million personally and targets EPS compounding above 40% through consumer, merchant…
Latticework’s briefing questions AI capex returns while featuring Close Brothers, Green Landscaping and OMS Energy Technologies.
Old Market Capital, a delisted holding company owning a rural fiber network, trades below comparable network valuations after institutional…

Leslie’s and nine affiliates filed Chapter 11 in Texas on September 30, 2026, after 18 months of deteriorating performance.
Leslie’s, the pool-supplies retailer, filed Chapter 11 after deteriorating operations, pricing and inventory missteps, and a burdensome…
Pyxis Oncology's recent financing extends MICVO's runway to clinical milestones as the oncology candidate works to establish a safe,…
 Myriam Alvarez 2 clicks
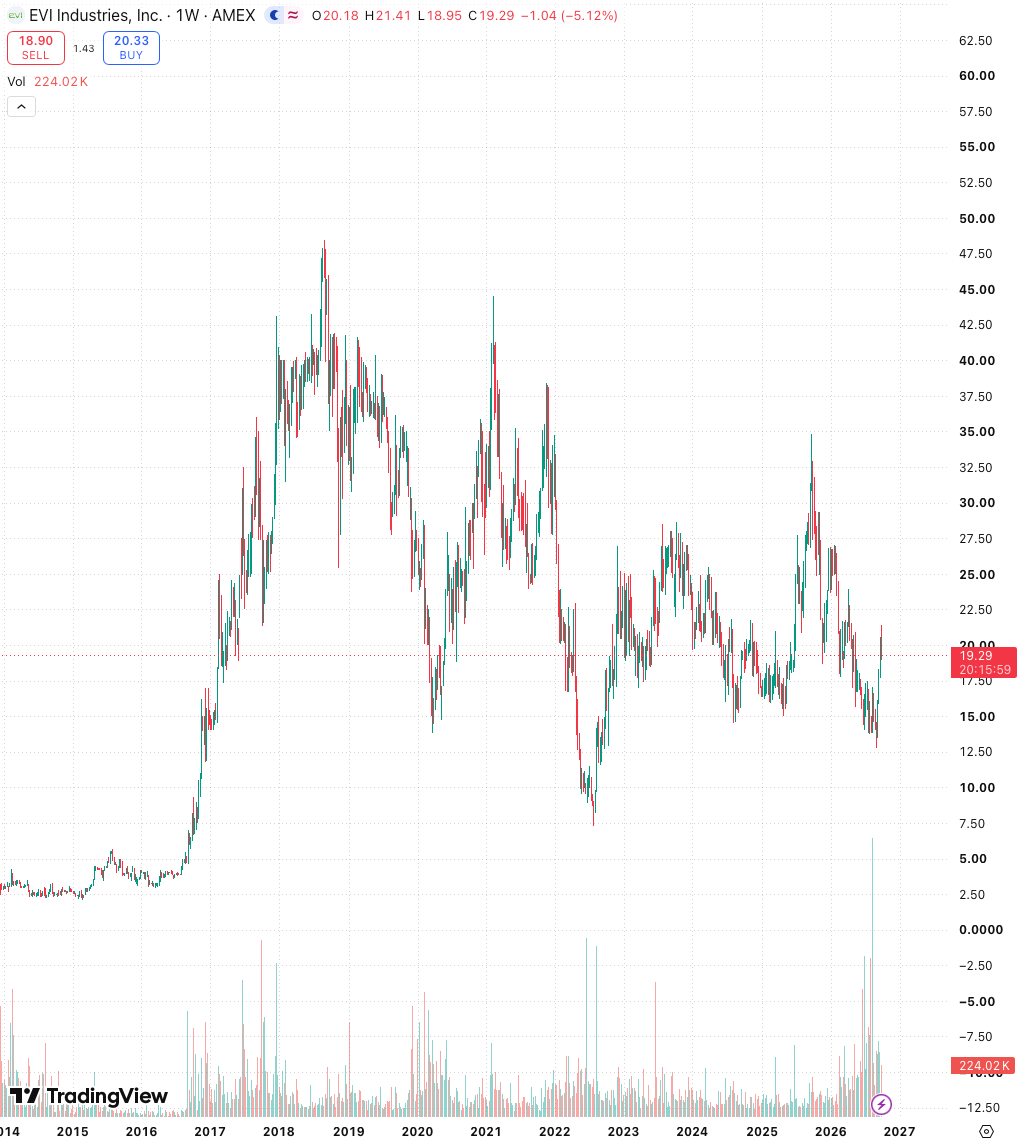
EVI Industries says its ERP and service-platform build is largely complete, testing whether 10.8% revenue growth can finally outpace…
 HNRG · long
Hallador Energy, a coal producer, is pitched as a long based on five value components and potential 2026 catalysts.
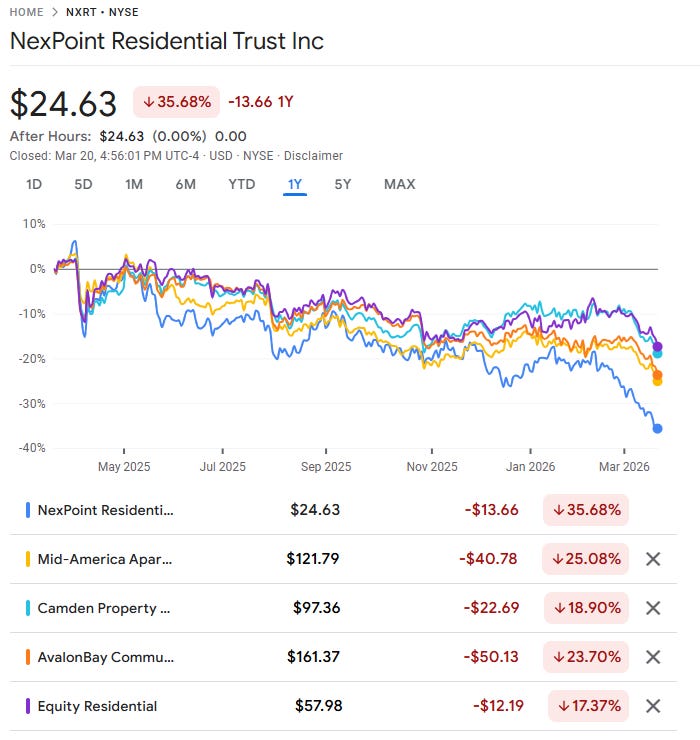
NexPoint Residential is being added despite weak multifamily performance, with insider ownership and a transaction-ready structure…
Solitron Devices' $27.5 million backlog rose 124% year over year as its sole-source military semiconductors support AMRAAM and HIMARS,…
New Fortress Energy’s restructuring cancels its 12% 2029 notes for 94.3% of BrazilCo, $974 million of New NFE preferred and 25.8% of New…
Lands’ End’s March 19 results could clarify the WHP IP joint venture, debt paydown and retained stake, supporting a rerating beyond the…
MAPS reported $39.8 million of FY25 adjusted EBITDA and $62.4 million of cash as a holder builds a record around a possible affiliated bid.
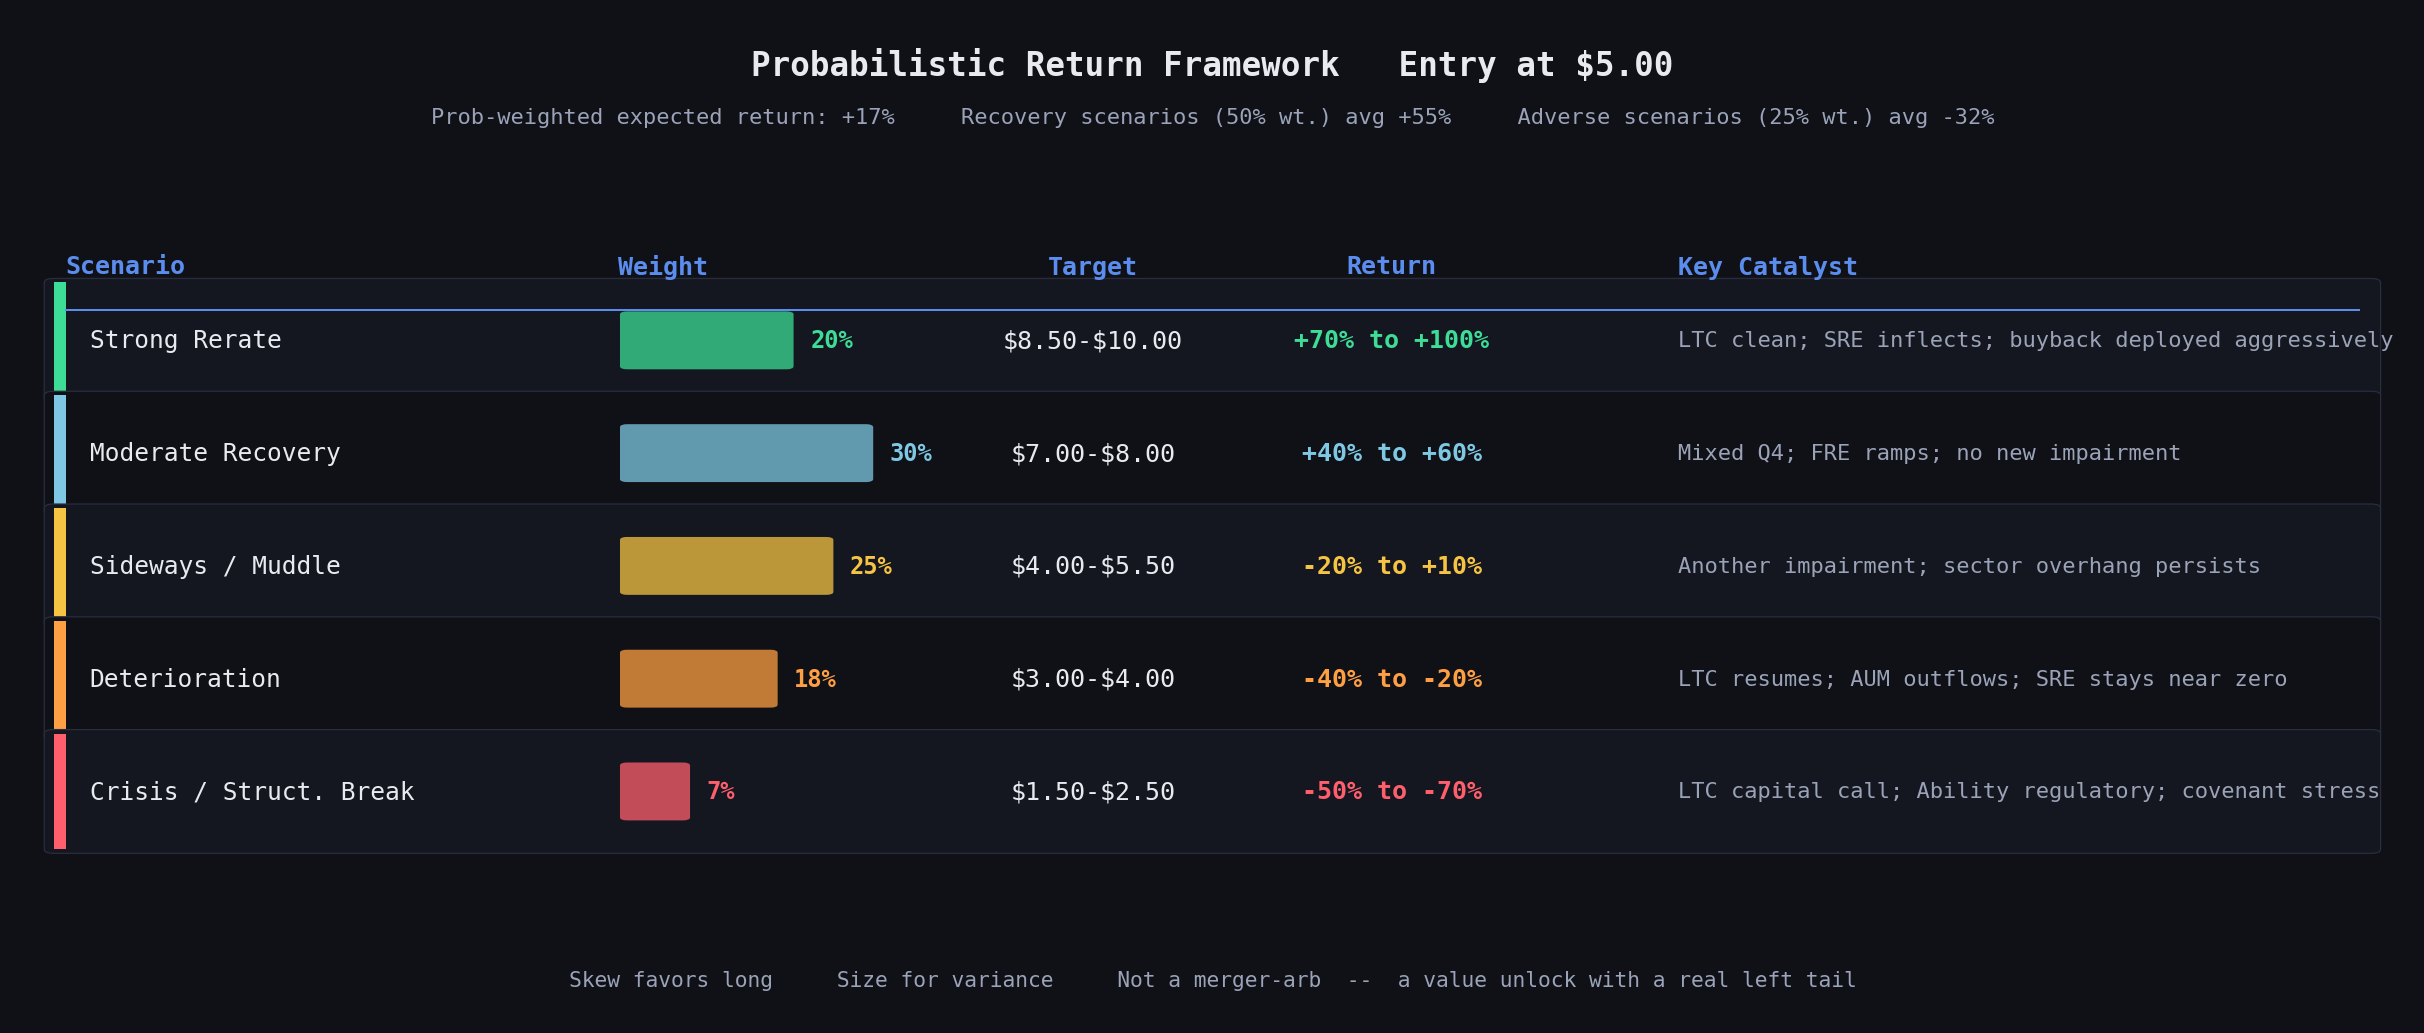
Mount Logan Capital repurchased shares at $9.43 before an oversubscribed tender and forced selling drove them to $5.00, below $10.39 book…

Hallador’s 1 GW Merom plant could supply a proposed 1,000-acre Sullivan County data center, with local filings and Stantec references tying…

Theravance Biopharma began a strategic review after a failed Phase 3 trial.
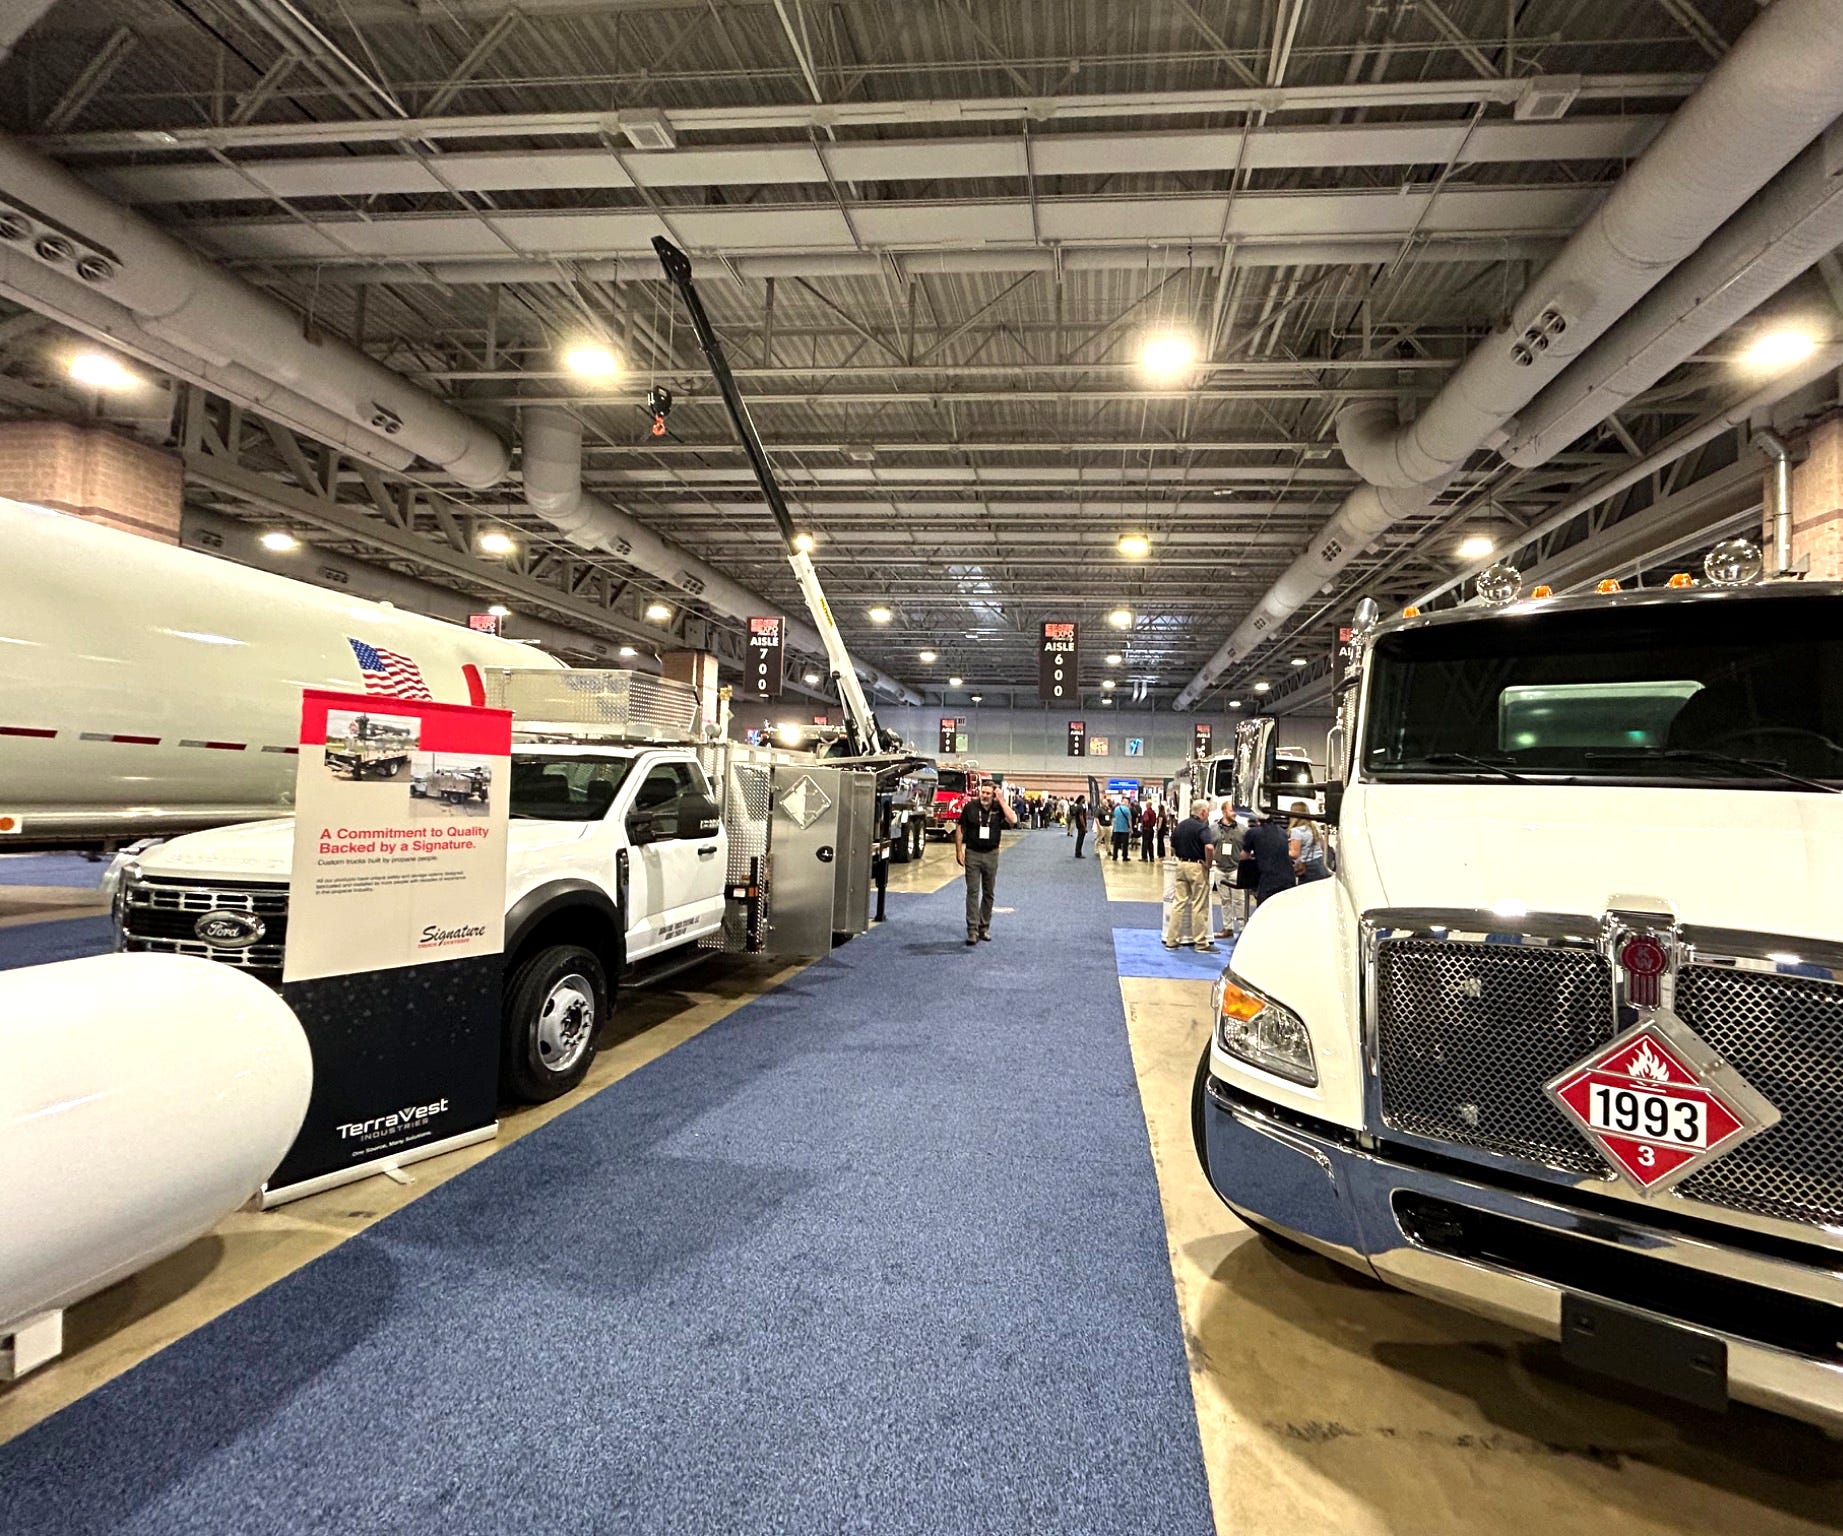
Seaport Entertainment sold 250 Water St for $142 million and leased the loss-making Tin Building, while TerraVest’s Q1 cash EBIT margin…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.