The Final Phase of This Bull Market Will Be Massive | Charles Lemonides
Charles Lemonides argues the 18-year bull market has not reached its late-stage liftoff, pairing value-oriented semiconductor longs with shorts in overvalued names.
Charles Lemonides argues the 18-year bull market has not reached its late-stage liftoff, pairing value-oriented semiconductor longs with shorts in overvalued names.
Meanwhile disintermediation by OEMs going direct is accelerating. See recent commentary from partners $CSCO, $PANW $DELL, etc. $PLUS has zero discernable benefit from $NVDA and AI.
Answer: aggressive revenue booking, financing sales, selling products at/ below cost to boost revenue and hoping to “then try to build it back up over time” per CEO. Contrast $PLUS performance w competitor and industry leader $CDW.
$PLUS Numbers don’t add up. 50% sales $CSCO product (sales -13% MRQ, guided -11%). MRQ $PLUS sales +13% (reported yesterday). Earnings call question: “OEM Cisco have talked about bottlenecks, weak orders. You’ve been unscathed…how are you outperforming the market significantly?”
$EXLS Highly innovative founder-CEO rapidly taking share w AI-based services. High-teens topline growth w expanding margins, higher value-add mix to attractive end-markets. 17x P/E yet to reflect business transformation. 100% FCF to buybacks. Winning customers from $ACN $DXC $WIT
8/ There is a lot more to talk about (24% sequential increase in new home sales, ward village condo sales etc.) but I am hungry. So to wrap up, if you're selling $HHH on this quarterly report you do not understand what you own and I will be buying your shares at tomorrow's open.
1/ So first things first, $HHH missed on top and bottom line. Am I concerned? Absolutely not. Value was created for shareholders and I'll briefly explain why...
$OII Niche leader in subsea robotics at 12x P/E. Offshore rig count accelerating (70% share), A&D growing DD, new autonomous tech a major growth driver in other end markets (lifts, etc). Investor day next week will showcase products and new LT targets. >50% NTM upside, IMO.
@TheMuffinMan28 SRS is a PE rollout, bit of a hodgepodge of assets. Concentration in landscaping, pool and roofing. No exclusive relationships (GMS is for $AWI, regional duopoly across most categories). End customers are small homebuilders (more competitive, less scale benefit for distributors).
Cognex expects 15% revenue growth this year as its RealSense acquisition expands machine-vision exposure to robotic perception, logistics,…
 Fountainhead 2 clicks
Global-e provides cross-border merchant-of-record, payments, tax and fulfillment services to more than 1,500 brands, including Shopify…
Penguin Solutions grew FY2026 revenue 26% as AI data-center and memory demand expanded, while negative free cash flow and cyclical memory…
 Investor Overview 5 clicks
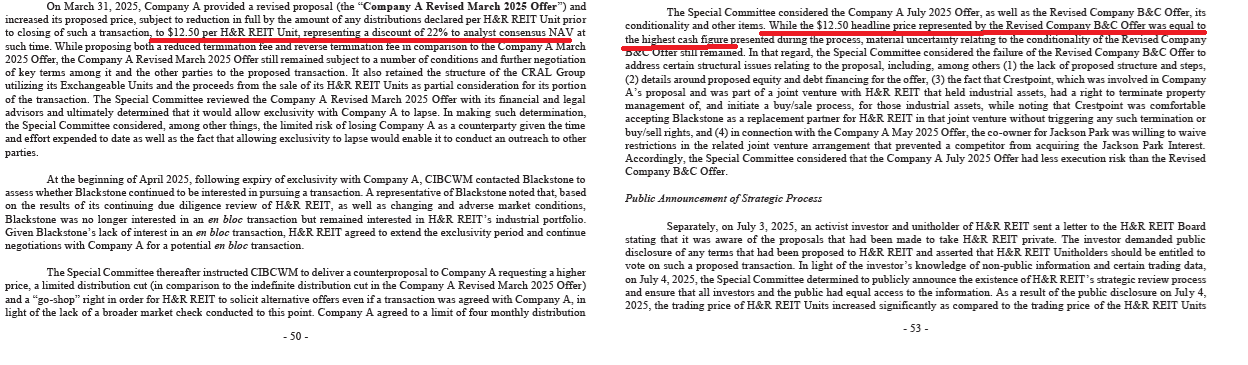
H&R REIT's proposed GO Residential transaction faces investor opposition over rejected $12.50 cash bids, insider benefits and tax…
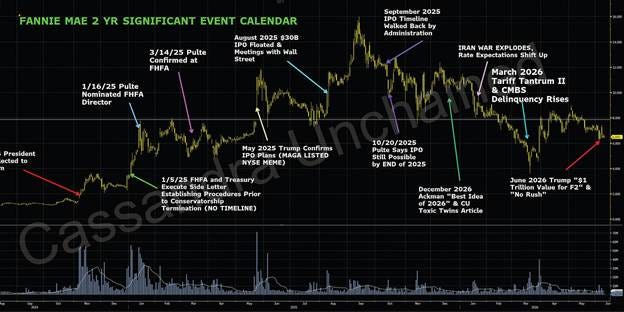
Fannie Mae and Freddie Mac common shareholders face at least 90% dilution if Treasury converts its growing senior preferred stakes into…
Inter & Co, Brazil’s second-largest neobank, grew over 20% with controlled delinquencies and 15% book-value compounding while trading at…
Hippo’s insurance platform posted 61% premium growth, a 95.8% combined ratio and a fifth profitable quarter as it shifted toward carrier…
Brazil Potash has secured court support and a power agreement, but financing, dilution and potash-price-sensitive EBITDA remain central…
 Wolf Report 4 clicks
Brazil’s October 25 runoff puts Bolsonaro’s likely victory at the center of a bullish regional-stock case; Golar LNG (GLNG) also reports…
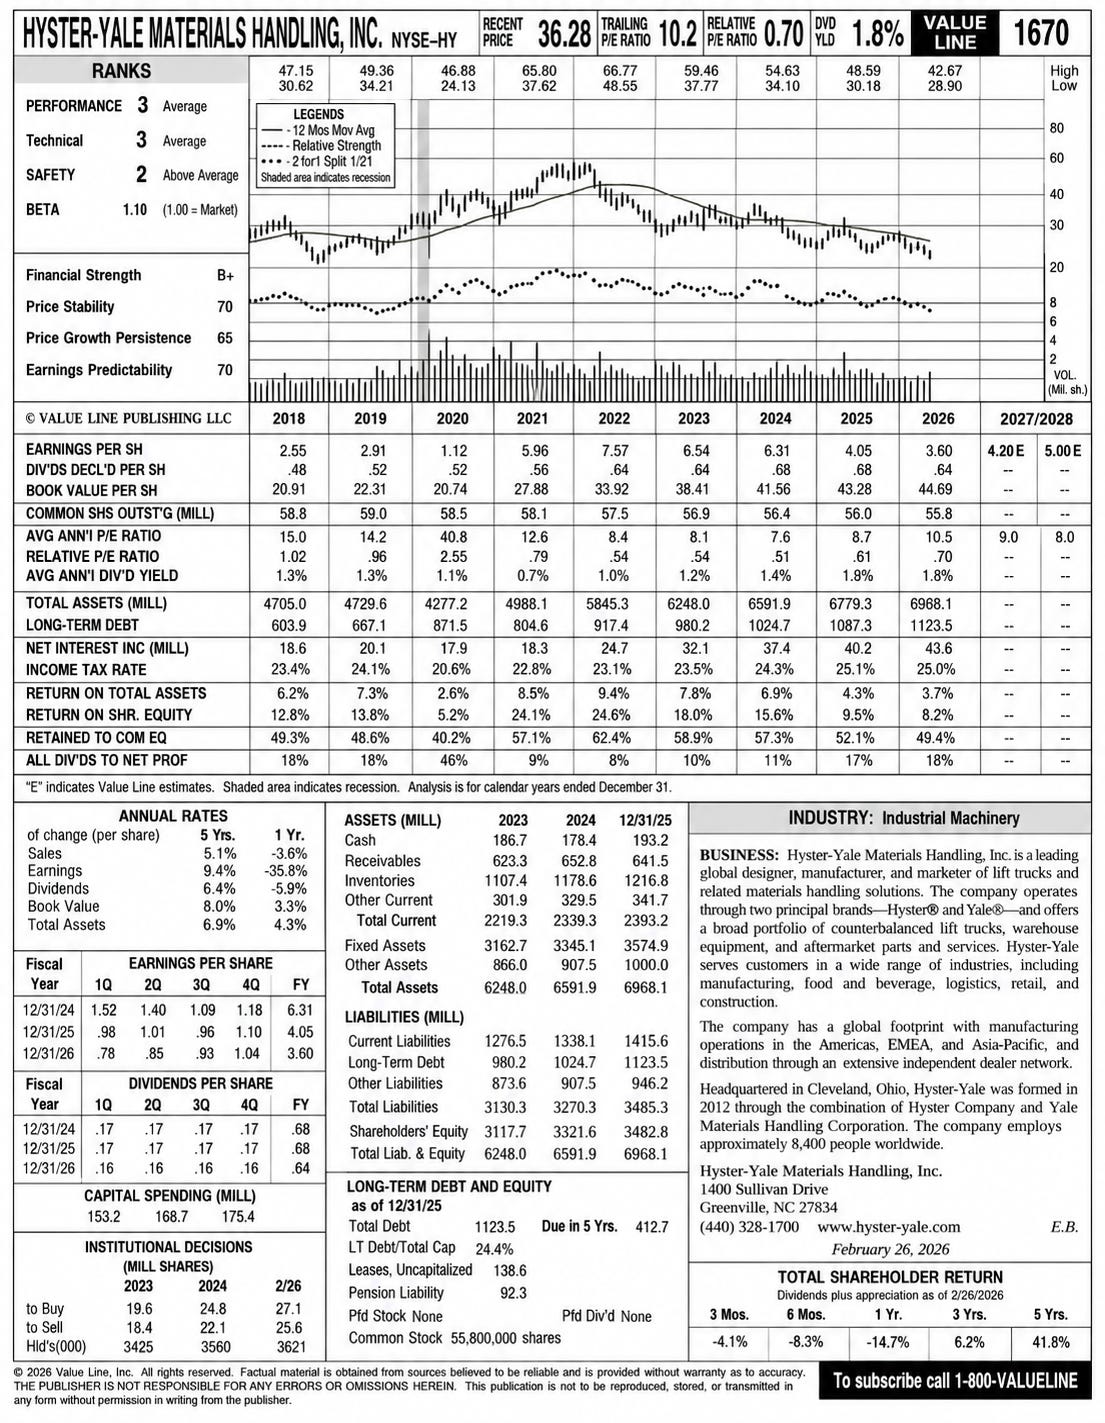
Hyster-Yale trades at 0.16 times sales as lift-truck bookings rebound and restructuring targets $85 million to $100 million in annual…
 ABSSF · long
AirBoss is a large North American rubber producer moving away from its existing business mix.
DHT Holdings earns more than $1 million daily from VLCC tankers, with Q3 EPS near $1.25 and a 20% annualized yield as spot rates outpace…
 Melissa Tucker 5 clicks
Legence trades at 10.4x EV/aEBITDA with a $5.7 billion backlog, as AI data center installations drive growth and expand its maintenance…
OceanaGold trades below its mine value despite US$655 million of cash and no debt, with production set to dip before Wharekirauponga begins…
 The Bullionaire 1 click
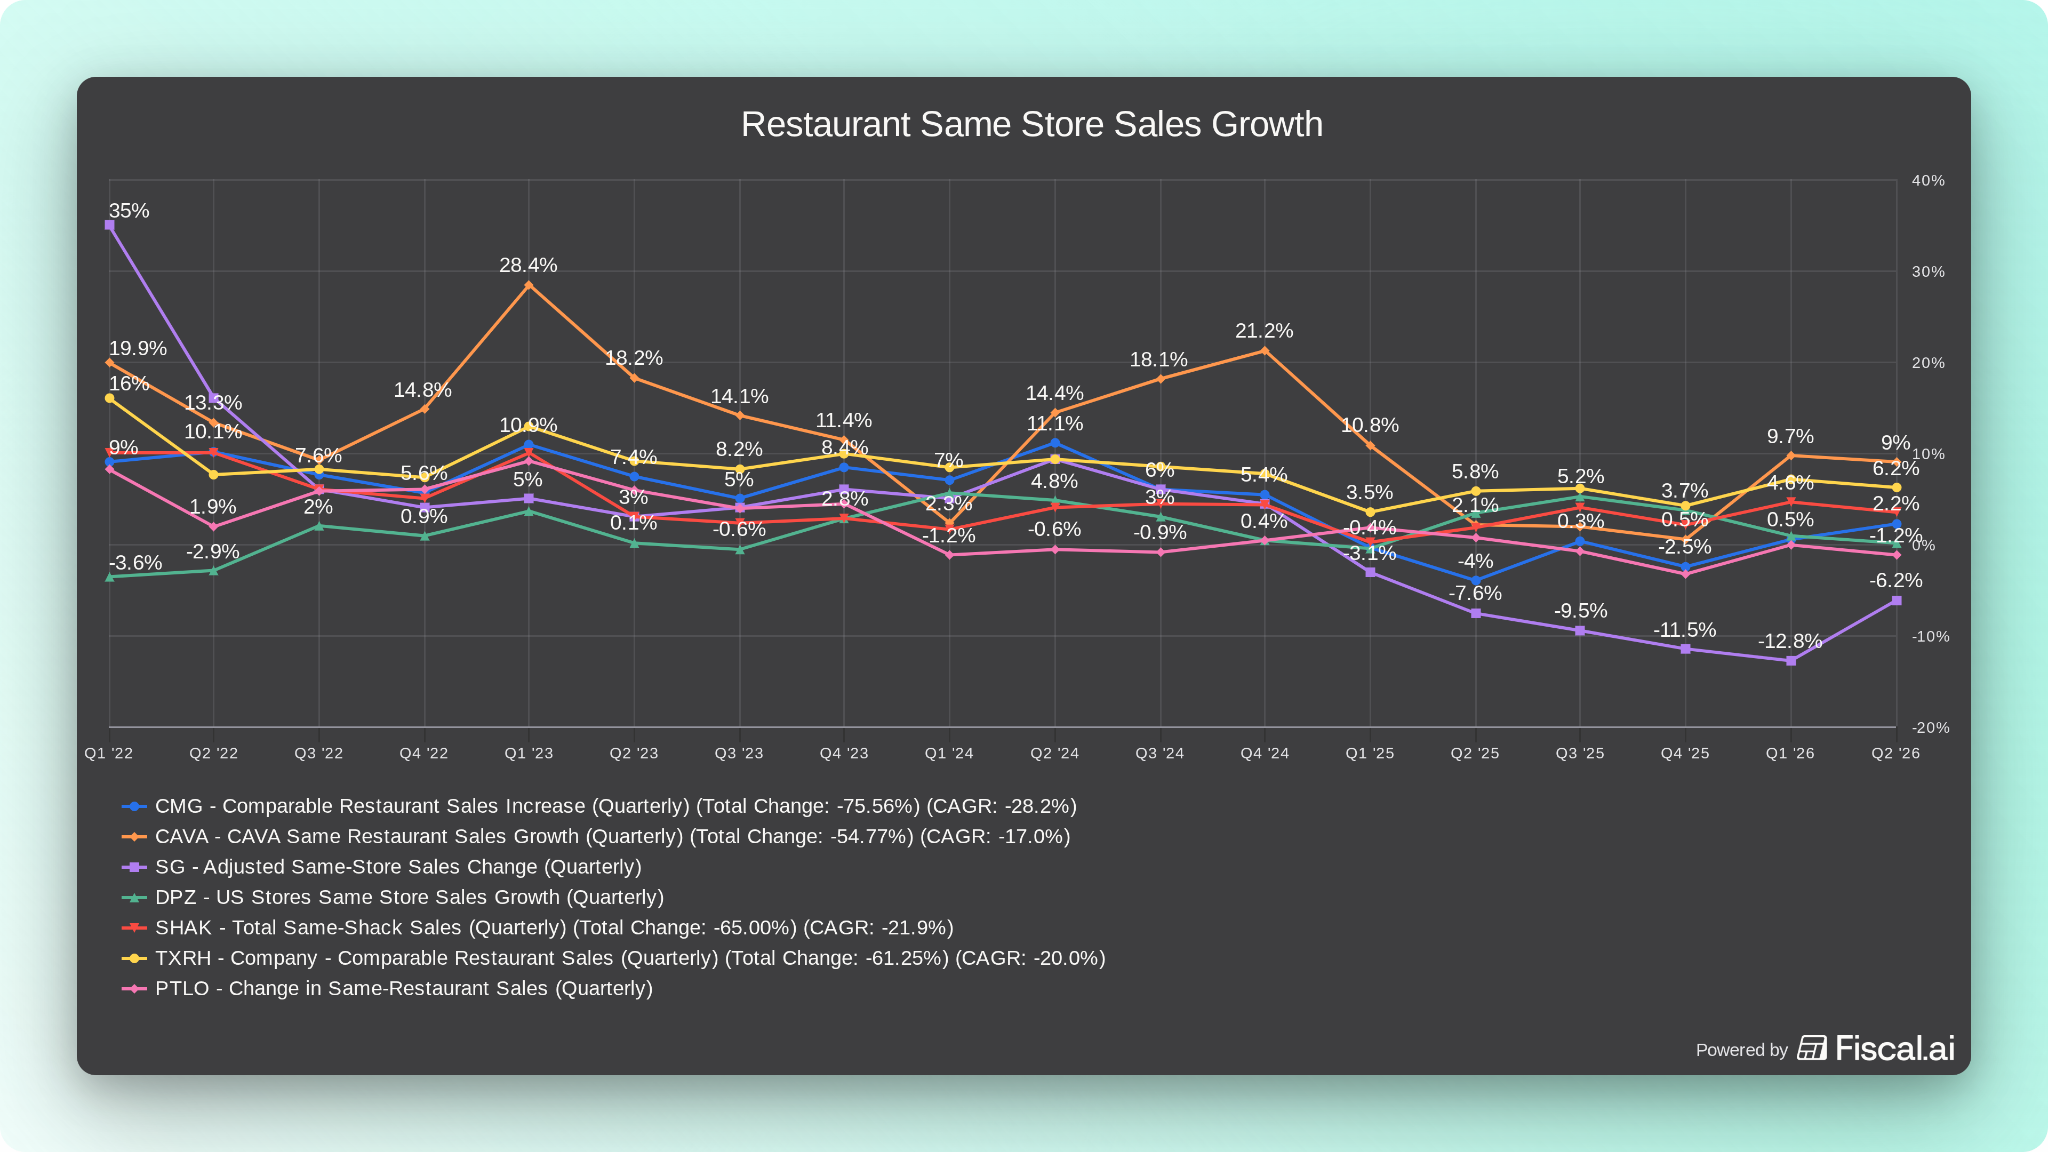
Cava’s $3 million AUVs, 25.1% restaurant margins and sector-leading same-store sales support its expansion case as awareness rose from 40%…
Namib Minerals posted H1 adjusted EBITDA of $19.0 million, up 76%, as higher gold prices offset lower production.
Special-situations survey profiles 26 activist, capital-return, M&A and strategic-alternative catalysts, led by buybacks at Under Armour,…
Millrose told Goldman its Lennar purchases had rent-to-own tenants lined up, but most analyzed homes were advertised for rent and showed…
Golar LNG ordered a $2.45 billion fourth FLNG vessel, targeting 3.5MTPA of capacity and $400 million in annual EBITDA under a 20-year…
Lesaka CEO Ali Mazanderani has bought more than $10 million of stock while pursuing a $20 to $30 valuation case through targeted…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.