Hippo Holdings ($HIPO): The Insurtech That Stopped Chasing Hype and Started Making Money
Hippo’s insurance platform posted 61% premium growth, a 95.8% combined ratio and a fifth profitable quarter as it shifted toward carrier and MGA fee income.
Hippo’s insurance platform posted 61% premium growth, a 95.8% combined ratio and a fifth profitable quarter as it shifted toward carrier and MGA fee income.
@shallowdives1 @peter_mantas Yeah it’s a nice little industry bubble forming. $DNA is also a Shitco
$DNA - Looks like another genetics short too.
Huron Valley Bank to merge into Bank of Ann Arbor. A few $OXBC holders may be pleased to see it transact for 180% of book value. https://t.co/8buSKj0oh2
Namib Minerals posted H1 adjusted EBITDA of $19.0 million, up 76%, as higher gold prices offset lower production.
Cogent Communications and AI data-center bottlenecks feature in a newsletter update on recruiting, financial media and conference takeaways.
Lesaka’s executive chairman has invested more than $10 million personally and targets EPS compounding above 40% through consumer, merchant…
VersaBank's Q3 revenue rose 23% and adjusted net income 27%, while a 2.19% net interest margin and 19.15x forward earnings temper its 2027…
 Grassroots Trading 1 click
Latticework’s briefing questions AI capex returns while featuring Close Brothers, Green Landscaping and OMS Energy Technologies.
Old Market Capital, a delisted holding company owning a rural fiber network, trades below comparable network valuations after institutional…

Leslie’s and nine affiliates filed Chapter 11 in Texas on September 30, 2026, after 18 months of deteriorating performance.
Leslie’s, the pool-supplies retailer, filed Chapter 11 after deteriorating operations, pricing and inventory missteps, and a burdensome…
Pyxis Oncology's recent financing extends MICVO's runway to clinical milestones as the oncology candidate works to establish a safe,…
 Myriam Alvarez 2 clicks
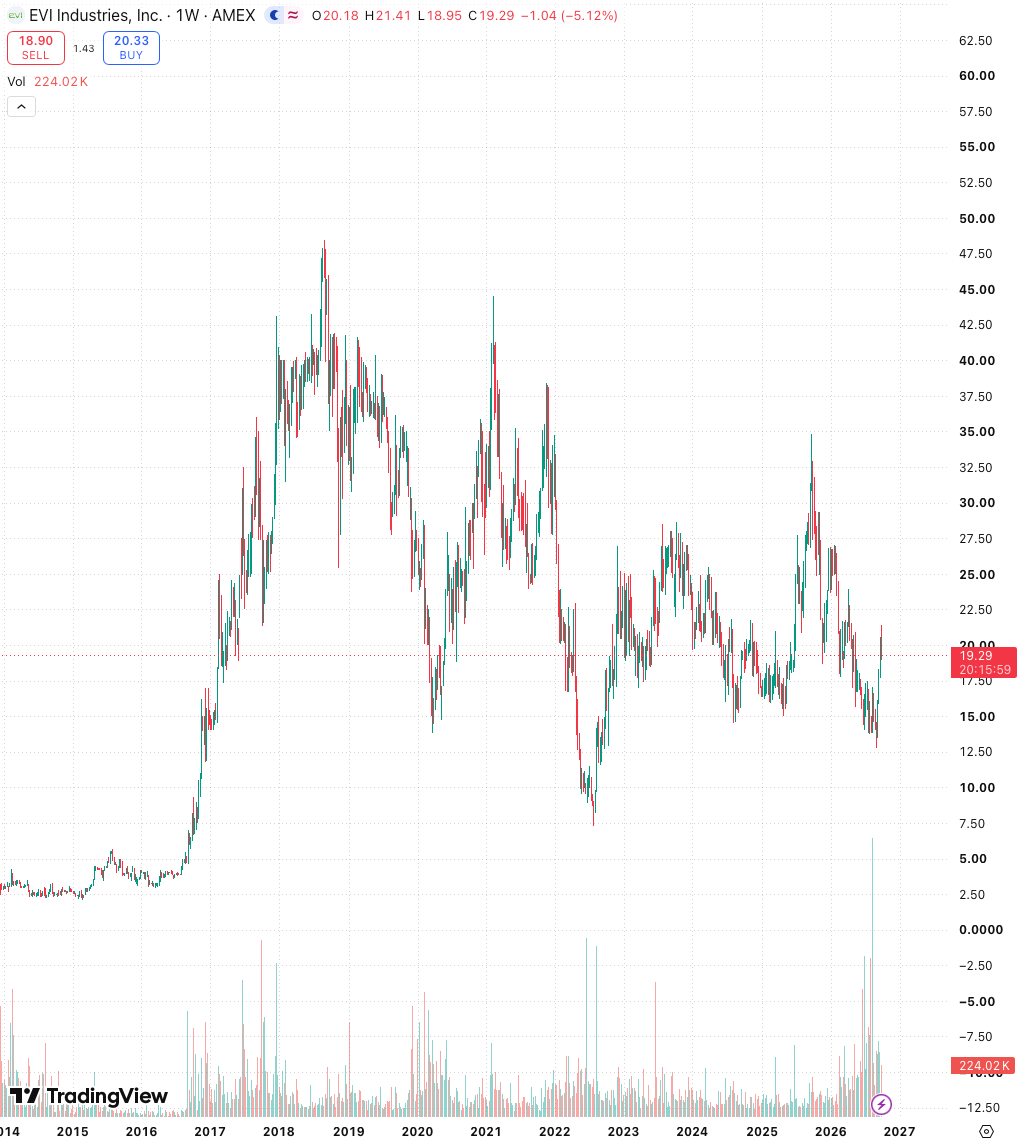
EVI Industries says its ERP and service-platform build is largely complete, testing whether 10.8% revenue growth can finally outpace…
 ABSSF · long
AirBoss is a large North American rubber producer moving away from its existing business mix.
Brazil Potash has secured court support and a power agreement, but financing, dilution and potash-price-sensitive EBITDA remain central…
 Wolf Report 3 clicks
Huckleberry.AI trades near $3.30 against $221 million of cash and $900 million-plus of NOLs after selling its operating business, creating…
Entravision, the portfolio’s largest position, fell more than 40% from its highs as Q3 returns dropped to 37.8% YTD.
Zentek shipped its first ZenGUARD air-filter order to a Canadian federal facility as its Albany graphite PEA confirmed a US$3.85 billion…
Yuanbao pairs a 10.2% dividend and cash exceeding its market value with 33.5% first-half profit growth from AI-enabled Chinese insurance…
Stratus Properties liquidates Austin real estate below projected distributions, while Atlantic Lithium and Intermex await approvals for…
Beyond Meat’s Q2 2026 revenue fell 8.2% as U.S. retail and foodservice volumes declined, while a flatter, not inverted, Treasury curve…
Cullinan Therapeutics plans December 2026 autoimmune updates for CLN-978, while zipalertinib awaits an FDA decision in previously treated…
Myriam Alvarez 2 clicks
VersaBank uses cash holdbacks and put-backs to buy point-of-sale loan cash flows, with C$7 billion in assets and AI-enabled real-time…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.