Boyz in the Hood
Robinhood’s AI agents, 24/7 equity trading and 10:1 crypto perpetual futures encourage higher retail trading velocity, leverage and momentum.
Robinhood’s AI agents, 24/7 equity trading and 10:1 crypto perpetual futures encourage higher retail trading velocity, leverage and momentum.
@whatsgoingoninm $HHH is a little different. The fee structure is weird and they have a weirder collection of assets, not just a bunch of publically listed stocks anyone can buy. Though no capital returns. Still not a great structure but not as egregious as PSH.
$FEIM (defense) was a great example of this. Not only was backlog growing, it was replacing sub 30% gross margin backlog with over 40% GM. You had all day to buy the stock between $8 & $15 in 2024. Now it’s pushing $100. $SIF (defense) might be approaching that type of set-up. https://t.co/wZh0Jqi3dz
@realroseceline Kind of crazy that $APP was at a quarter trillion market cap
@mkfilko How you be walking with $NKE shoes https://t.co/jITmdz7fgR
@CompoundingEV There is no semi comprehensive tweet on $PAHC, there is no where for people to see a snapshot of it in such a pleasing manner unless they have value line. To me at least it’s nicer reading a quick pitch complied by a human than asking AI
Millrose told Goldman its Lennar purchases had rent-to-own tenants lined up, but most analyzed homes were advertised for rent and showed…
Nike's 4.8% dividend yield masks payout ratios above 100% of forward EPS and inadequate free cash flow coverage, while China sales declines…
 Sensor Unlimited
Golar LNG ordered a $2.45 billion fourth FLNG vessel, targeting 3.5MTPA of capacity and $400 million in annual EBITDA under a 20-year…
Credo expects optical revenue to reach $600 million in FY27 after Q1 revenue grew 114.7% year over year, expanding from AEC cables into AI…
 Analysis Fundamental 4 clicks
Vertiv's 33% stock decline followed a 2026 forecast increase, despite a $15 billion backlog and rising AI data-center demand for power and…
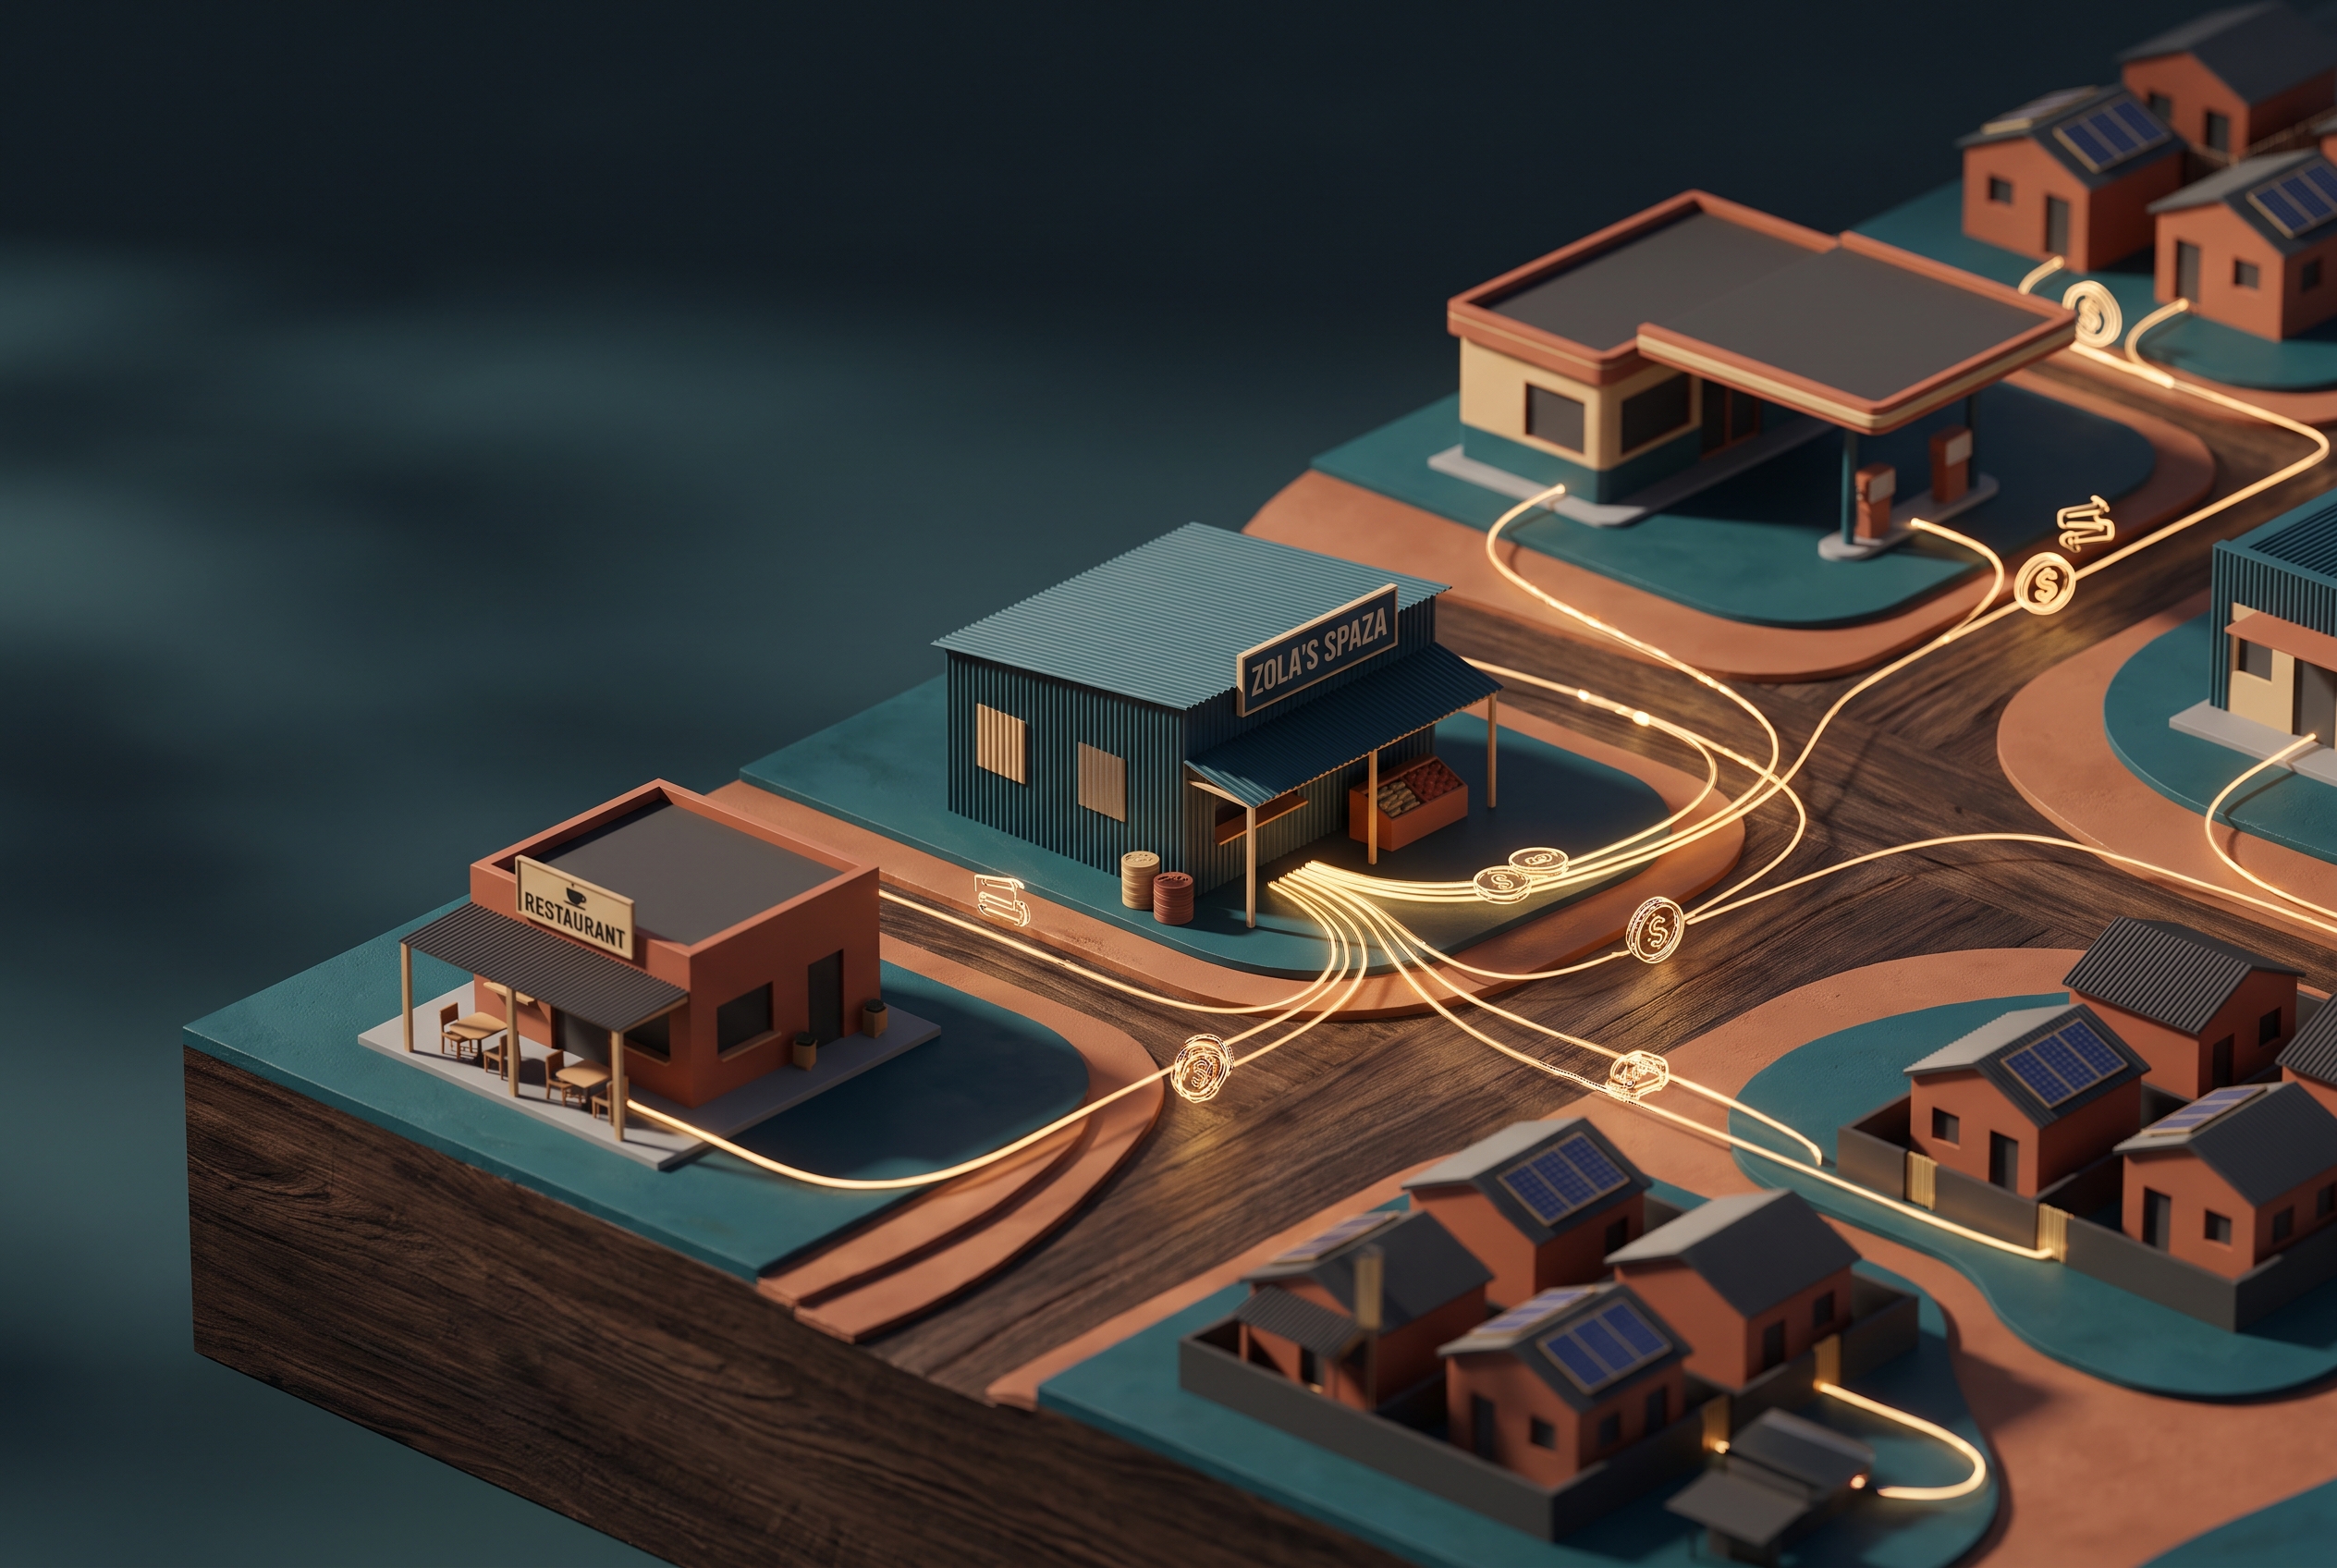
Lesaka CEO Ali Mazanderani has bought more than $10 million of stock while pursuing a $20 to $30 valuation case through targeted…
Cogent Communications and AI data-center bottlenecks feature in a newsletter update on recruiting, financial media and conference takeaways.
Undercovered Dozen spotlights 12 lesser-covered stocks, including Brookfield Renewable, Annaly Capital and Seagate.
Lesaka’s executive chairman has invested more than $10 million personally and targets EPS compounding above 40% through consumer, merchant…
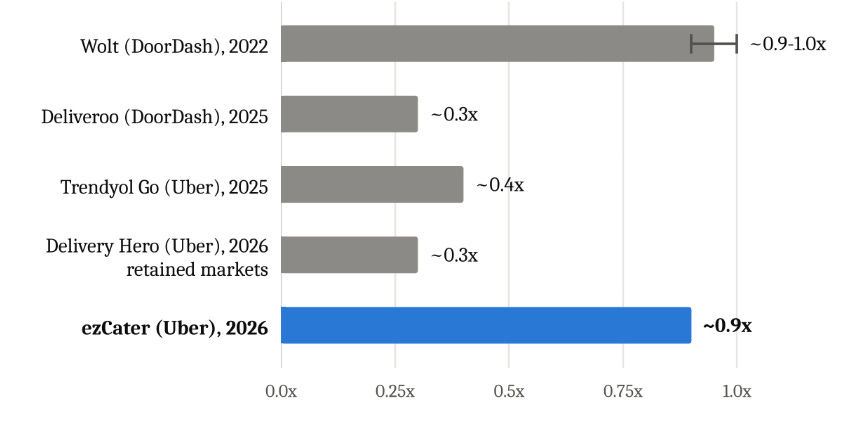
Uber’s $2.3 billion cash purchase of ezCater extends its buy-versus-build strategy and raises questions about the price and capital…
 POST · long
Post Holdings remains a large position after the stock's recent decline.
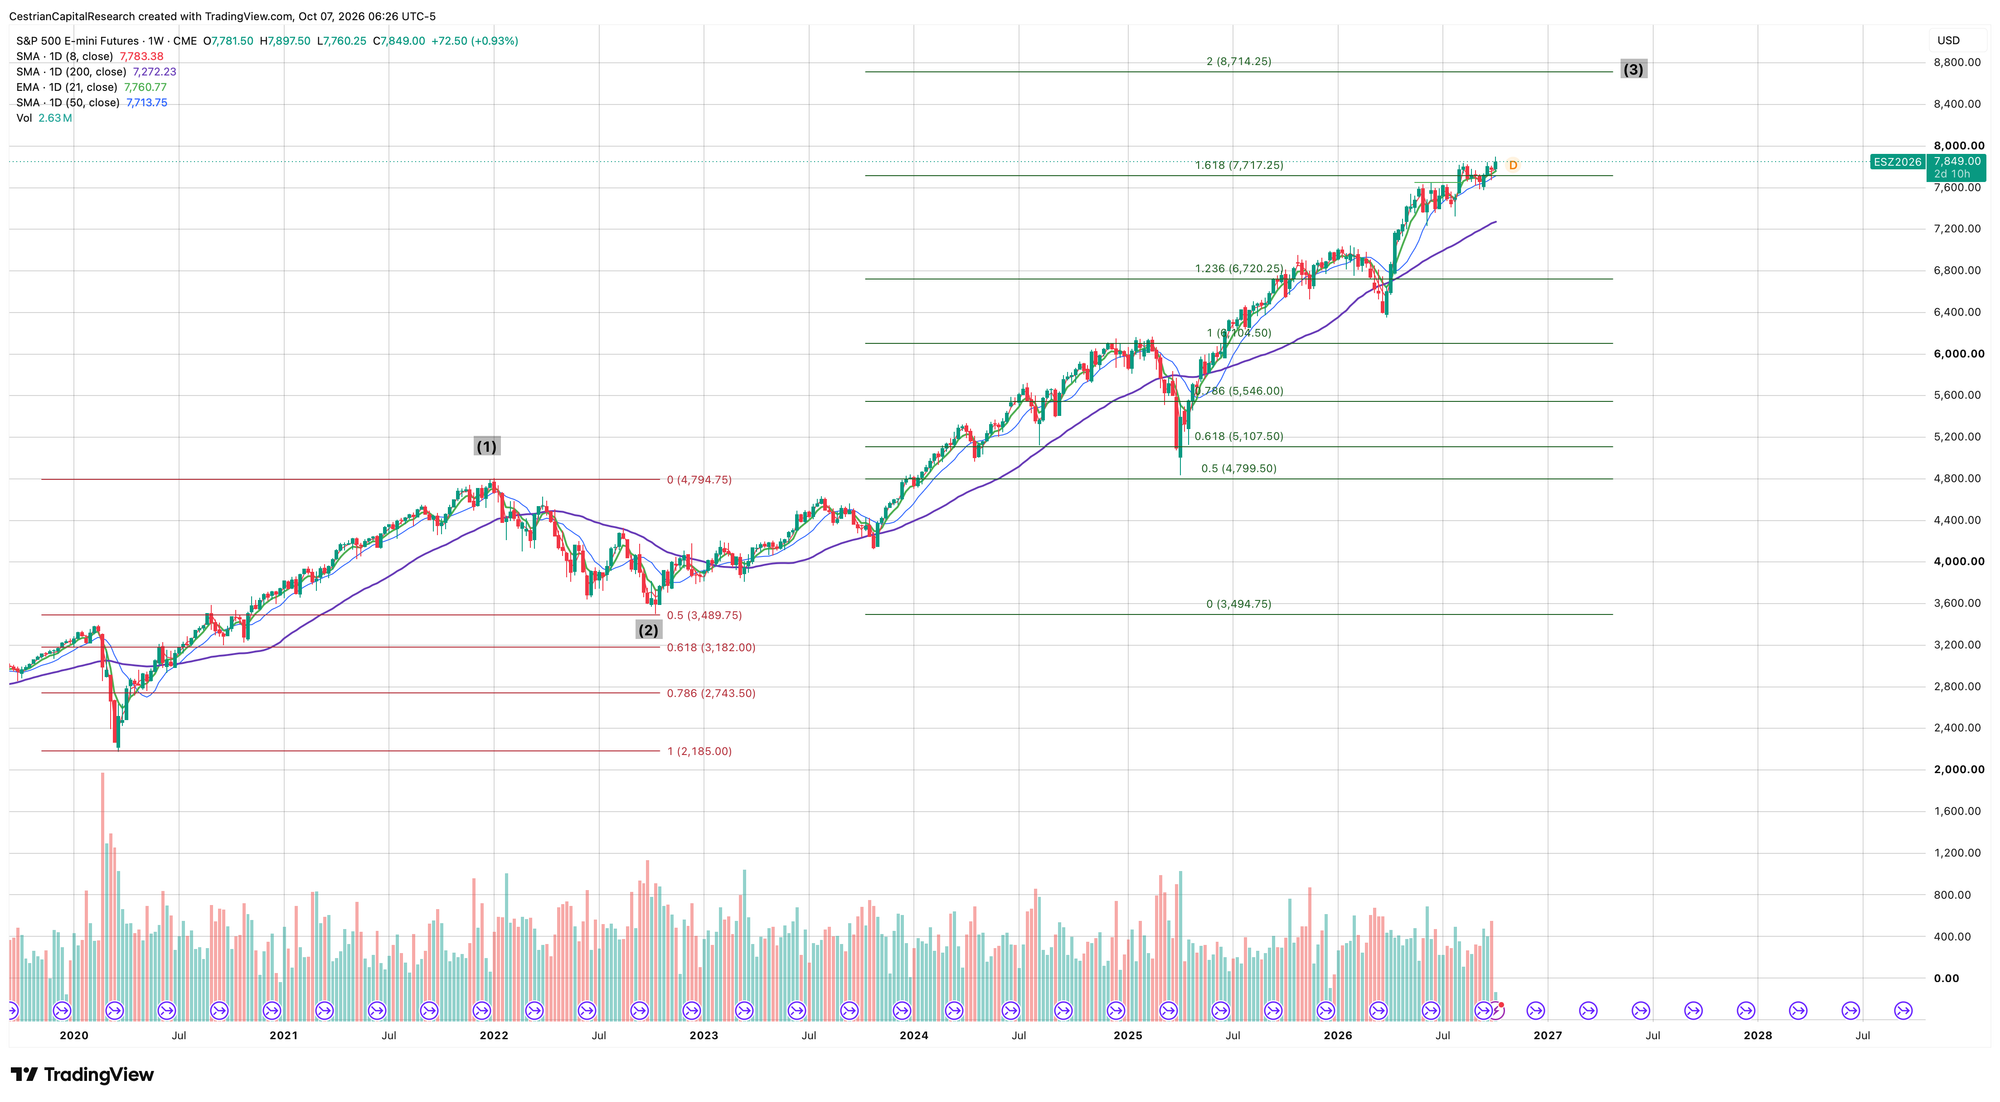
L3Harris upgraded to Accumulate after a 38% stock decline, backed by 8% Q2 revenue growth, a $42 billion backlog and planned Missile…
Cerebras retains its 750 MW commitment despite OpenAI's Nvidia move, but TSMC supply, owned capacity and gross-margin recovery remain the…
 Deep Value Investing
Salad and Go filed Chapter 11 after its Texas and Oklahoma expansion failed, seeking to sell 65 leases to Dutch Bros for $105 million as 7…
West Pharmaceutical Services’ GLP-1 demand, HVP upgrades and Annex 1 conversions support double-digit growth, but its premium valuation…
 Petri Dish Reports
OpenAI’s enterprise privacy push and Synopsys’s Factory 2 royalty model anchor a technology roundup, alongside oil above $100 and Bitcoin’s…
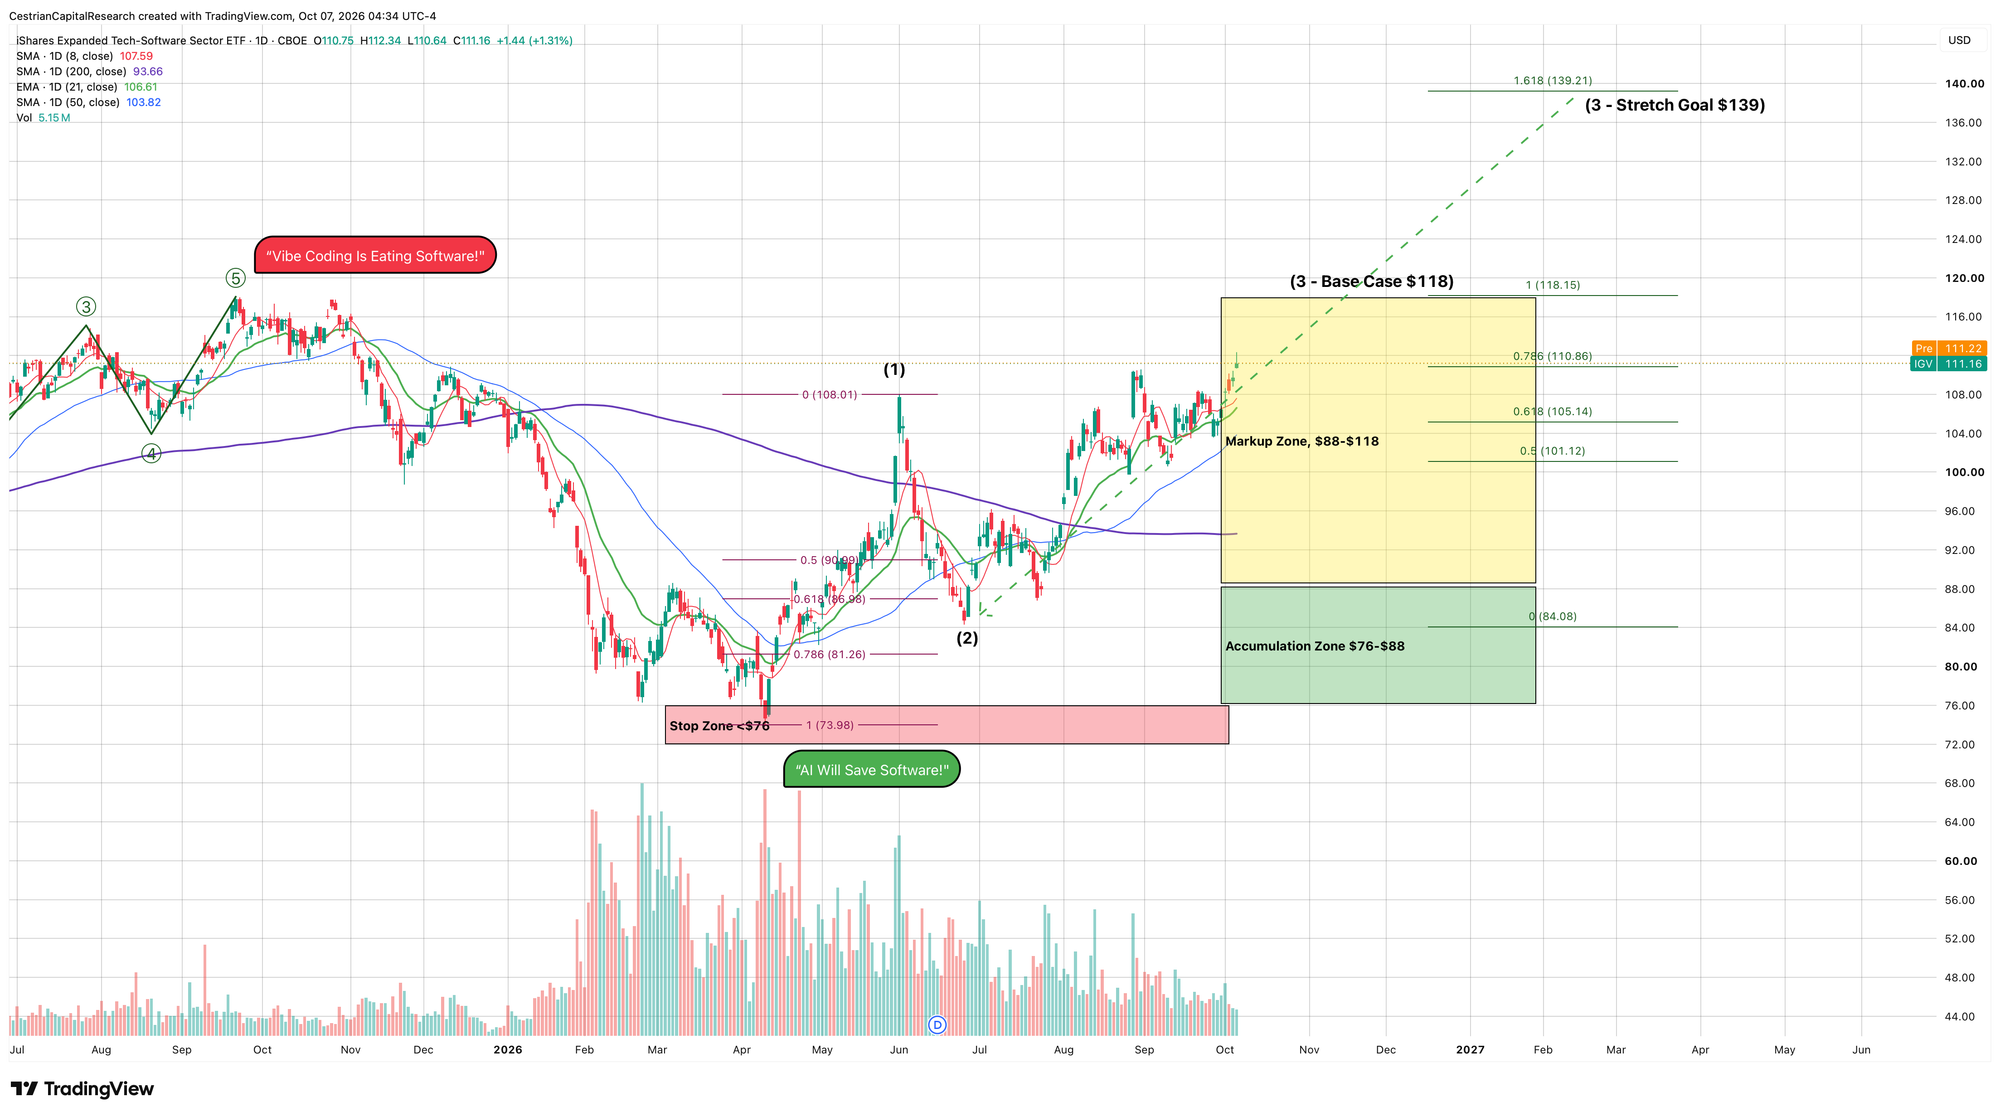
Adobe rates Accumulate at $189-$266 after Q3 FY26 revenue grew 12.9%, while management guided slower growth and RPO growth decelerated.
On Holding (ONON) is gaining sportswear share, expanding store space and launching soccer with Kylian Mbappé as investors debate U.S.
Astronics targets $1.02 to $1.04 billion in 2026 revenue after adjusted operating margin reached 20.3%, with Boeing representing 12% of…
 Jordan Aquilina
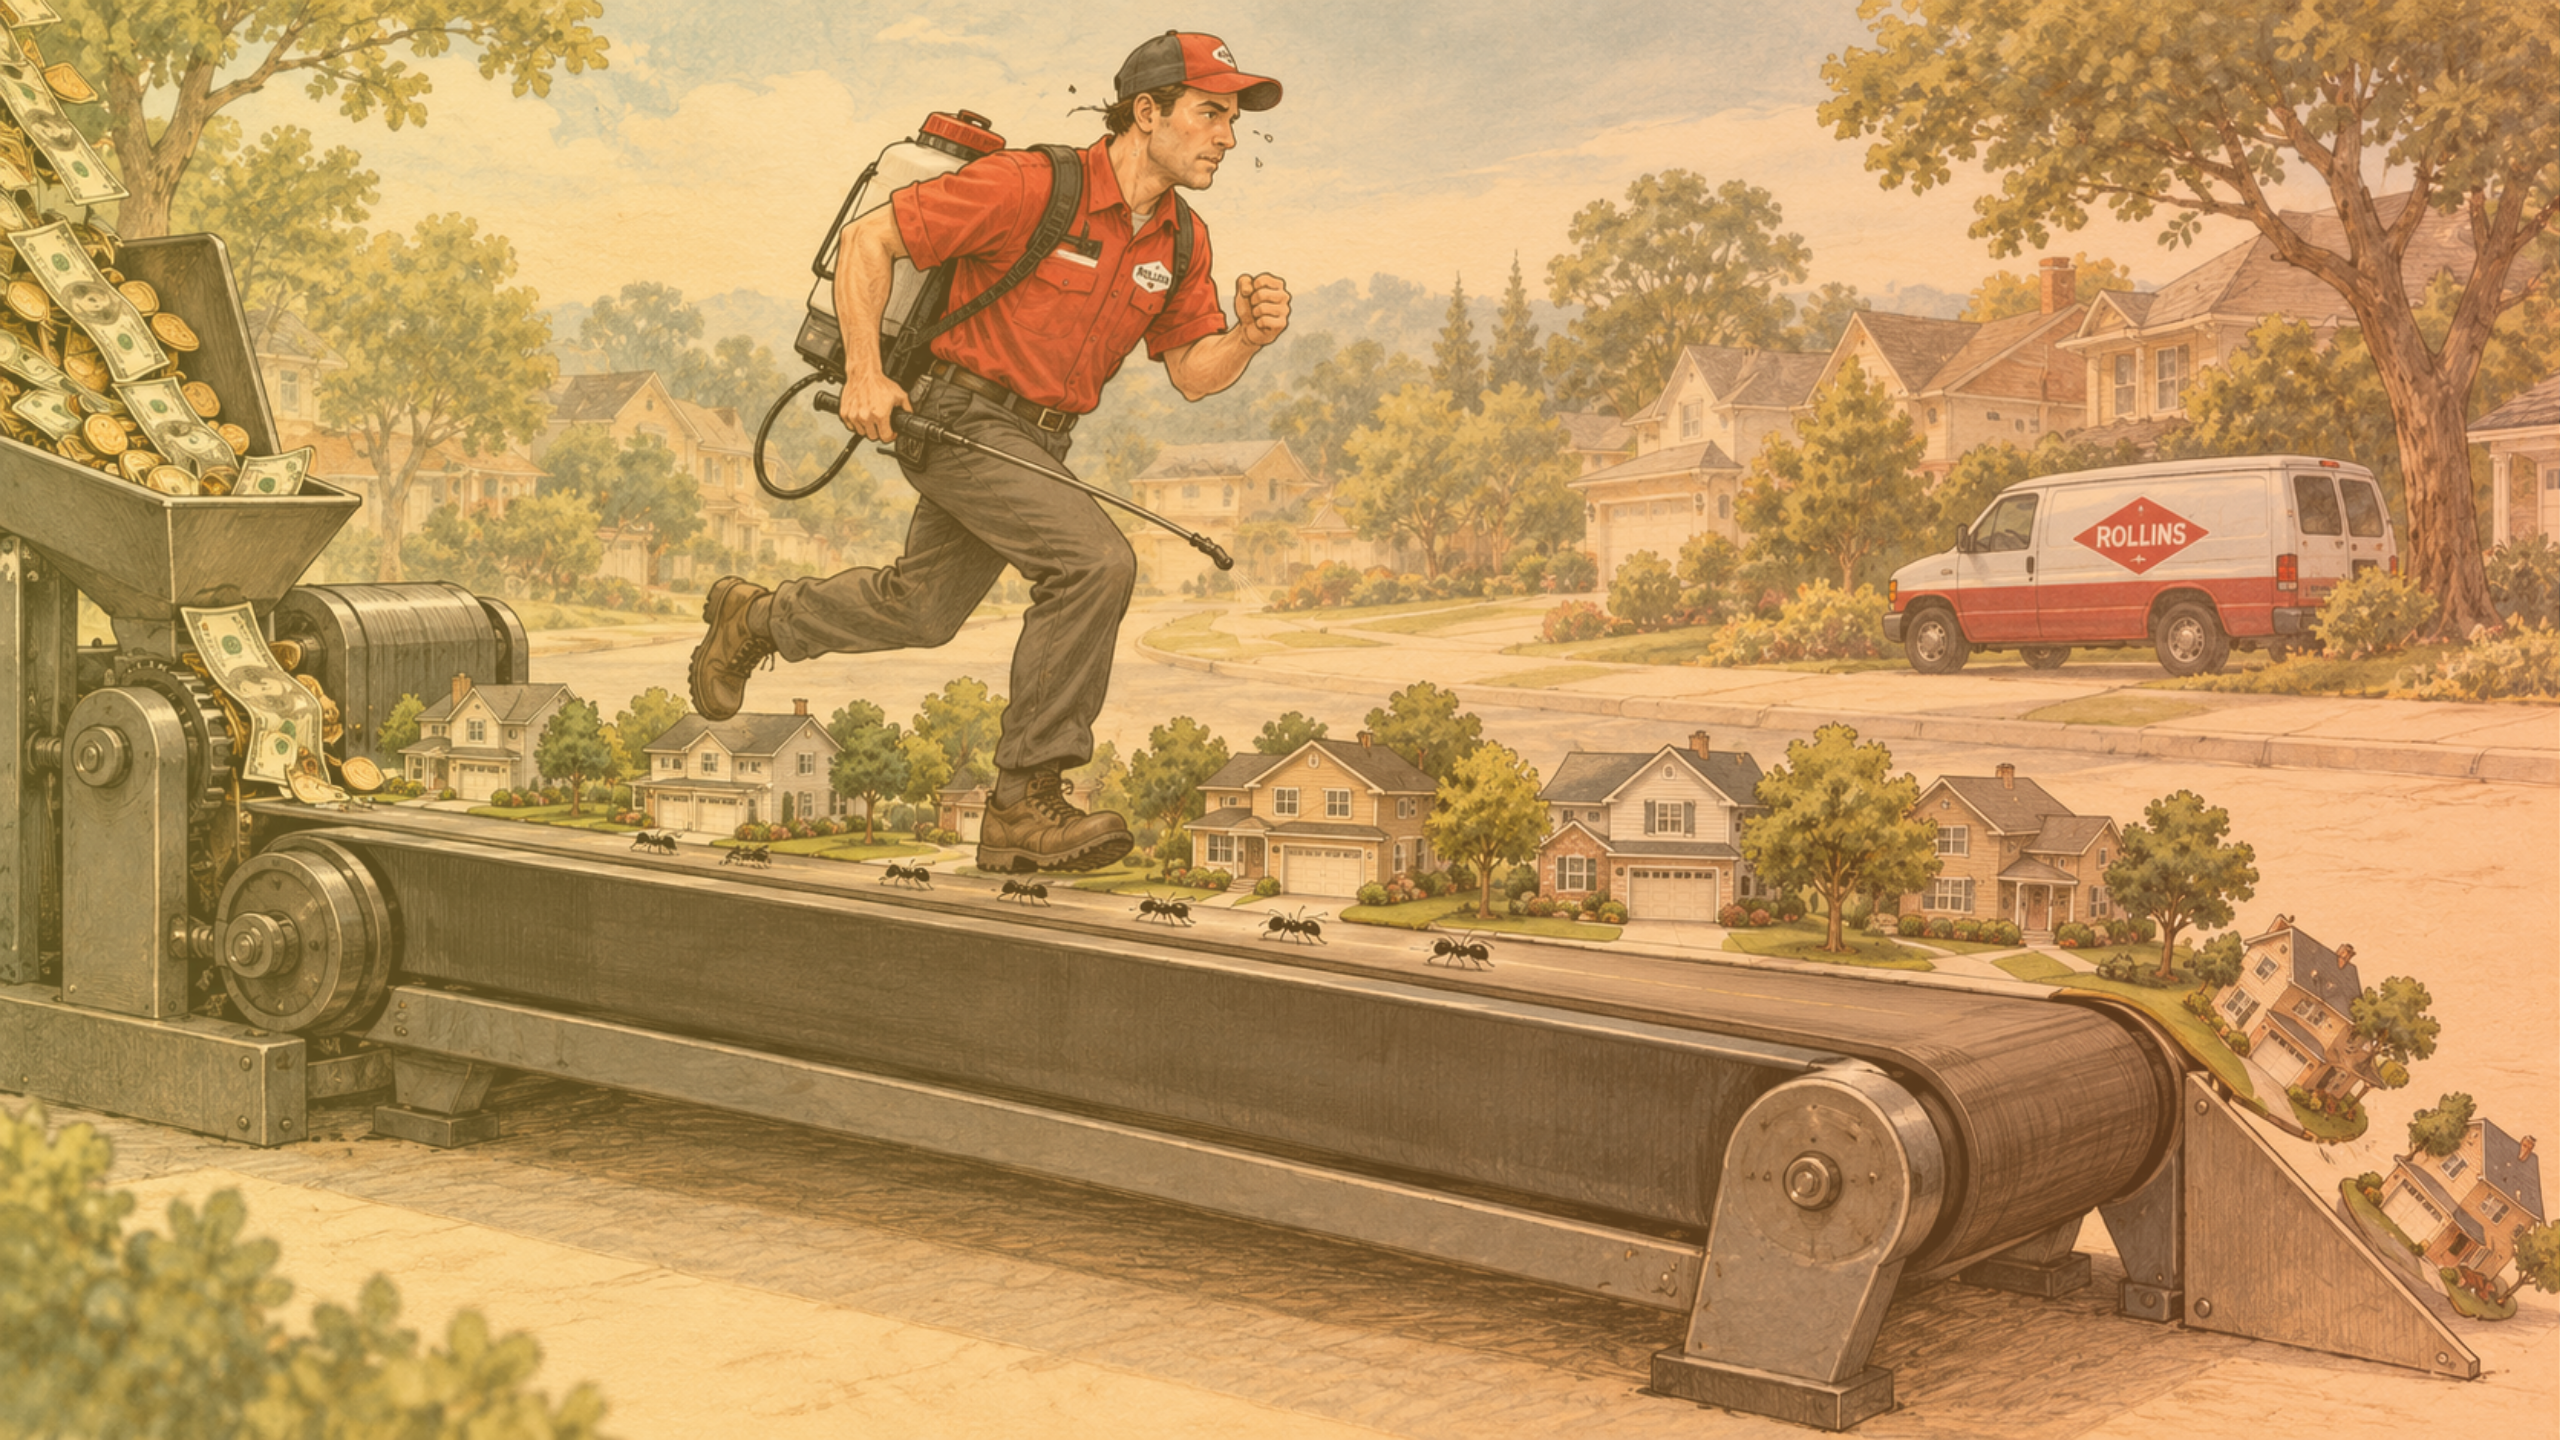
Rollins’ recurring pest-control base requires ongoing spending to replace departing customers, a concern tied to its nearly 50%…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 David Zanoni Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.