Ciena & Fabrinet: The Road Ahead for Optics
Ciena and Fabrinet benefit as AI clusters require high-speed optics within and between data centers, through networking systems and contract manufacturing respectively.
Ciena and Fabrinet benefit as AI clusters require high-speed optics within and between data centers, through networking systems and contract manufacturing respectively.
@ryanTesling @elliotrades worry isn’t something i do often. a rate hike is a known risk investors won’t like short term, but it changes nothing about my larger $AMZN thesis.
@elliotrades $AMZN
Liberty Media bought Formula 1 for $4.4 billion in 2017 and monetizes its exclusive commercial rights through racing, media and sponsorship.
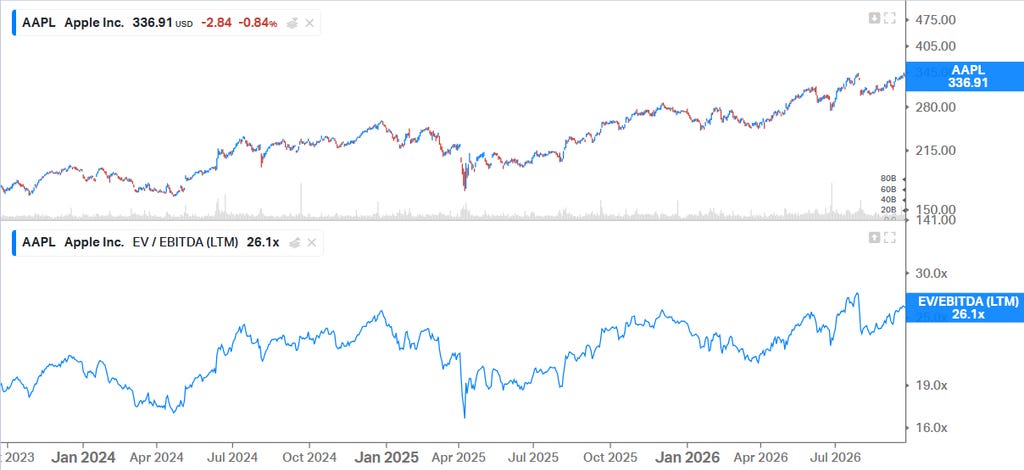
Apple has ceded frontier AI to partners like Google while planning AI-native glasses, camera-equipped AirPods and a smart-home hub over the…
AMD’s MI455X offers 432 GB of HBM4, 50% more memory than Nvidia’s Rubin, positioning it for memory-intensive enterprise AI agents.
 Simple Investment Ideas 3 clicks
Micron’s customer agreements, Analog Devices’ acquisitions, Ondas’ GATE deal and Baker Hughes’ power systems position them for AI…
Intel reported Q2 2026 revenue of $16.13 billion, up 25.4%, as AI PCs and data-center CPUs lifted margins and narrowed foundry losses.
 Danil Sereda 2 clicks
CoreWeave funds GPU data-center expansion with debt backed by $104 billion in contracted revenue, while GPU cloud rentals generate roughly…
Texas Instruments, ON Semiconductor and Vishay are rated Accumulate on rising robotics demand for analog, power and discrete chips after a…
Abbott’s Exact Sciences acquisition raises leverage, leaving Medical Devices’ 8% growth and 33.9% margin to carry cash flow until…
 PV Research 1 click
Innodata's new Meta contract for long-horizon agent personalization ties the data company to Meta's Muse AI assistant, despite Meta's Scale…
 MA · long
Mastercard trades near $495, about 18% below its $602 52-week high, framing a favorable long risk-reward case.
Reddit’s subreddit-driven communities support targeted advertising, and its 0.3 PEG ratio makes RDDT undervalued, according to the upgrade…
 Fountainhead 4 clicks
Credo Technology was added at $170.54 after a 40% selloff, backed by its high-speed AECs and optical connectivity for AI data centers.
Copart’s $1.9 billion ACV Auctions acquisition targets renewed growth, with EPS accretion expected by fiscal 2028 as insurance…
 Robert J. Lake 2 clicks
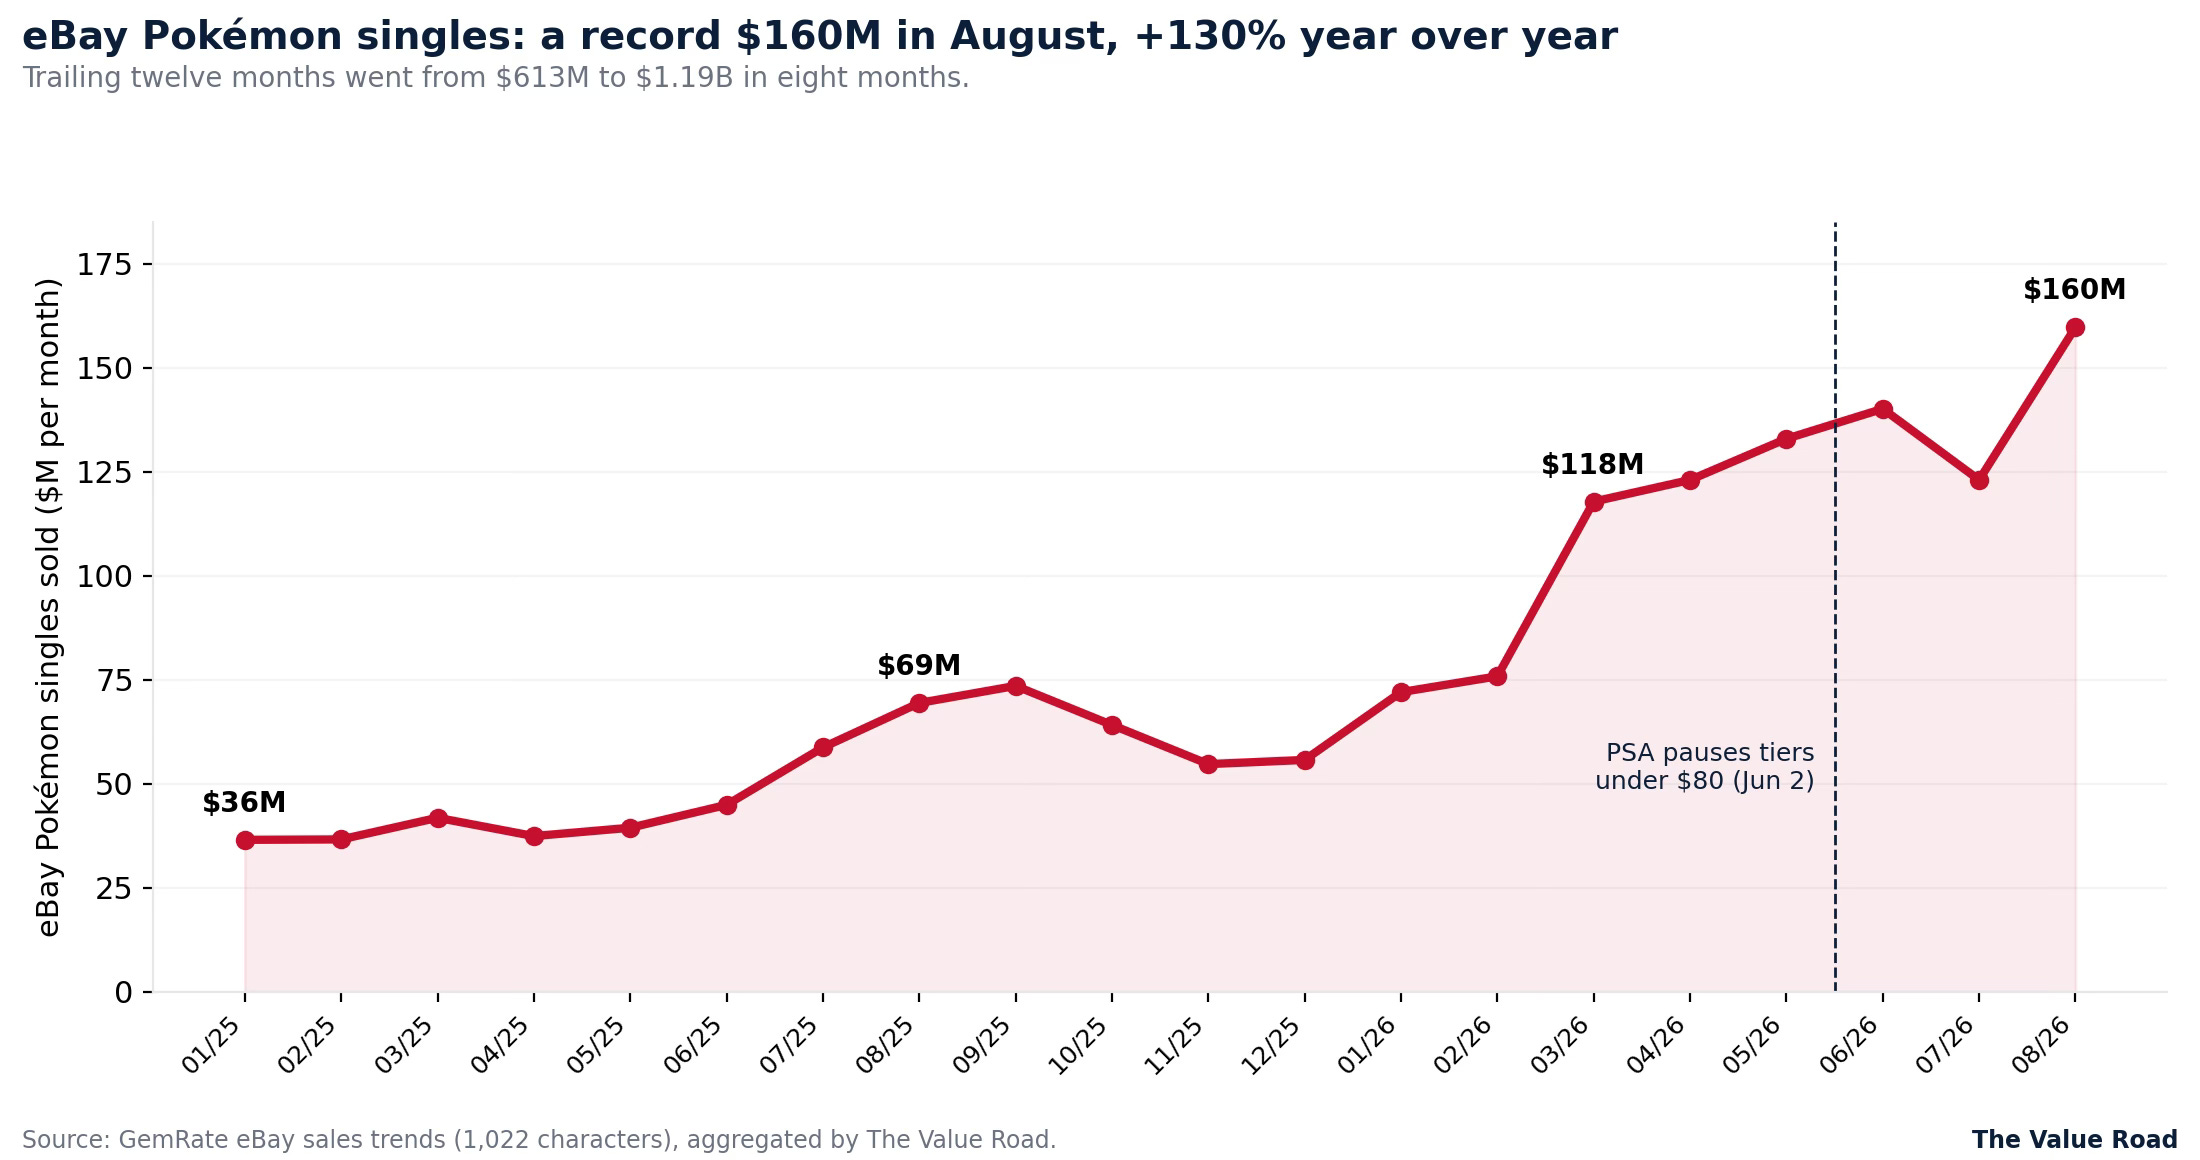
GameStop's collectibles mix rose to 45% of sales as gross margin reached 44%, supporting a deep-value case built on cash and store…
Tempus AI’s Q2 oncology testing volumes rose 31%, while data and applications revenue grew 28% as its clinical data flywheel expands.
 Bay Area Ideas 2 clicks
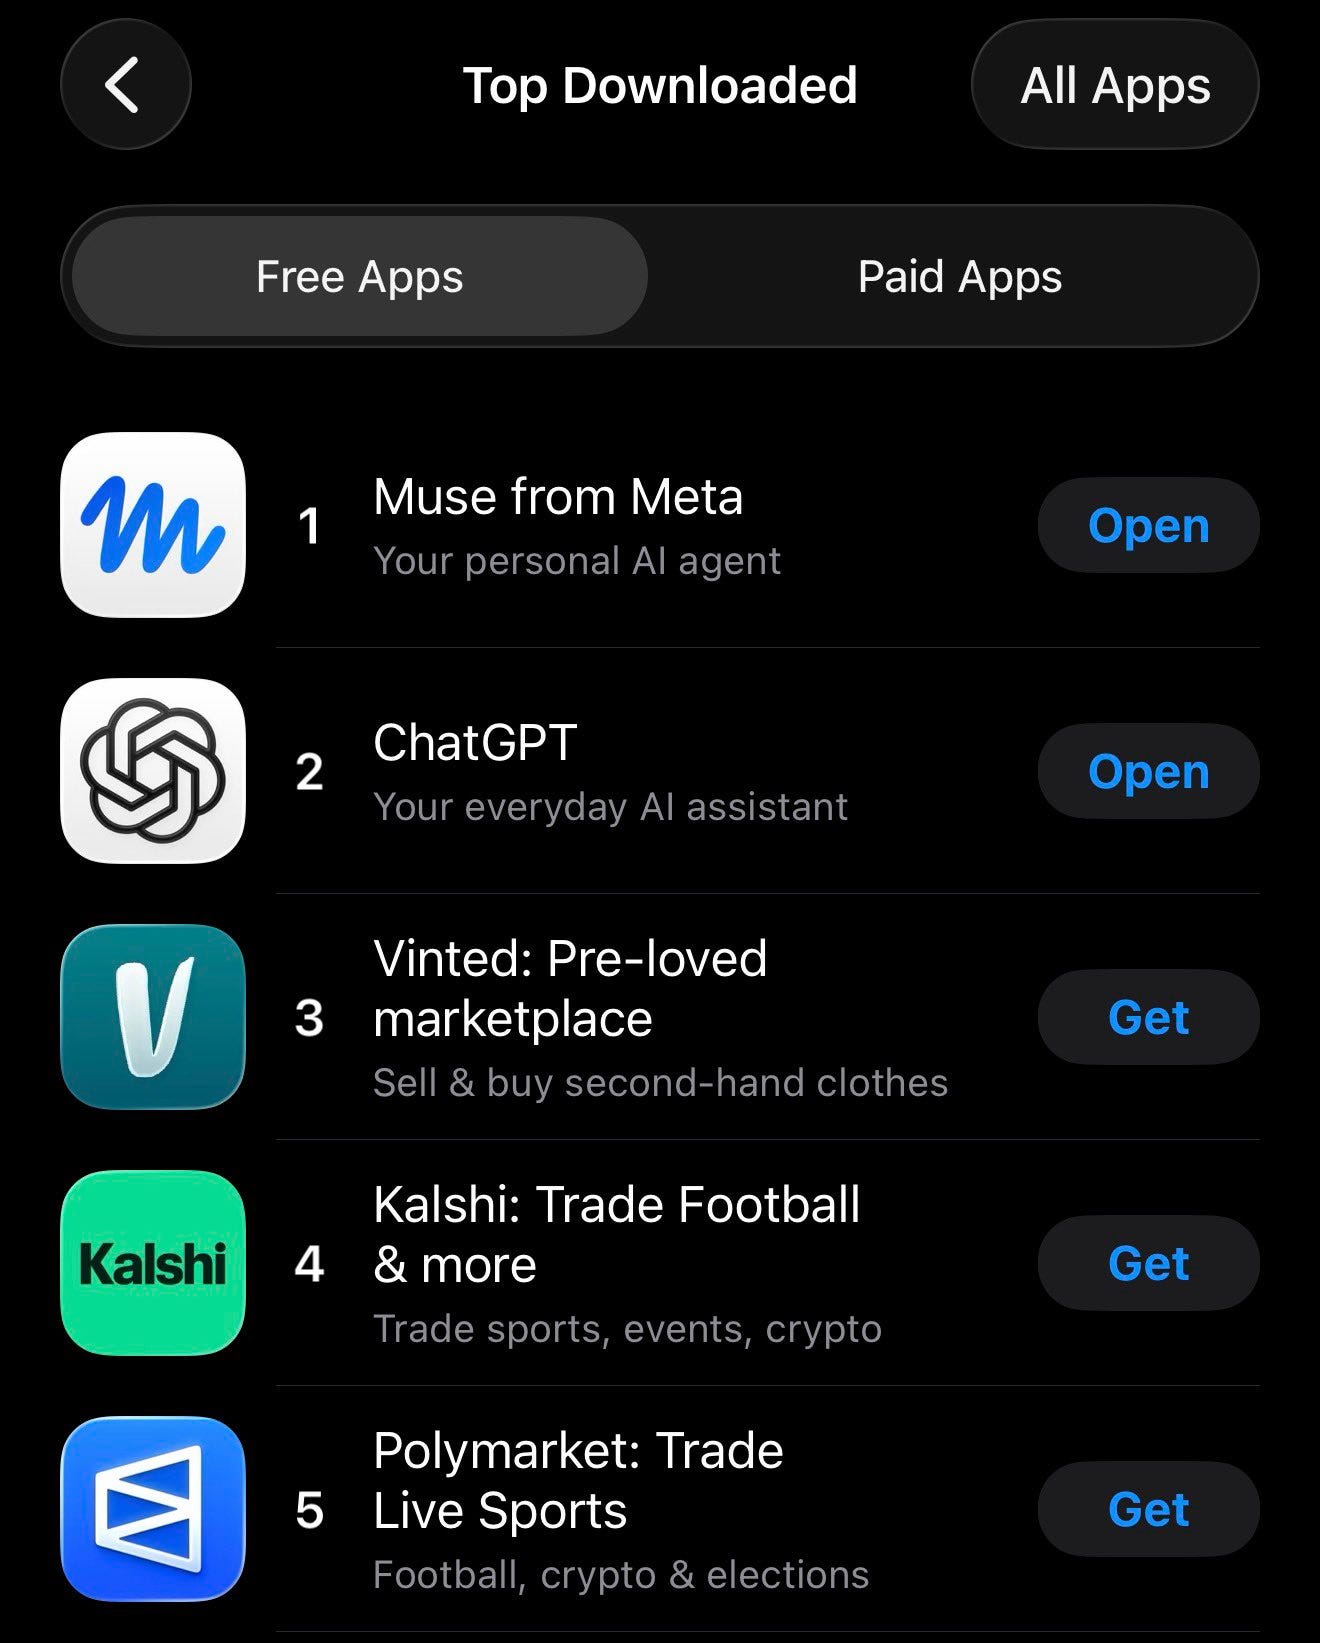
Meta’s Muse AI agent drove an 11% share surge, but OpenAI, Google and Apple could erode its early consumer lead.
A2Gold’s first Taylor drill holes returned 20.96 g/t AuEq over 1.5m and 209.4 g/t silver over 10.7m, alongside 141.10 g/t gold at…
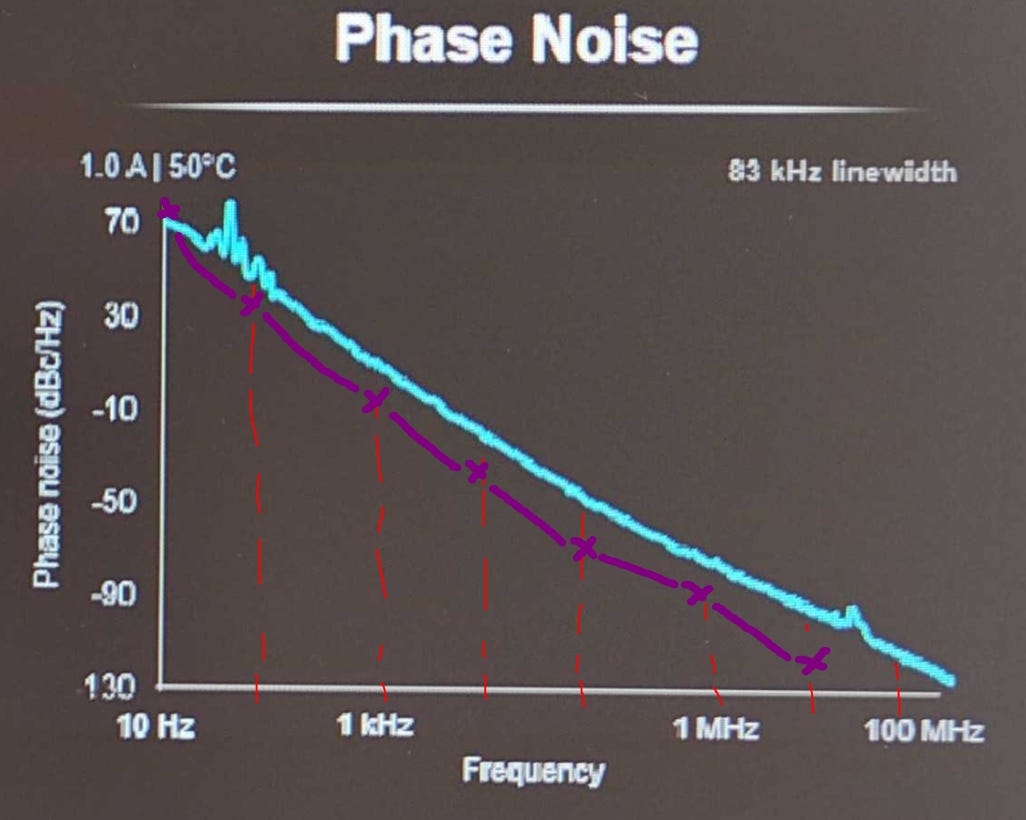
Coherent’s CPO/NPO laser misses 1 MHz effective-linewidth requirements, Irrational Analysis argues.
CoStar spent more than $1 billion building Homes.com to challenge Zillow, betting seller-agent leads, proprietary listing content and…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA PV Research Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.