No Cap? Currently Capped by Three Hundredths of a Percent: Medtronic’s MiniMed Split-Off Odd Lot
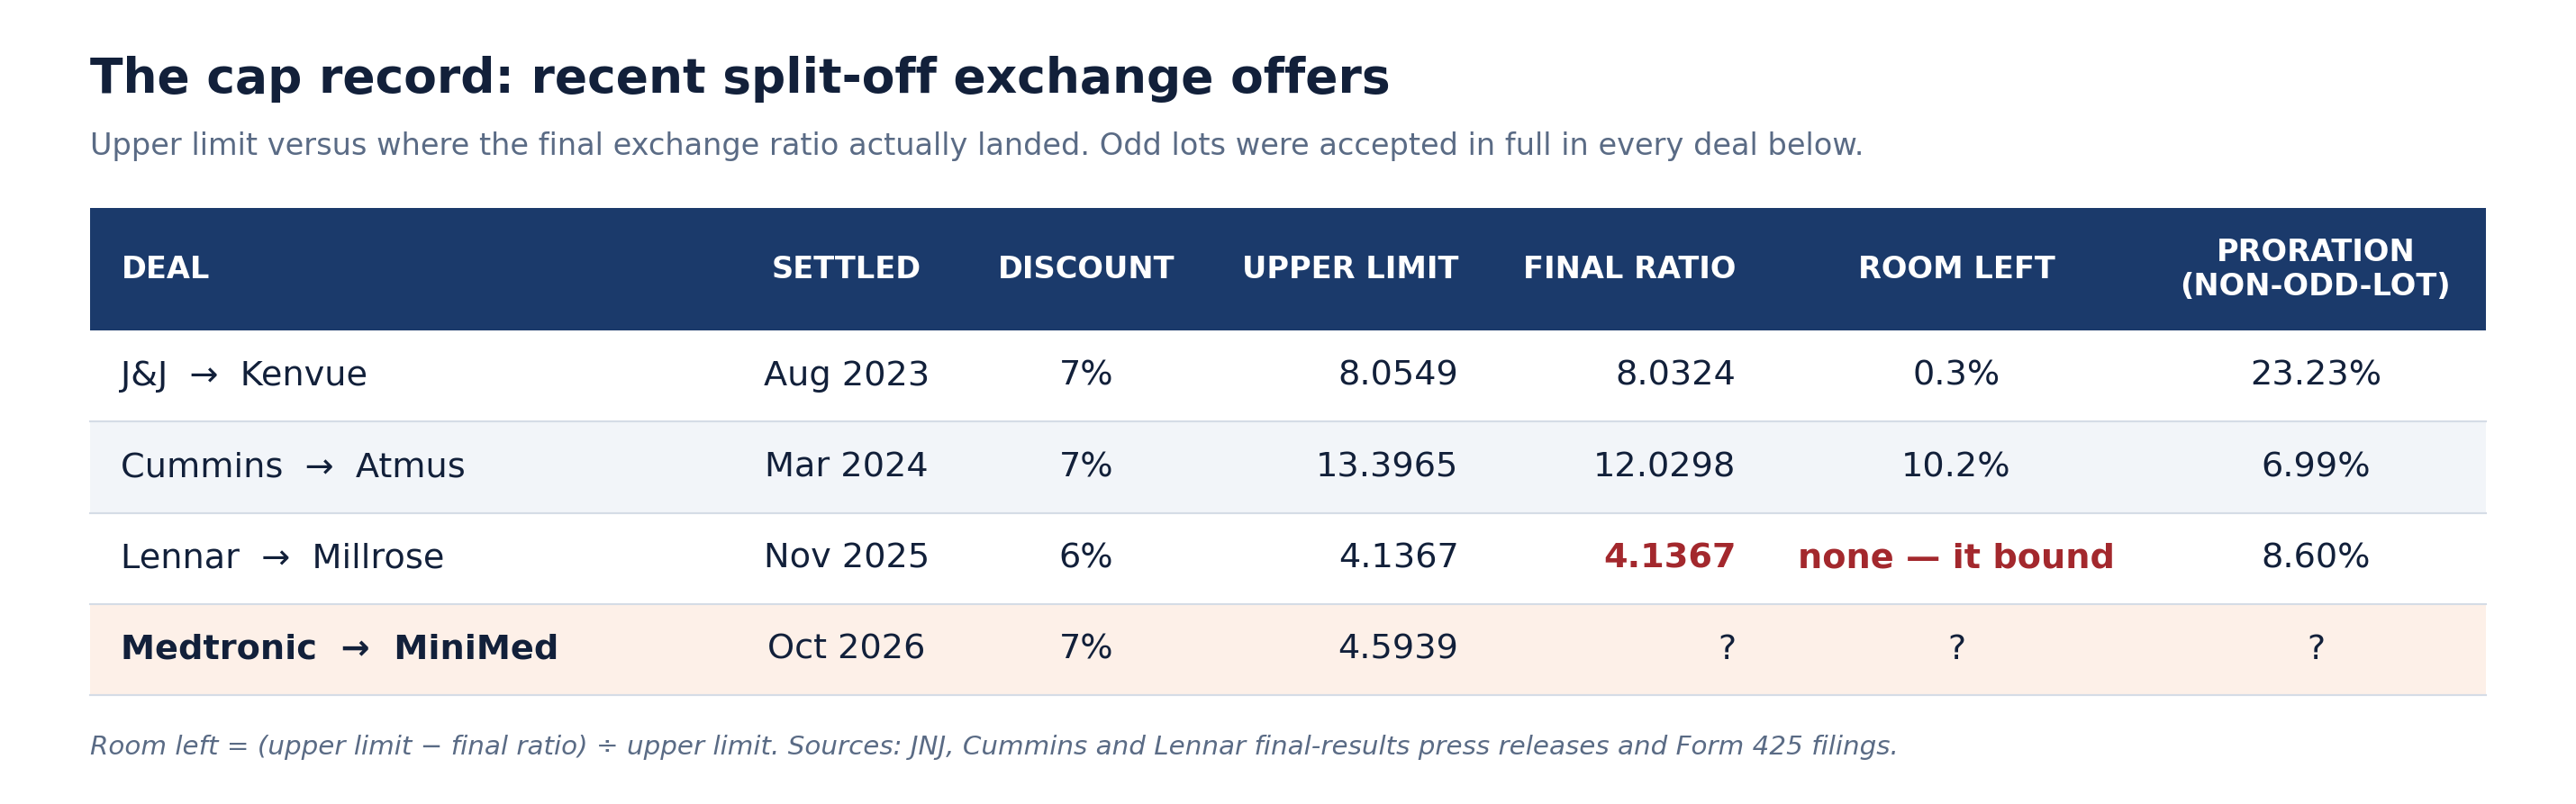
Medtronic’s MiniMed split-off gives odd-lot MDT holders priority on a 7% discounted exchange, but a 4.5939-share cap has begun reducing the payoff.
Medtronic’s MiniMed split-off gives odd-lot MDT holders priority on a 7% discounted exchange, but a 4.5939-share cap has begun reducing the payoff.
1/ So first things first, $HHH missed on top and bottom line. Am I concerned? Absolutely not. Value was created for shareholders and I'll briefly explain why...
$OII Niche leader in subsea robotics at 12x P/E. Offshore rig count accelerating (70% share), A&D growing DD, new autonomous tech a major growth driver in other end markets (lifts, etc). Investor day next week will showcase products and new LT targets. >50% NTM upside, IMO.
@TheMuffinMan28 SRS is a PE rollout, bit of a hodgepodge of assets. Concentration in landscaping, pool and roofing. No exclusive relationships (GMS is for $AWI, regional duopoly across most categories). End customers are small homebuilders (more competitive, less scale benefit for distributors).
$GMS Underfollowed building products distributor, HSD growth, favorable mix shift/ margin, tracking to beat estimates, trading at 10x EPS, 7x EBITDA. Peers at >50% higher multiples. $HD just acquired lower quality peer SRS for 17x EBITDA. GMS = $240 or +150% at that multiple.
Here is a little pricing guide for any of you looking into $HHH at the moment. Credit to @mfwarder for the format. https://t.co/MeZP5qopmR
@marginofdanger @BillAckman Additionally, $HHH as a pure play MPC is much more valuable than the sum of its parts. Though the market doesn't understand it well at the moment it will likely come to appreciate it more as it grows and produces substantial FCF. Patience is key here.
$CART Moved forward its lock-up expiration date to 2/16 (Thursday) from the original 3/19. >65% of the shares will be eligible for sale. COO leaving, just announced a restructuring w ambitious guidance. Almost certainly did so to support the stock in advance of a secondary.
$YOU Delta just significantly expanded its Digital ID program. This service is free, more efficient than Clear and now available in Clear's core markets. Other majors will have to follow in order to compete on service. Seems like this could kill $YOU in pretty short order. https://t.co/tgfebZZCWK
Cestrian initiated Joby Aviation at Accumulate and upgraded Applied Materials and Broadcom to Accumulate for the week ended 11 September…

Oracle’s $88.3 billion net debt and $90-95 billion capex plan pushed five-year CDS to 215 bps, despite 121% OCI growth and a $664 billion…
MKS Instruments posted $1.25 billion in Q2 revenue and is expanding Penang capacity for a $200 billion to $250 billion wafer-fab-equipment…
 The Straits Strategist

Adobe’s fiscal 3Q26 revenue grew 13%, while ARR growth was about 9.3% excluding Semrush.
Enel Chile uses battery storage and grid management to turn renewable oversupply into flexibility, lifting H1 2026 EBITDA 3.9% and net…
 Ryan Canady 4 clicks
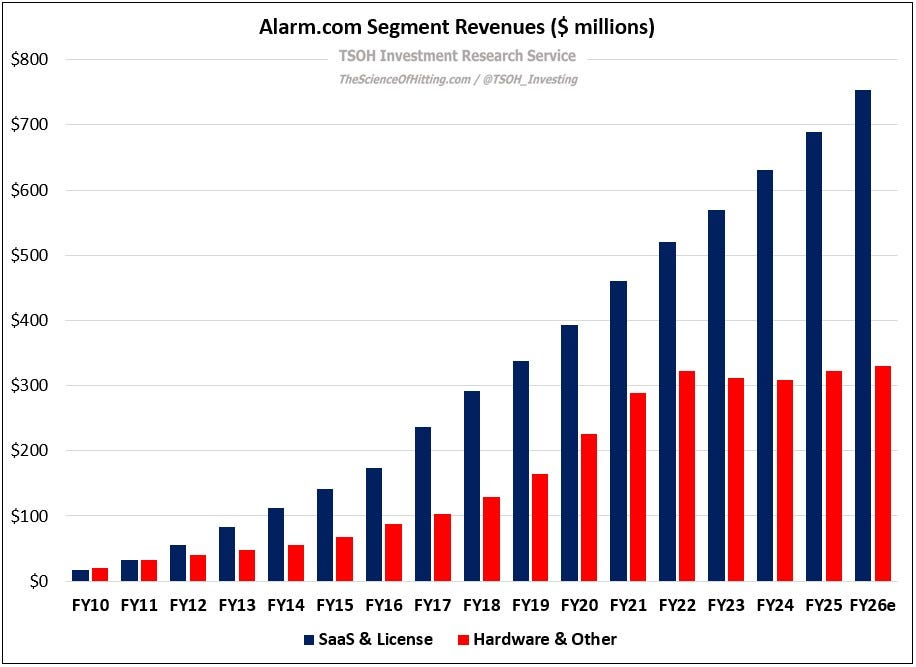
Alarm.com, founded after CEO Steve Trundle’s bad home-security experience, has fallen from $105 in 2020 to about $55, testing whether…
Booking Holdings trades at 19x earnings, its lowest since 2022, after a 20% annual decline, with the thesis resting on durable online…
Oak Bloke’s 2026 picks have returned 37% in GBP, with AltynGold, Geiger Counter, Silvercorp and China-focused trusts still rated buys…
Nintendo expects software, digital sales and character licensing to drive growth, with FY2027 revenue forecast at ¥2.05 trillion and…
 LL Insights

Ten-year Treasury yields breach 4.9% as Steve Eisman discusses AI fears, OpenAI's price cut, Oracle's 30% revenue growth and Tesla's…
 TYL · long
Tyler Technologies, TYL, is positioned as a resilient govtech software provider if AI disrupts enterprise SaaS.
Keurig Dr Pepper’s U.S. beverage growth and JDE Peet’s acquisition support earnings growth as coffee-cost and tariff pressures ease.
 Value Capital Research 1 click
Lululemon’s North American sales, margins and legging demand are falling as Alo and Vuori gain share, leaving its brand moat and depressed…
Chevron’s 2027 EPS could be underestimated by about $4.50 per share if U.S.-Iran conflict keeps oil near $100 rather than forecast $74 to…
 Envision Research 1 click
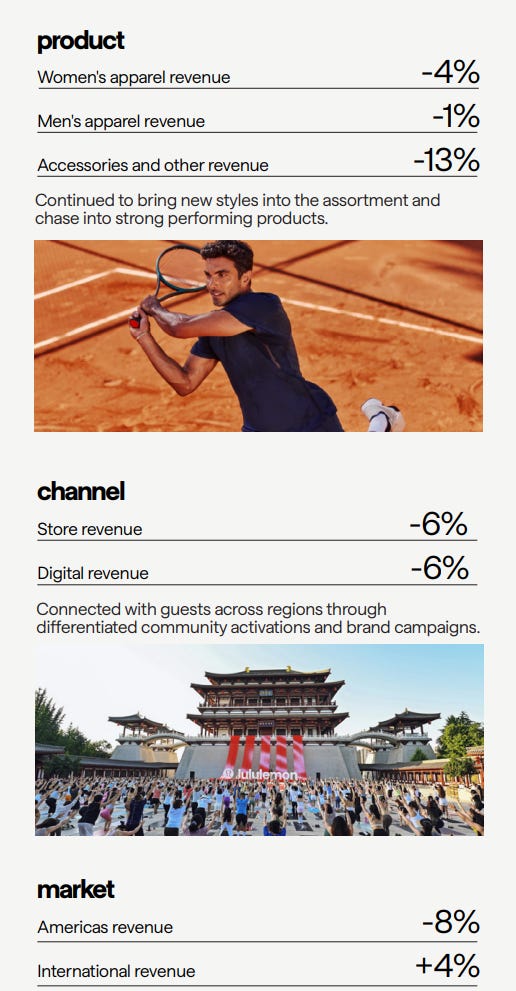
Lululemon’s growth stalled as affordable-luxury apparel brands face fading post-Covid demand, cheap social-media influence and China…
Apollo Global Management’s five defining deals, from Executive Life to Intel, built a $1 trillion asset manager spanning insurance and…

TSOH weekly roundup covers Meta’s child-safety settlement, Markel’s leadership transition, Peloton’s gym strategy and an upcoming Alarm.com…

Independence Realty Trust is buying Centerspace in stock to create an $8.1 billion apartment REIT, targeting 5% 2027 Core FFO per-share…
 Dane Bowler

Applied Materials reported Q3 revenue of $9.1 billion, up 25%, and $2.3 billion in free cash flow as AMAT fell roughly 40% from its June…

Joby Aviation is initiated at Accumulate after booking $116m of trailing revenue, forming a Toyota manufacturing venture and agreeing to…
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.