Booking Holdings Deep Dive: An Attractive Setup
Booking Holdings trades at 19x earnings, its lowest since 2022, after a 20% annual decline, with the thesis resting on durable online travel growth.
Booking Holdings trades at 19x earnings, its lowest since 2022, after a 20% annual decline, with the thesis resting on durable online travel growth.
$AVO $CVGW 1) Retailers $CMG, etc sourcing elsewhere given MX tariff risk. 2) Avocado price spike during last year’s peak harvest season enabled distributors to realize outsized margins. 1-time benefit has reversed, significant earnings misses ahead for these commodity businesses
$NX Outlandishly guiding to flat 2025 sales, customers and channel -DD. Commodity window and door components facing pricing pressure from larger customers ($JELD, $OC). Now levered 4x, trading at a premium to higher value-add building products peers. Guide cut inevitable.
$J Beat earnings yesterday. Holding back detailed guidance for Investor Day (2/18)—likely raise ’25 #s, 4-year financial targets w significant upside on margins ($ACM and other peers +15% EBITDA margins). Record backlog and multi-year growth runway.
The industrial logic for the $UNF and $CTAS merger captured in one picture. Both have been going to the Chipotle (or same strip center) near our office in Houston on the same days at the same time (the store was closed at the time this pic was taken). https://t.co/zxTIFVgn1s
$NX Rapidly declining levered (4x) commodity biz. Q1’25 guide -12% sales, mgmt hoping for 2H’25 recovery. End-mkts deteriorating ($OC -20% Q4 guide, $JELD), customer losses, internal controls issues, integrating a large acq, 0 prior M&A experience. +30x P/E on best case 2025 #s
@StockJabber Thank you. As a read on $PLUS Q3 is tracking in October, $CSCO just reported -23% sales in networking (products account for ~50% of $PLUS revenue) for the Oct quarter-end. Further confirmation that PLUS Q3 is going to be ugly and no turnaround in sight.
$PLUS Accelerating, sales -14% y/y in Q2, noted Q3 not improving yet implied FY guide is for flat sales (downward revisions to come). Margins benefitted from 1-time financing segment gain-on-sale. Still trading at a premium to higher quality industry leader CDW, makes zero sense.
$AS 50x P/E levered retail roll-up w only one decent asset (Arc’teryx). Stagnating in the US, nearly fully-penetrated in China. >$500 jackets didn’t work for $GOOS in Asia. Arc already bigger. Hyper promotional mgmt sent the stock skyward. This is going to be an epic crash.
Lululemon’s North American sales, margins and legging demand are falling as Alo and Vuori gain share, leaving its brand moat and depressed…
Chevron’s 2027 EPS could be underestimated by about $4.50 per share if U.S.-Iran conflict keeps oil near $100 rather than forecast $74 to…
 Envision Research 1 click
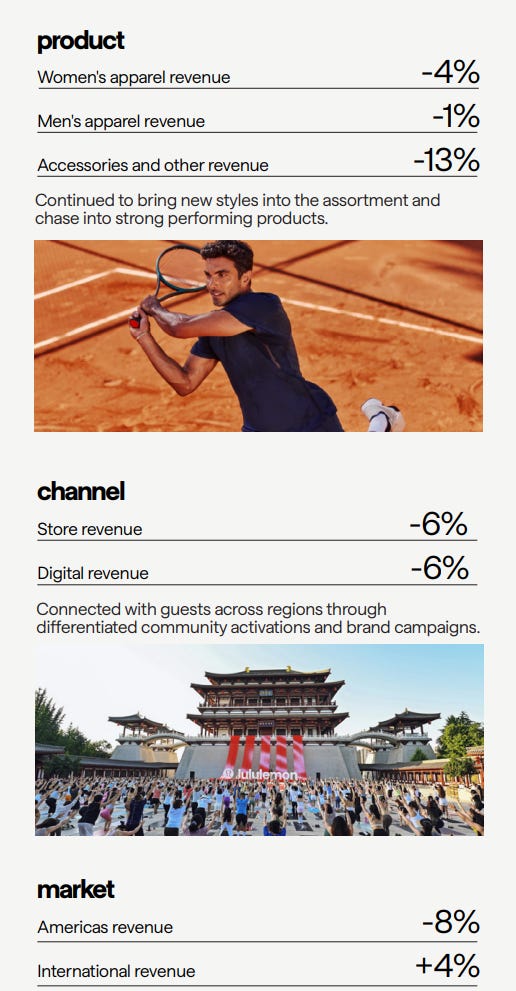
Lululemon’s growth stalled as affordable-luxury apparel brands face fading post-Covid demand, cheap social-media influence and China…
Apollo Global Management’s five defining deals, from Executive Life to Intel, built a $1 trillion asset manager spanning insurance and…

TSOH weekly roundup covers Meta’s child-safety settlement, Markel’s leadership transition, Peloton’s gym strategy and an upcoming Alarm.com…

Applied Materials reported Q3 revenue of $9.1 billion, up 25%, and $2.3 billion in free cash flow as AMAT fell roughly 40% from its June…

Joby Aviation is initiated at Accumulate after booking $116m of trailing revenue, forming a Toyota manufacturing venture and agreeing to…

Qualcomm offers more valuation cushion than Marvell despite Marvell’s stronger AI revenue, as its Amazon partnership supports data-center…
 Delta Analyst

AppLovin trades at 18 times EBITDA after a 57% drop, despite 84% EBITDA margins, rapid growth and a machine-learning advertising platform.
Williams Companies faces a revoked Northeast pipeline permit while pursuing growth through Momentum Midstream, Gulf export access and…
 Long Player
 UHS · long
Universal Health Services is a profitable hospital operator whose $146 share price over-discounts an earnings-collapse scenario.

USA Compression targets nearly 30% full-year EBITDA growth as JW Power synergies, telemetry and maintenance reduce costs; its units yield…
 Ron Ferrie 3 clicks
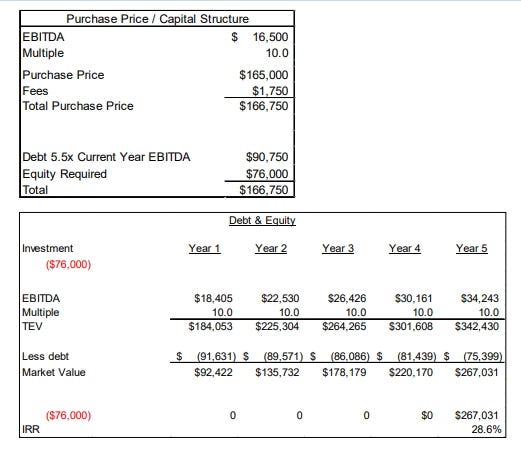
TransDigm’s sole-source aerospace parts generate roughly 70% aftermarket margins, with 90% of revenue tied to owned IP and 80% from…
Deckers Outdoor has fallen about 60% from its late-2024 peak and trades at 11x earnings as HOKA growth slows.
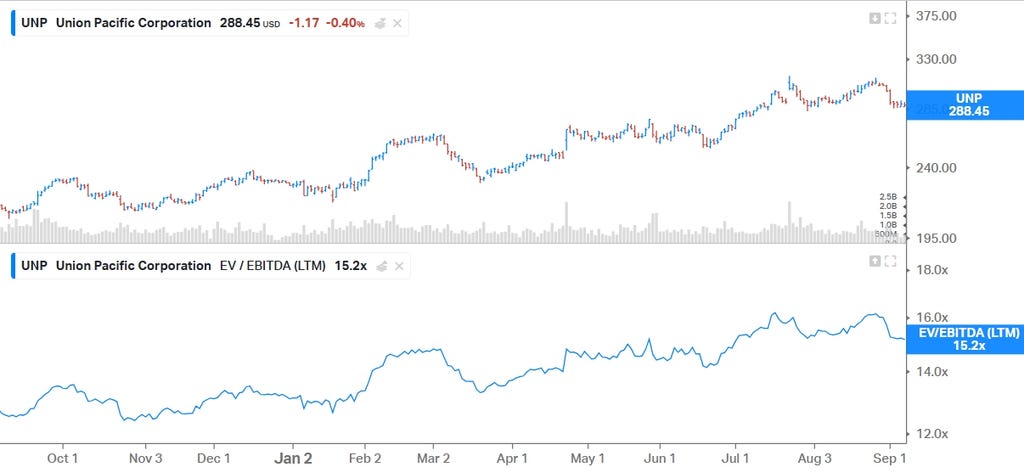
Union Pacific’s $85 billion Norfolk Southern merger pitch centers on a coast-to-coast rail network that cuts interchange delays and wins…

Dell’s Q2 revenue rose 57.7% to $47.0 billion and RPO tripled to $132 billion, but its stock trades at 32 times unlevered pretax free cash…
Lululemon’s Q2 revenue fell 4% and Americas comparable sales 12%, as markdowns, tariffs and activewear rivals pressure its premium apparel…
Qualcomm targets $15 billion of data-center revenue by FY2029 through AI accelerators, custom ASICs, Arm server CPUs and hyperscaler wins.
 Khaveen Investments
Ryan Tunis discusses P&C insurers, favoring Travelers over Chubb in a soft commercial market and calling AIG a near-book-value self-help…
Pinterest’s Q2 showed reaccelerating North American growth, while weaker international trends, AI-related engagement risks and elevated…
 Richard Durant 2 clicks
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.