Veeva 2Q’26: “SaaSpocalypse” Cancelled
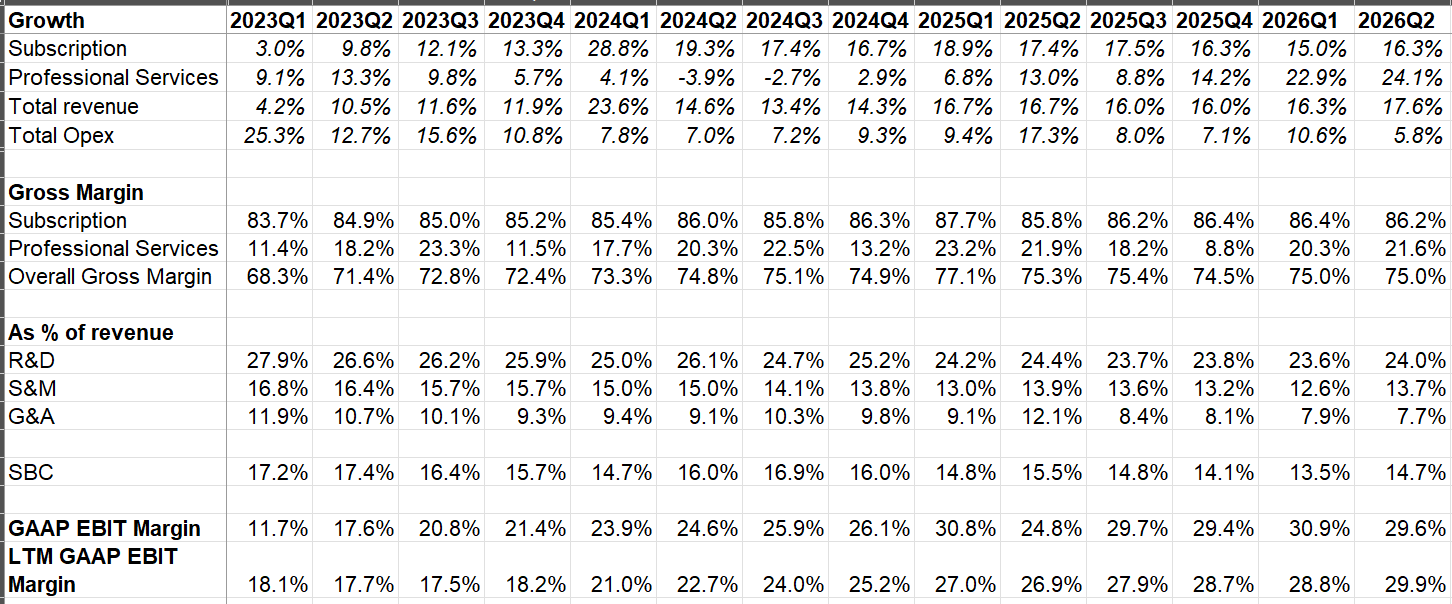
Veeva beat its $905 million revenue guide with $928 million, up 17.6%, while subscription growth accelerated and GAAP EBIT margin reached 29.6%.
Veeva beat its $905 million revenue guide with $928 million, up 17.6%, while subscription growth accelerated and GAAP EBIT margin reached 29.6%.
$FTDR Vol declining (existing home sales=driver). Pricing lagging inflation, massively over-earning. Problematic given 25% churn w aggressive new entrants. Dubious company overall. Investor day yesterday was comical, compared themselves to $NFLX. Earnings misses coming.
$AVO $CVGW 1) Retailers $CMG, etc sourcing elsewhere given MX tariff risk. 2) Avocado price spike during last year’s peak harvest season enabled distributors to realize outsized margins. 1-time benefit has reversed, significant earnings misses ahead for these commodity businesses
$NX Outlandishly guiding to flat 2025 sales, customers and channel -DD. Commodity window and door components facing pricing pressure from larger customers ($JELD, $OC). Now levered 4x, trading at a premium to higher value-add building products peers. Guide cut inevitable.
$J Beat earnings yesterday. Holding back detailed guidance for Investor Day (2/18)—likely raise ’25 #s, 4-year financial targets w significant upside on margins ($ACM and other peers +15% EBITDA margins). Record backlog and multi-year growth runway.
$NX Rapidly declining levered (4x) commodity biz. Q1’25 guide -12% sales, mgmt hoping for 2H’25 recovery. End-mkts deteriorating ($OC -20% Q4 guide, $JELD), customer losses, internal controls issues, integrating a large acq, 0 prior M&A experience. +30x P/E on best case 2025 #s
@StockJabber Thank you. As a read on $PLUS Q3 is tracking in October, $CSCO just reported -23% sales in networking (products account for ~50% of $PLUS revenue) for the Oct quarter-end. Further confirmation that PLUS Q3 is going to be ugly and no turnaround in sight.
$PLUS Accelerating, sales -14% y/y in Q2, noted Q3 not improving yet implied FY guide is for flat sales (downward revisions to come). Margins benefitted from 1-time financing segment gain-on-sale. Still trading at a premium to higher quality industry leader CDW, makes zero sense.
$AS 50x P/E levered retail roll-up w only one decent asset (Arc’teryx). Stagnating in the US, nearly fully-penetrated in China. >$500 jackets didn’t work for $GOOS in Asia. Arc already bigger. Hyper promotional mgmt sent the stock skyward. This is going to be an epic crash.
 MU 2026-08-28
SK Hynix posted record quarterly revenue of 79.32 trillion won and a 76% operating margin, while trading below Micron on forward sales and…
 Prakhar Agarwal, CFA 4 clicks
Sandisk’s FY28-FY30 model relies on long-term NAND agreements holding near-80% gross-margin floors despite pricing 26-28% below current…

Higher rates could compress equity multiples and raise AI data center lease costs, while UWMC and Cogent raise questions about CEO-driven…
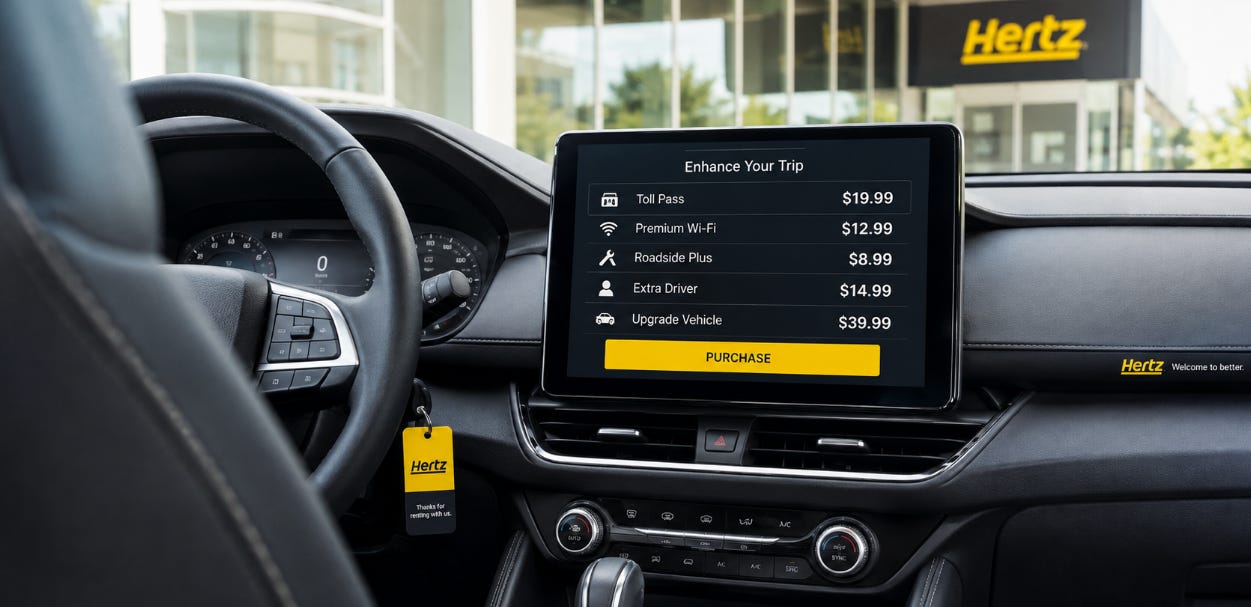
Verra Mobility renewed Hertz tolling management for five years. AutoKinex lets rental customers buy tolling, fuel and protection products…
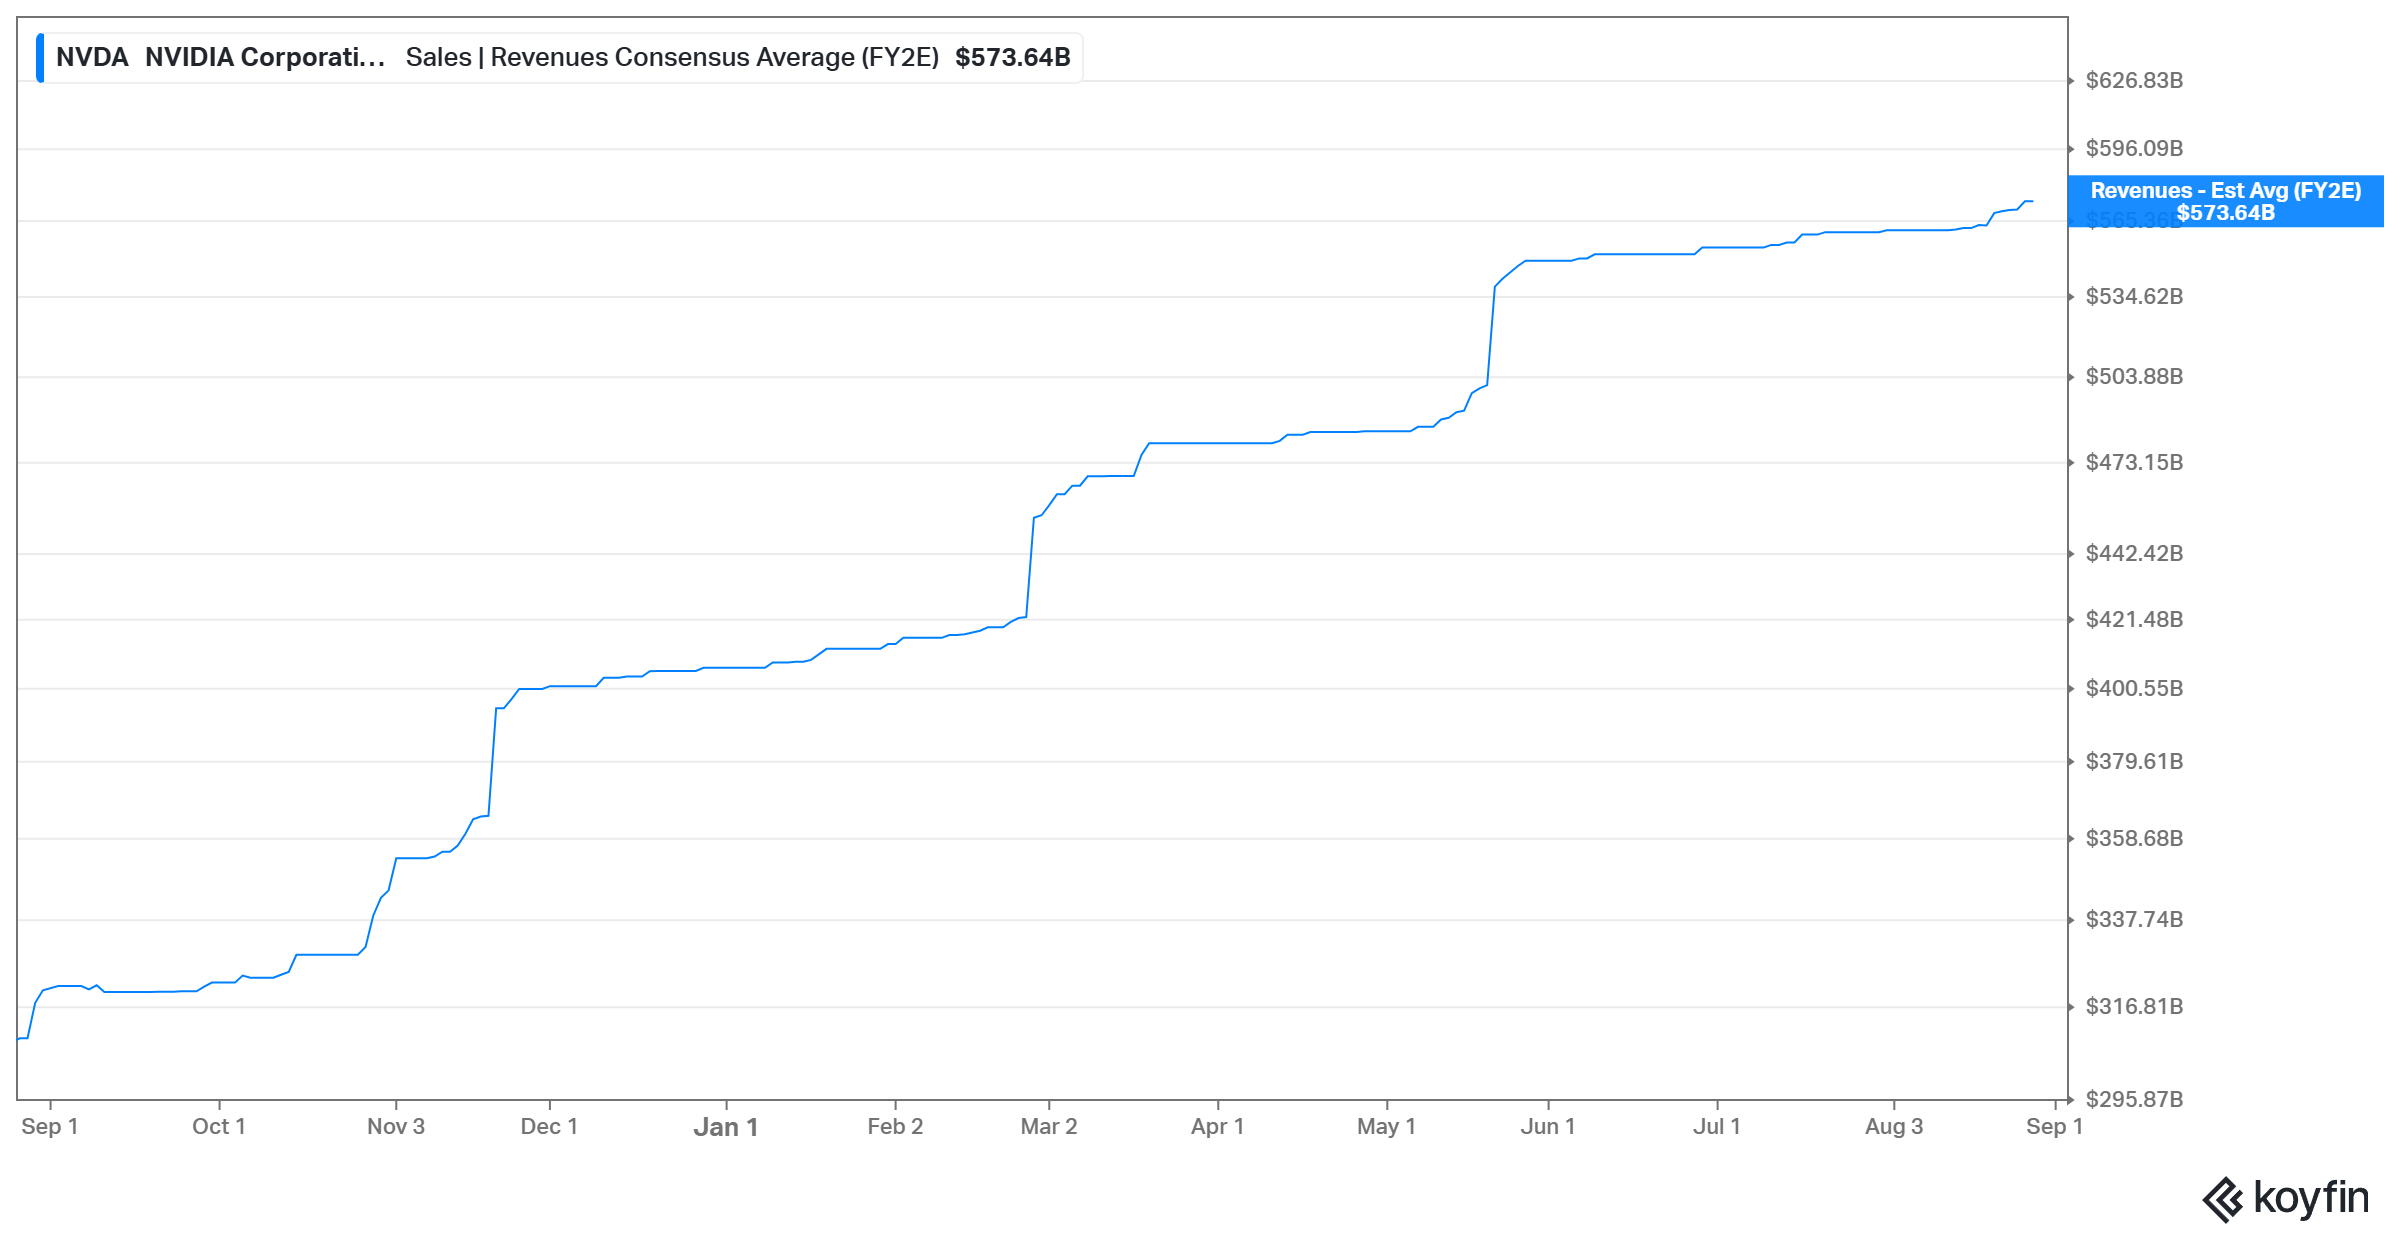
Nvidia guided FY2028 revenue toward $700 billion, roughly 70% growth, while supply constraints and neocloud demand face concerns over…
Domo’s $400 million sale to Progress would leave a cash-rich public shell with $900 million of NOLs; January 2028 $5 calls cost 22 cents.
MT 2026-08-27 ArcelorMittal’s regional steel franchises, integrated mining and India expansion are lifting EBITDA per ton and supporting per-share…
 Capital Connoisseur 1 click
AWS AI campuses cost $40–$45 billion per gigawatt, with Trainium 3 expected to lift compute per megawatt and improve infrastructure returns.
KMI 2026-08-26 Kinder Morgan raised 2026 guidance after record Q2 results, supported by a $9.6 billion backlog and growing U.S.
 Steven Fiorillo 1 click

El Al trades near 2x EBITDA after wartime near-monopoly profits, with $1.3 billion of net cash and owned aircraft weighed against…
 EGO · long
Eldorado Gold (EGO) is a long-life gold and copper miner with a rare growth profile across precious and base metals.
SBAC 2026-08-29 SBA Communications, target $230, pairs 2.3% Q2 revenue growth from international leasing with a 41% dividend payout ratio, buybacks and…
 Philip Wang 2 clicks
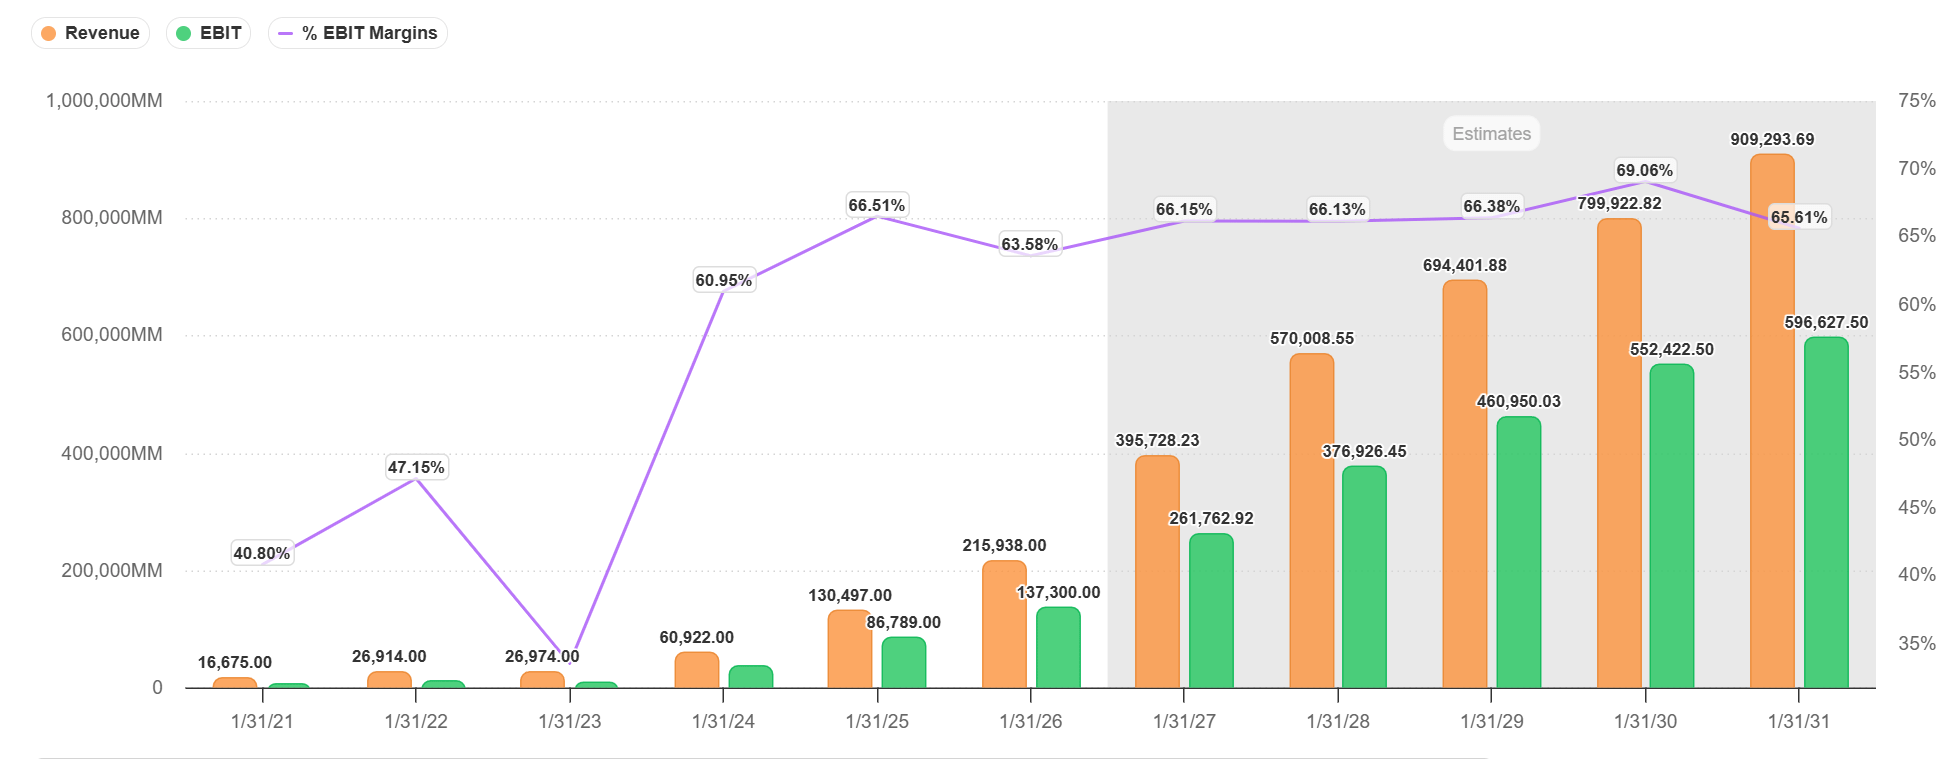
Nvidia faces questions over the durability of its long-term profit margins ahead of earnings.
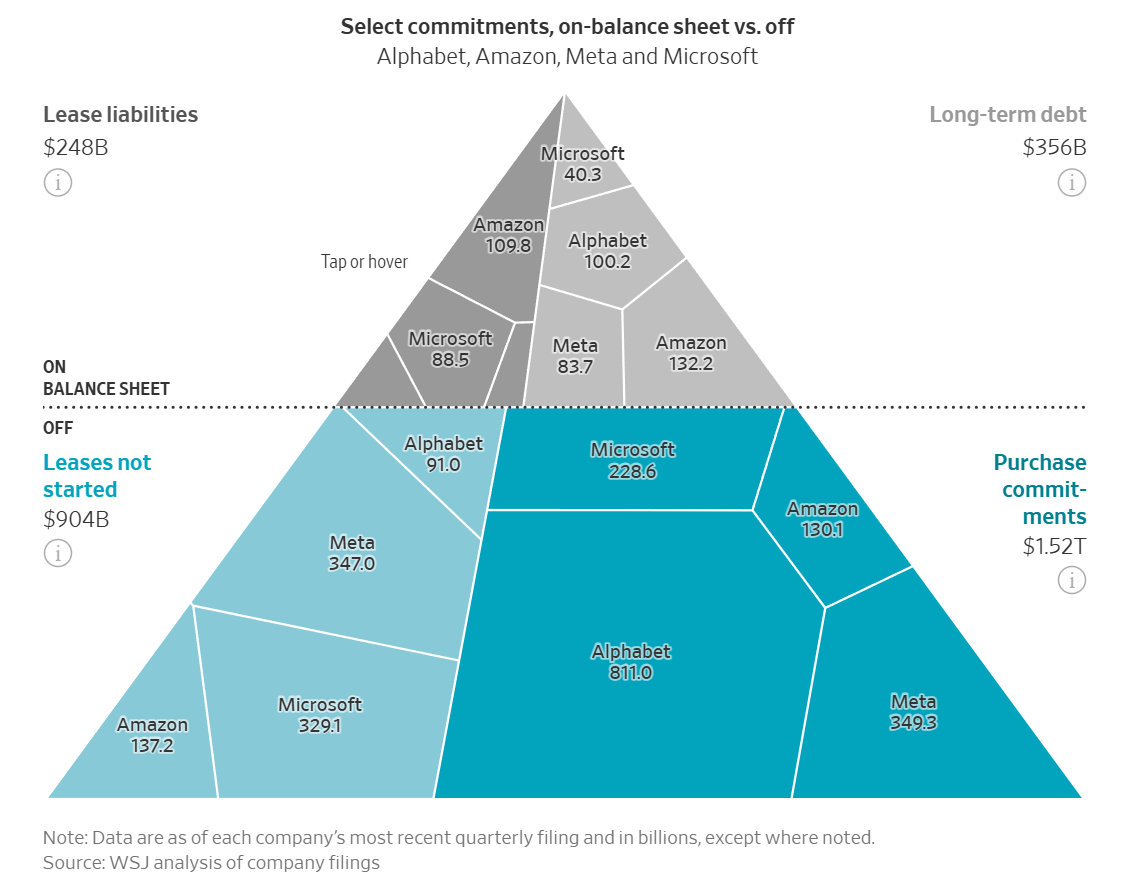
Big Tech’s $3 trillion AI commitments are disclosed and largely long-dated, with nearly 60% of Amazon’s $650 billion commitments falling…
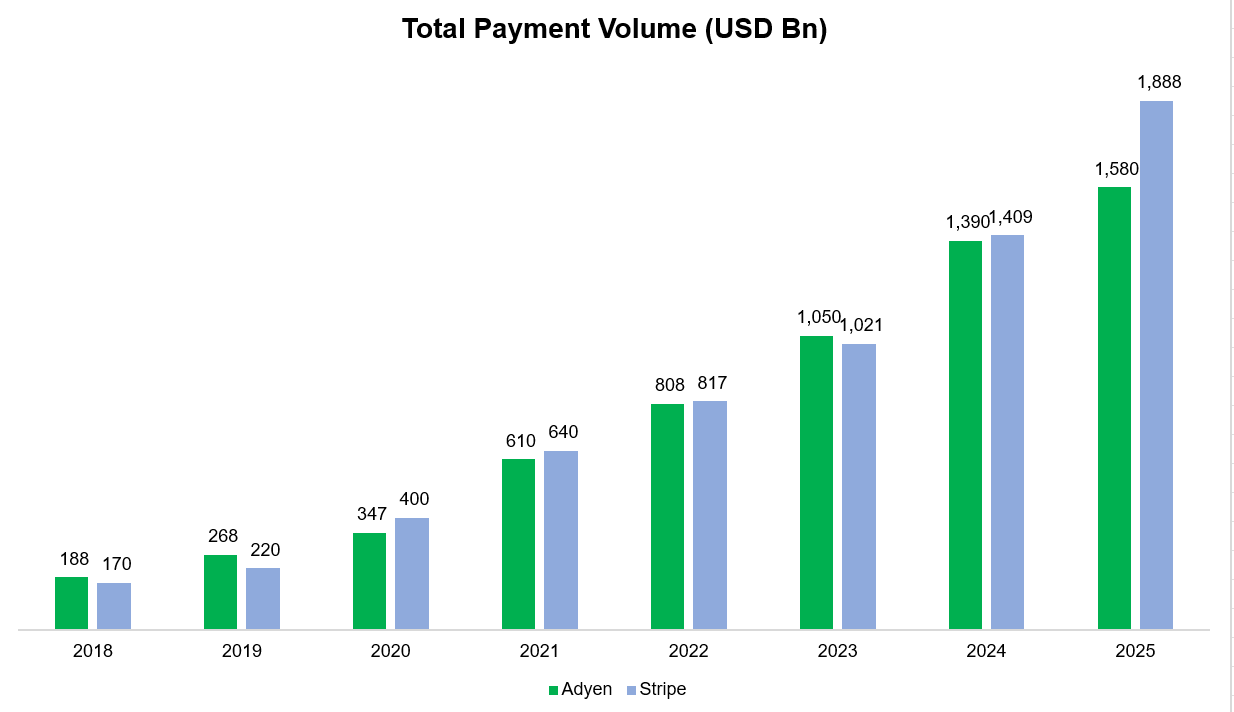
Stripe’s net revenue rose 41% in 1H 2026 versus Adyen’s 21% FX-adjusted growth, fueled by AI-native startups and acquisitions including…
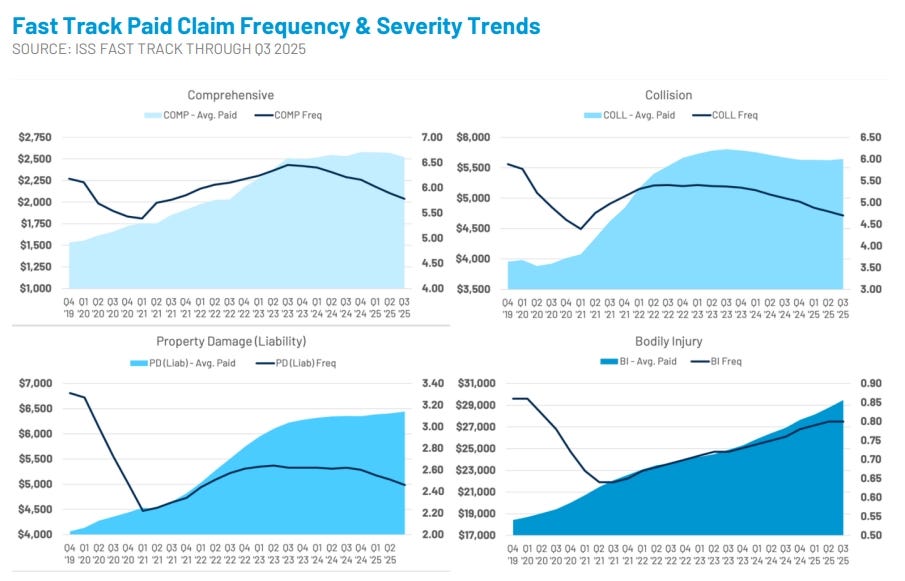
CCC, the dominant auto physical-damage claims estimator, connects 27 of the top 30 insurers with 31,000 repair shops as takeout rumors…
TEM 2026-08-20 Tempus AI's diagnostics and data businesses grew Q2 2026 revenue 19.4% year over year, with FDA approvals, expanded tests and pricing aimed…
Verra Mobility's new seven-year Avis agreement replaces a customer worth over 10% of revenue on materially worse economics, exposing…
BHP 2026-08-20 BHP expects copper to generate over half of FY2026 EBITDA and plans a 40% production increase by FY2035 after profit, free cash flow and…
 On the Pulse 1 click
Norwegian Cruise Line’s $15 billion debt and 2026-27 capex delay deleveraging, despite fuel-efficient new ships and stronger projected 2028…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports Philip Wang Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.