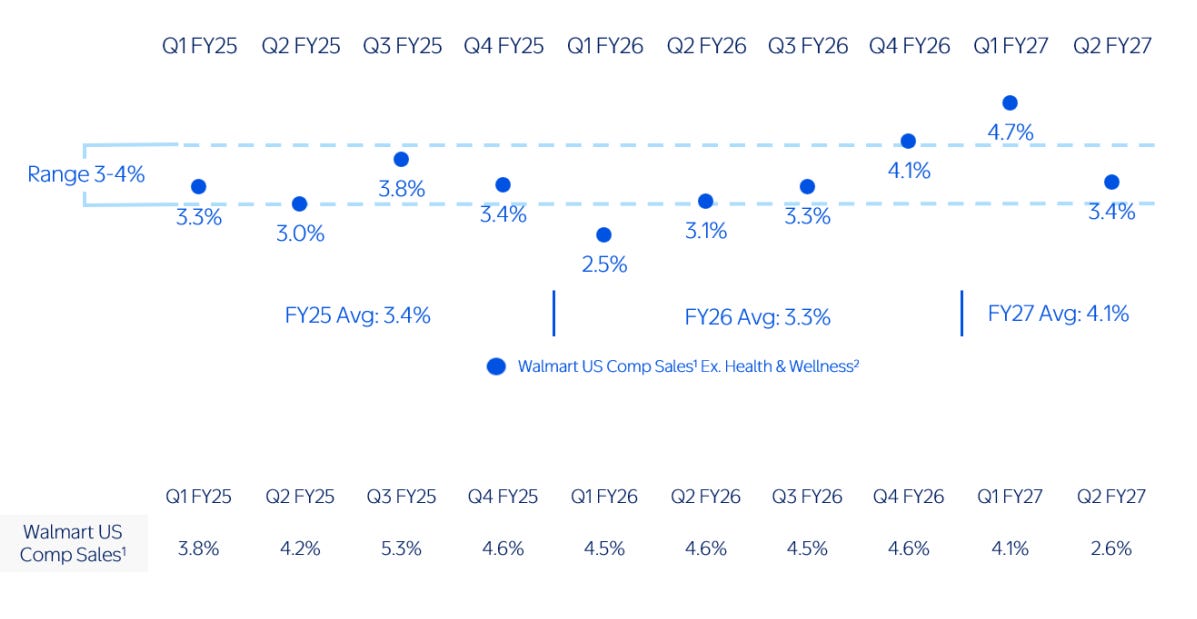
Walmart’s Evolution
Walmart says Medicare Maximum Fair Price rules will cut FY27 US comps by 125 basis points, while pharmacy margins and prescription volumes remain resilient.
Walmart says Medicare Maximum Fair Price rules will cut FY27 US comps by 125 basis points, while pharmacy margins and prescription volumes remain resilient.
@finphysnerd $cme and $otcm are in this category and are reasonable
In Play Today: UMB Financial $UMBF reiterates future M&A requirements; Blue Owl rejects buyout offer | S&P Global Market Intelligence https://t.co/qDTqHhJTSr
Seems like $PSUS and $PS going to trade worse than I expected. Looks like PSUS could open at a 20% discount to NAV and PS to trade below the $10 bn valuation from the latest 3rd party pre-IPO raise. https://t.co/Ix6uqF61LJ https://t.co/F5UNDNNVMb
@EricTheUmpire If you want exposure, buy $PSH.LN (or $PSHZF) which is trading at around 70% of NAV (implies $35/share for $PSUS). https://t.co/oSFLPLfnqr
I just published my Earnings Update about the Q1 2026 of Evolution $EVO $EVVTY. You can find it in the Portfolio section of the blog :) https://t.co/QXlBS93lji
@JeffreyCherkin Not a bad purchase of $FTAI this time last year < $90! @MelissaLeeCNBC
 CRWV 2026-08-19
CoreWeave’s Q2 converted backlog into sales, expanded margins and lifted operating leverage as active contracts topped half of its $104.2…
 Future Stack Investment

IREN awarded each co-CEO roughly 9 million RSUs, about 2.5% of shares and $400 million, in exchange for no further equity grants until…

Nubank's 140 million customers, 20% efficiency ratio and 30% ROE frame whether its high-teens P/E reflects a scalable fintech or a maturing…
HubSpot trades near its 2020 share price despite quadrupled revenue and $750 million in free cash flow, with Breeze AI upside weighed…
Zoetis’s U.S. companion-animal revenue fell 6% as dermatology competition drove rebates and discounts, pushing full-year net pricing to…
Copart faces a near-term lift from pricier AV repairs and total losses, but shrinking accident volumes could eventually force its…

GFL’s proposed acquisition of Secure follows 19% revenue growth at Secure and 14.8% EBITDA growth at GFL, with Permian produced-water and…

Glenn Schorr and Ken Worthington discuss risks in private-credit software loans, agentic AI at retail brokers, crypto use cases and bank…

Coupang’s product-commerce revenue rose 8% in constant currency as data-leak churn lingered, while promotions and underused logistics…
Old Dominion Freight Line grew Q2 revenue 10.4% and EPS 32.3% as pricing offset lower tonnage, while excess network capacity sets up…
 DASH · long
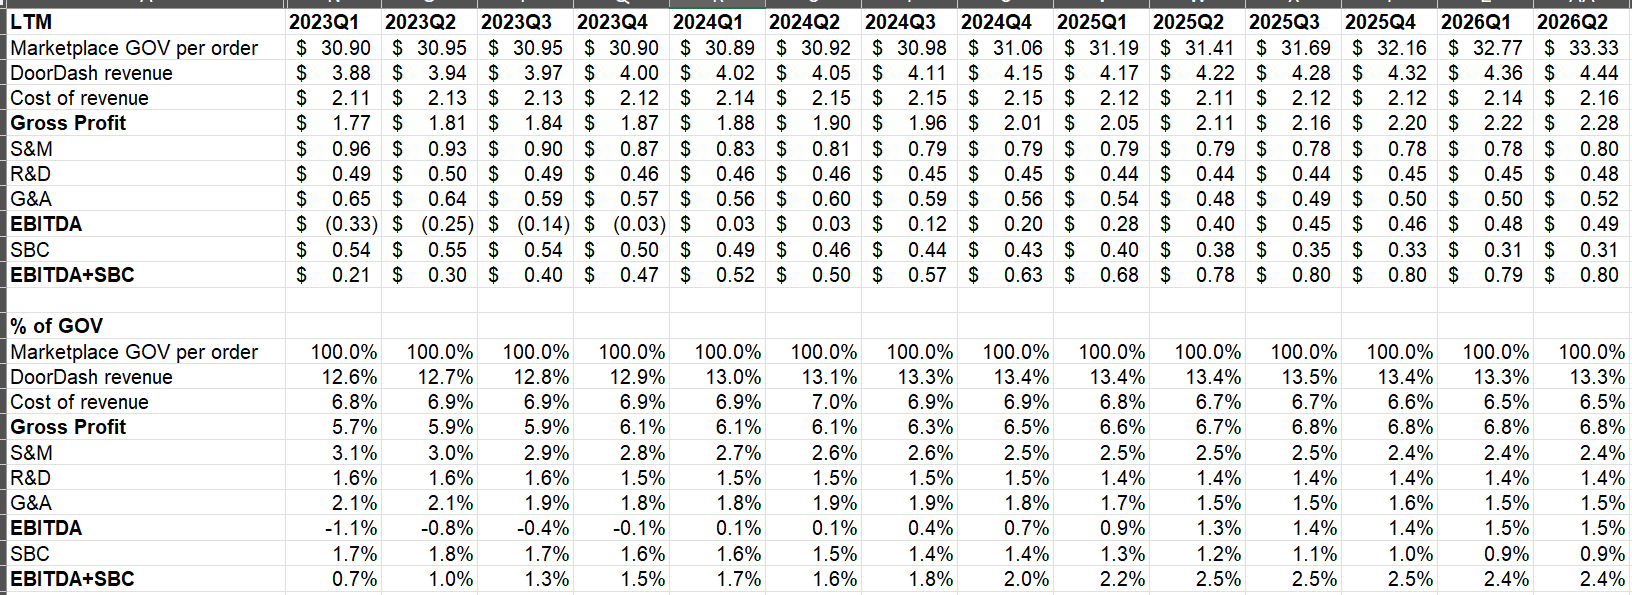
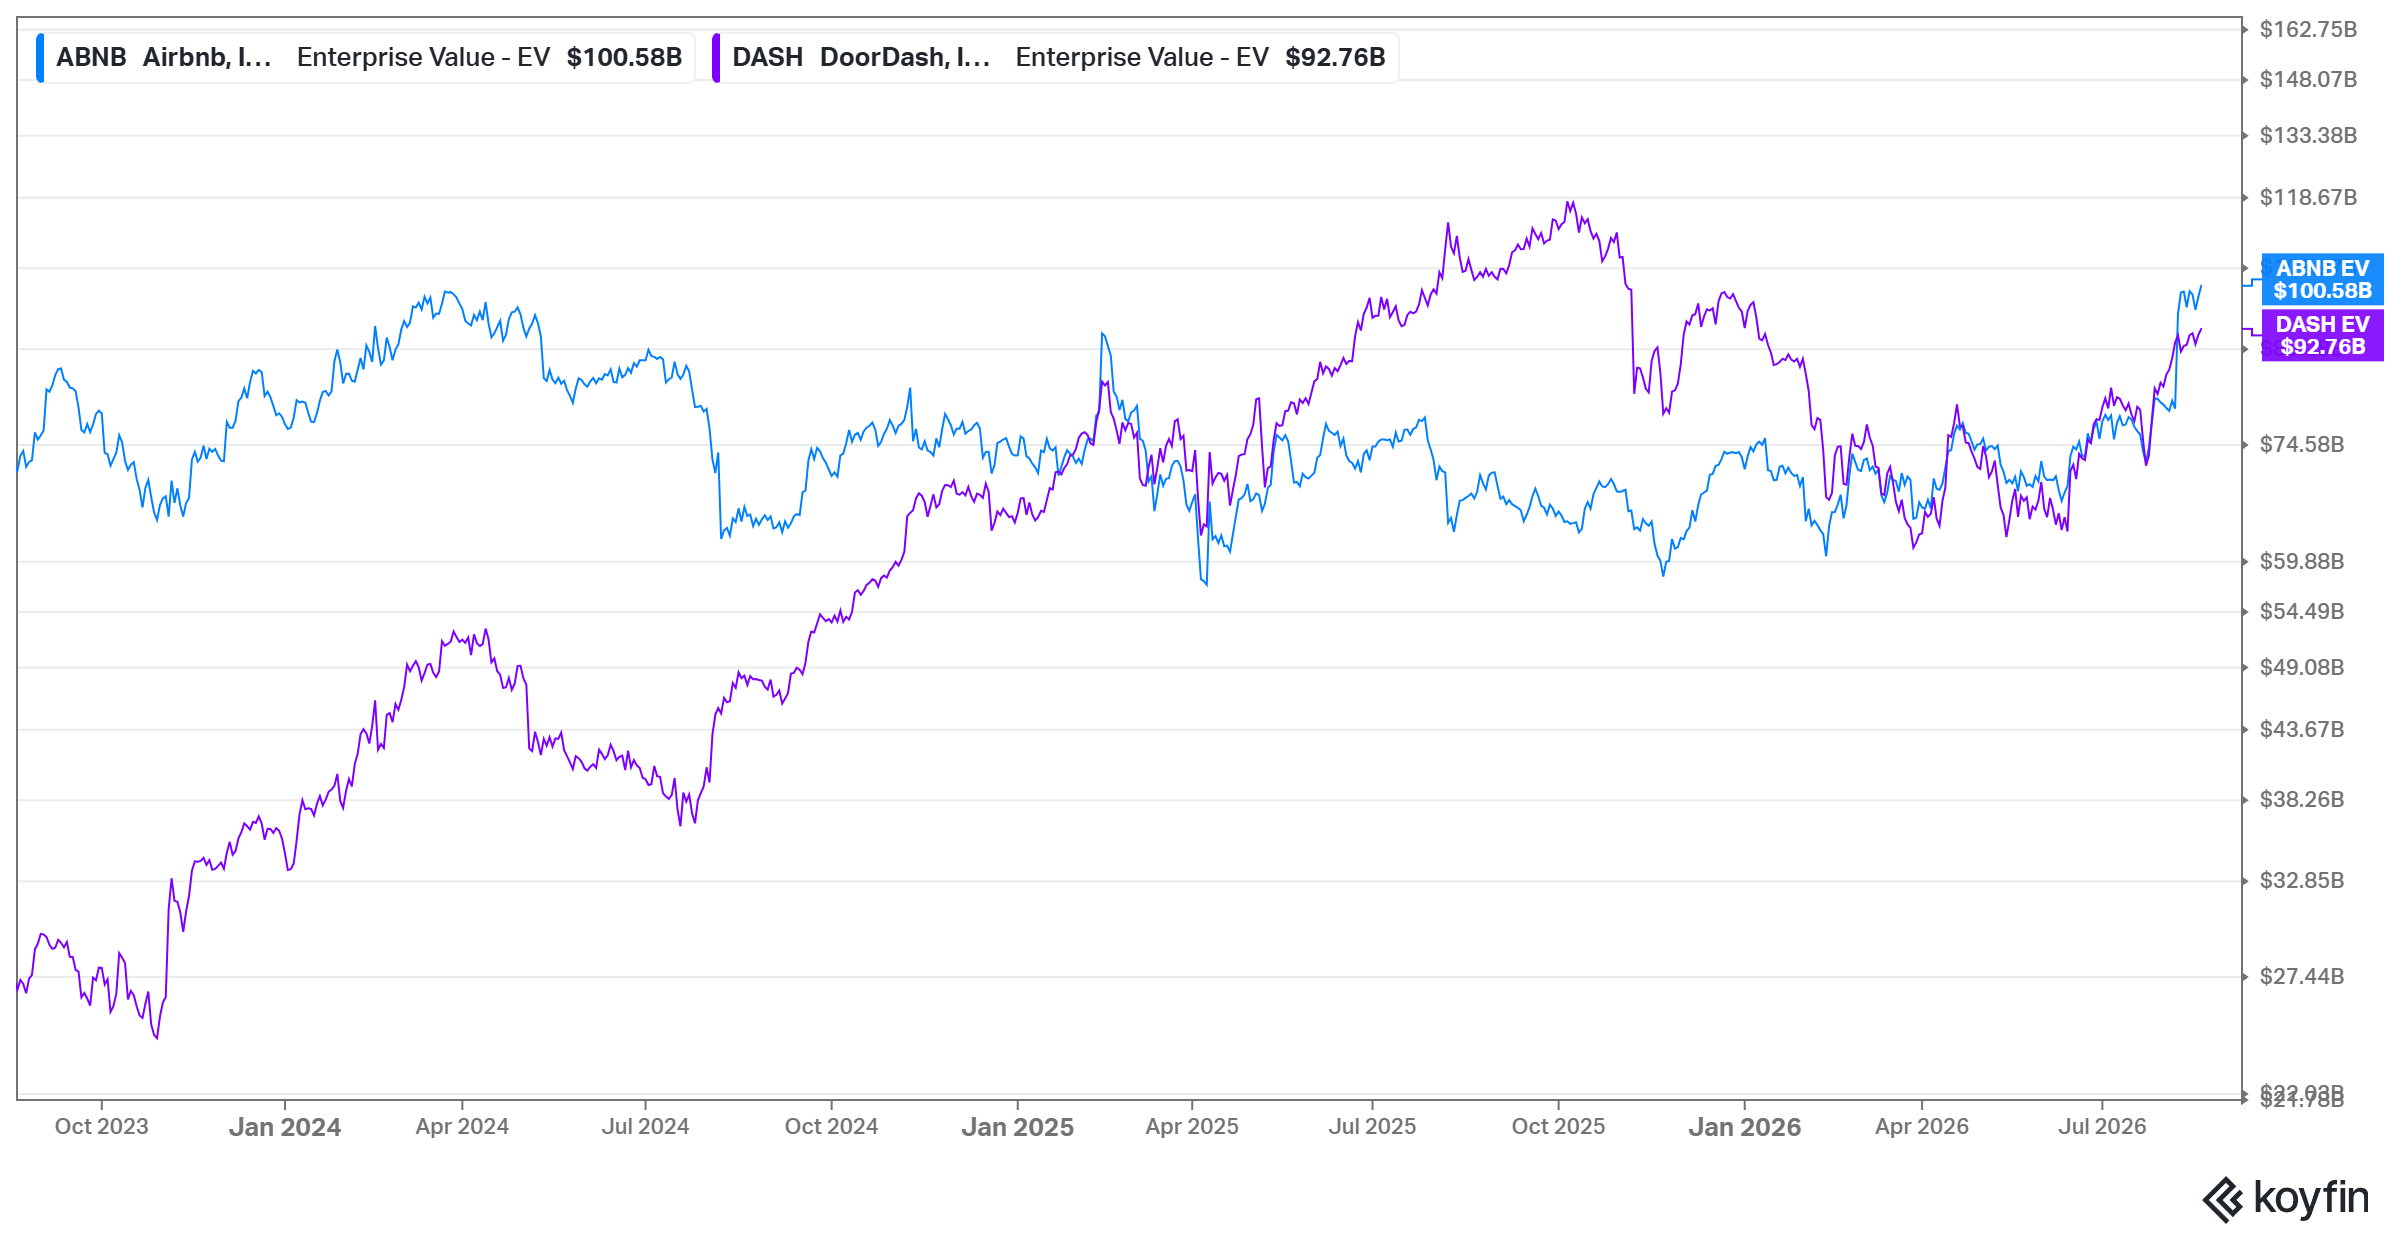
DoorDash holds roughly 60% U.S. market share in on-demand restaurant logistics, underpinning a long thesis on its defensible delivery…
RDDT 2026-08-19 Reddit joins the S&P 500 on August 18 after a short-term rally, while Q2 revenue growth came from ad pricing rather than user expansion and…
 Dilantha De Silva
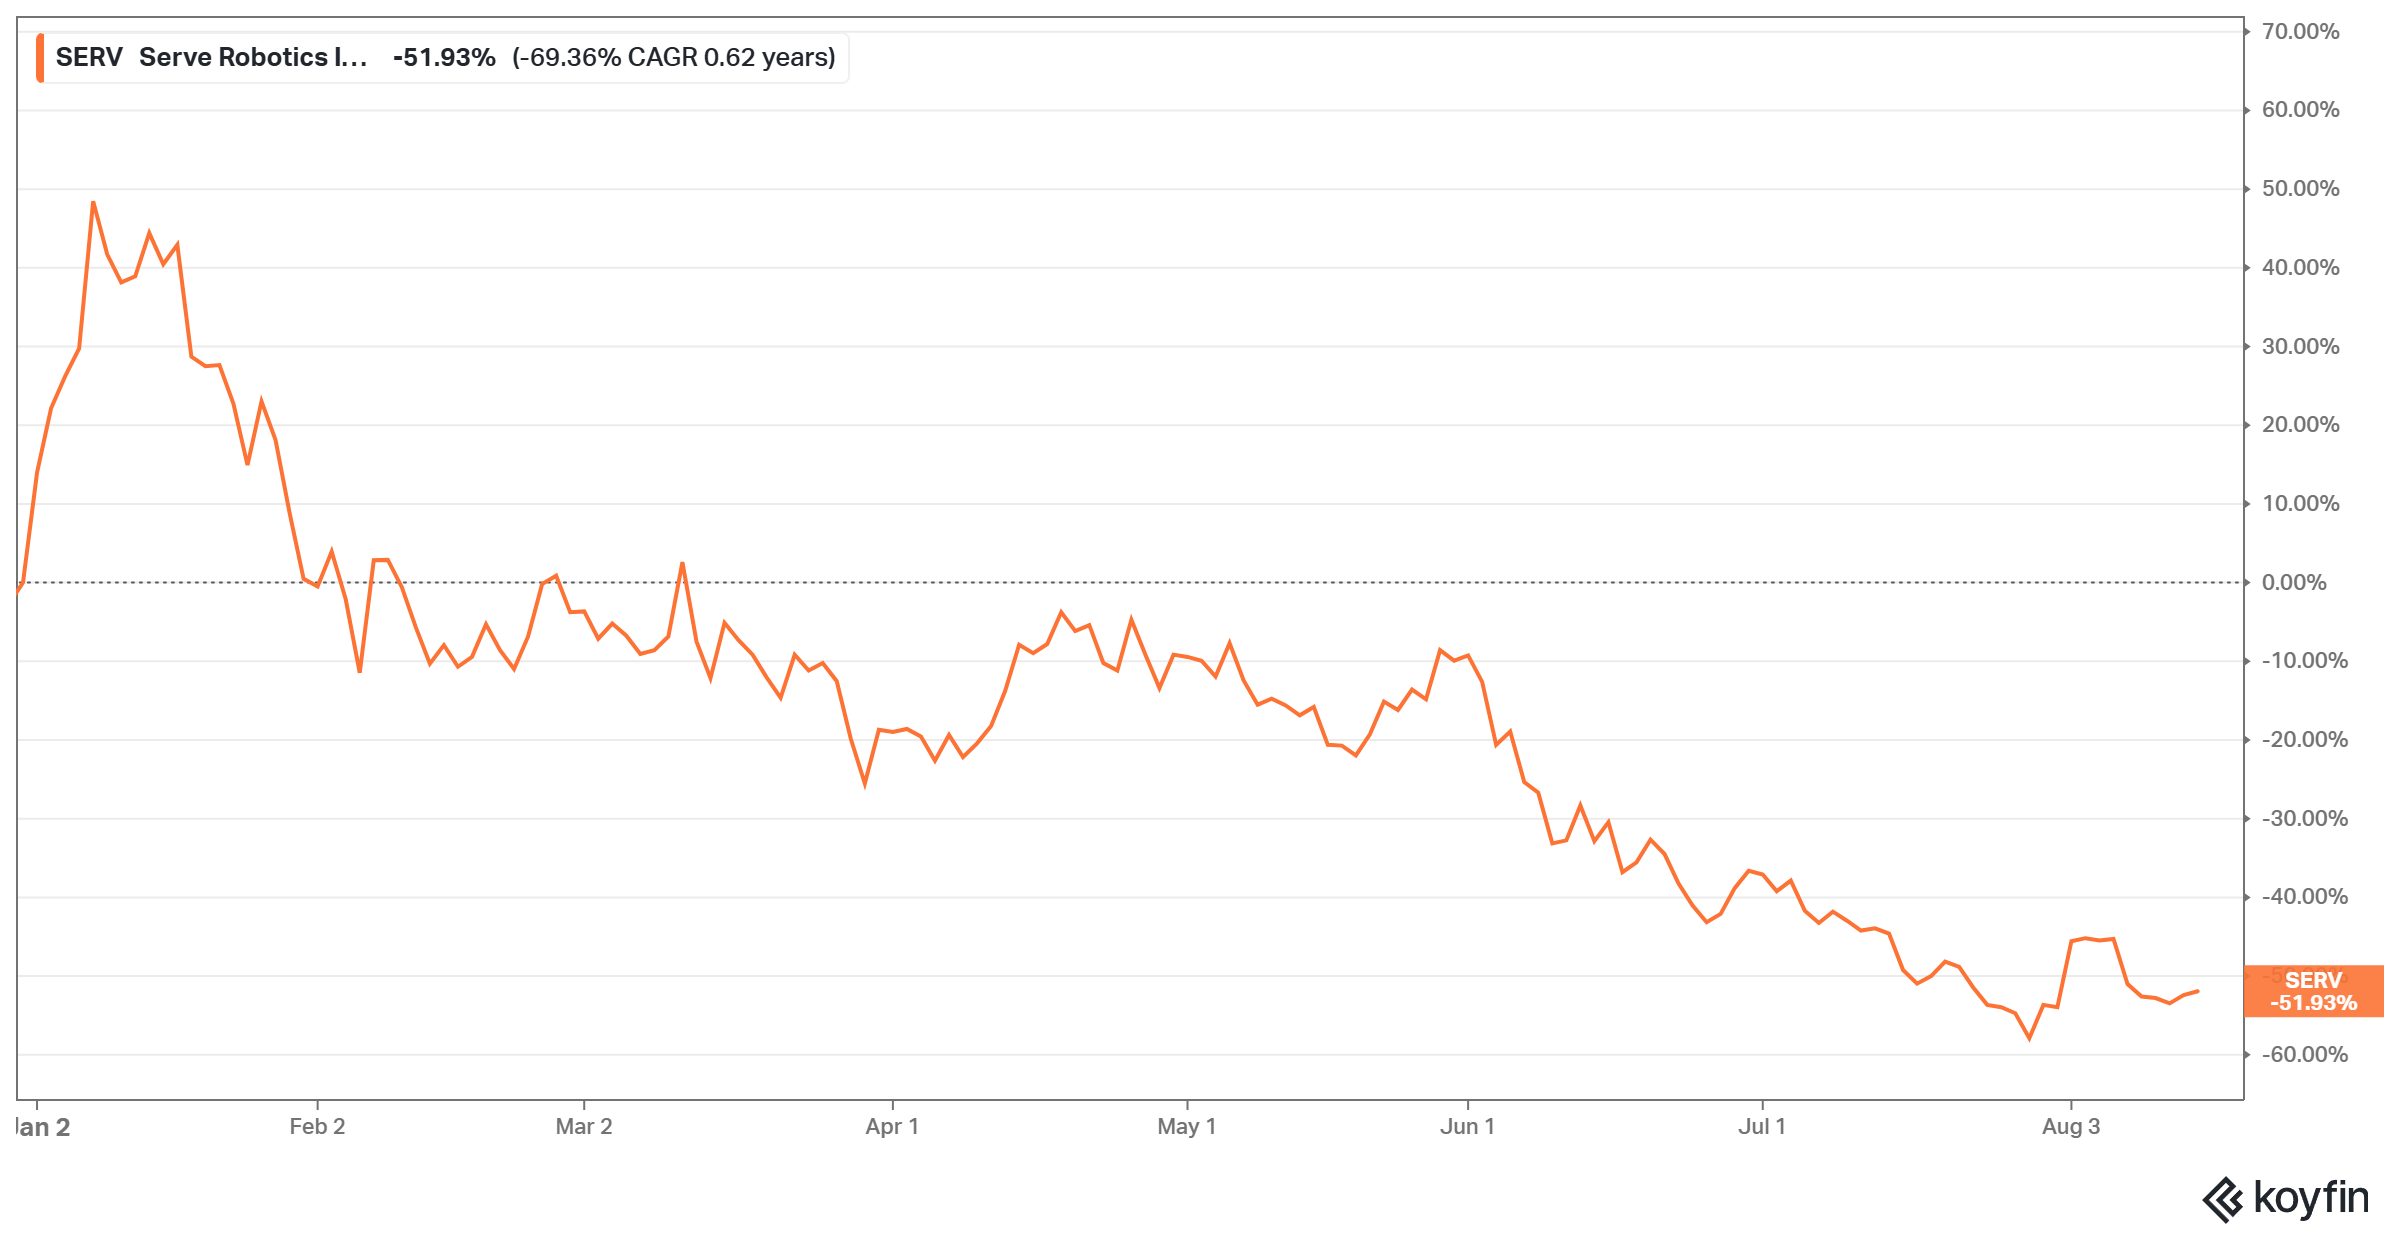
DoorDash’s integrated autonomous-delivery strategy contrasts with Uber’s 2026 divestment of Serve Robotics, its former delivery-robot…

CoreWeave and Nebius cite AI compute shortages and higher-priced GPU renewals, but older-chip utilization and depreciation vary across…
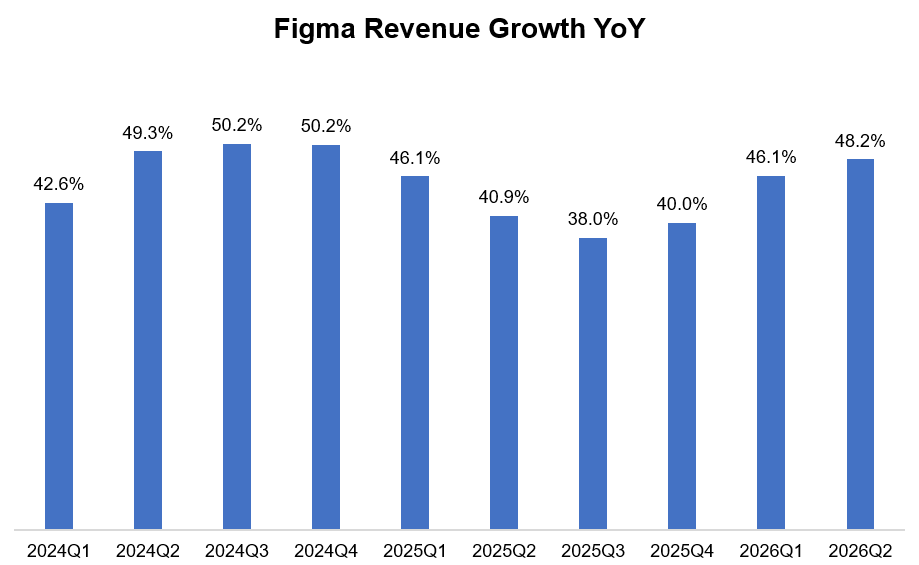
Figma raised its 2026 revenue growth guide to 39%, but a roughly 1% sequential 3Q outlook and unchanged $125-135 million operating-income…
Adobe generates 96% of revenue from subscriptions and converts over 40% into free cash flow, but generative AI tests whether Creative…
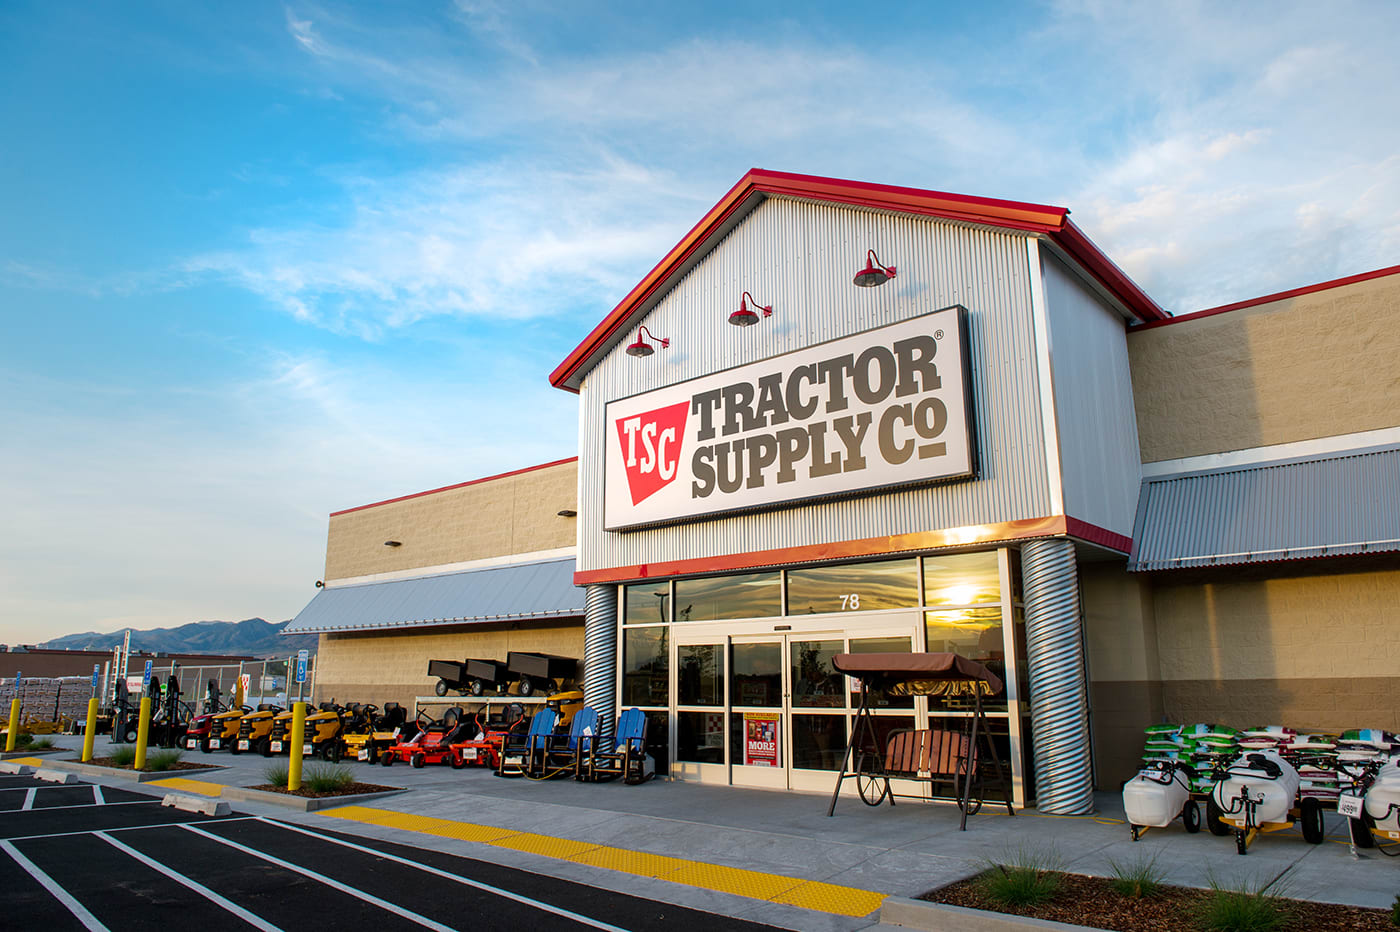
Tractor Supply’s 2,602-store rural retail network supported 30+ years of growth.
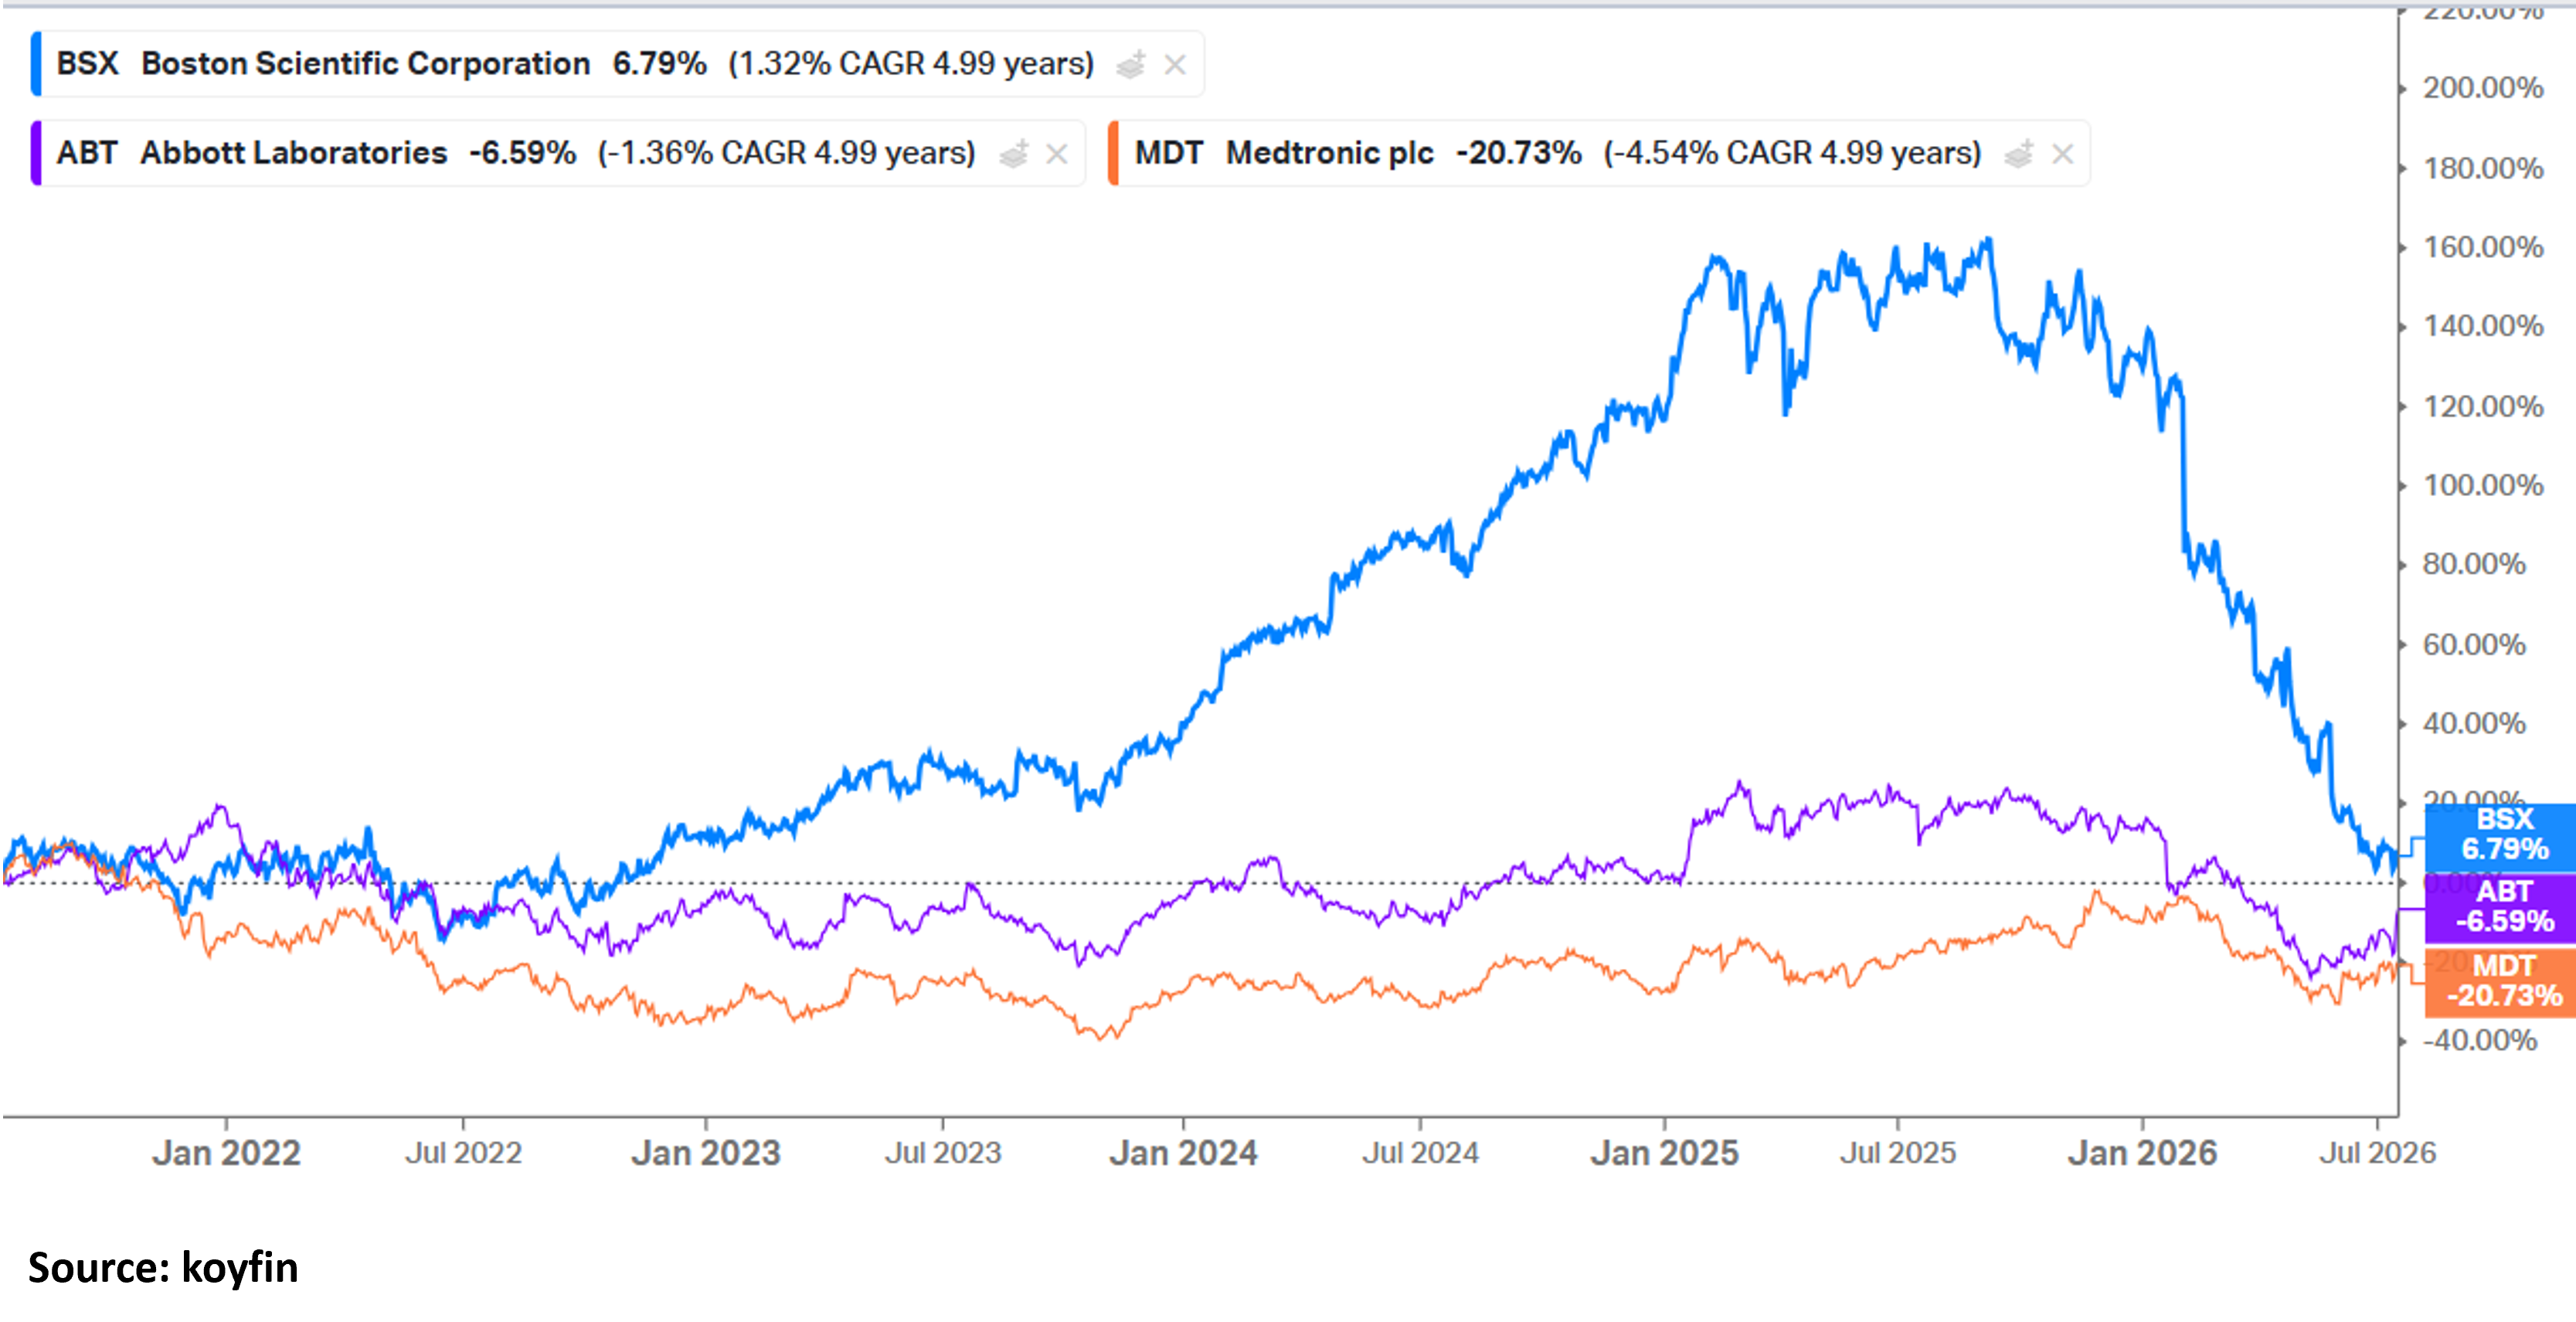
Boston Scientific built its interventional-medicine portfolio through acquisitions, but early-2000s growth became heavily dependent on the…
Synopsys and Cadence retain EDA pricing power through entrenched design flows, foundry relationships and high switching costs; AI-driven…
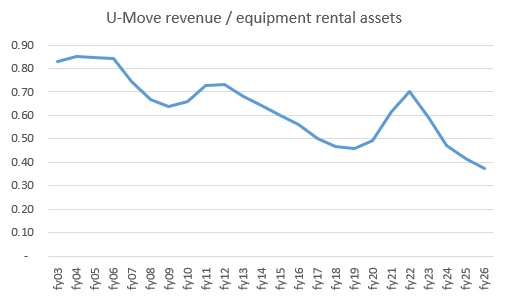
U-Haul’s pandemic-era fleet purchases at inflated prices now drive higher depreciation and disposal losses as truck and van prices…
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.