$DNOW: the boring distributor that could double on 2029 numbers | Firebird Management
DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.
DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.
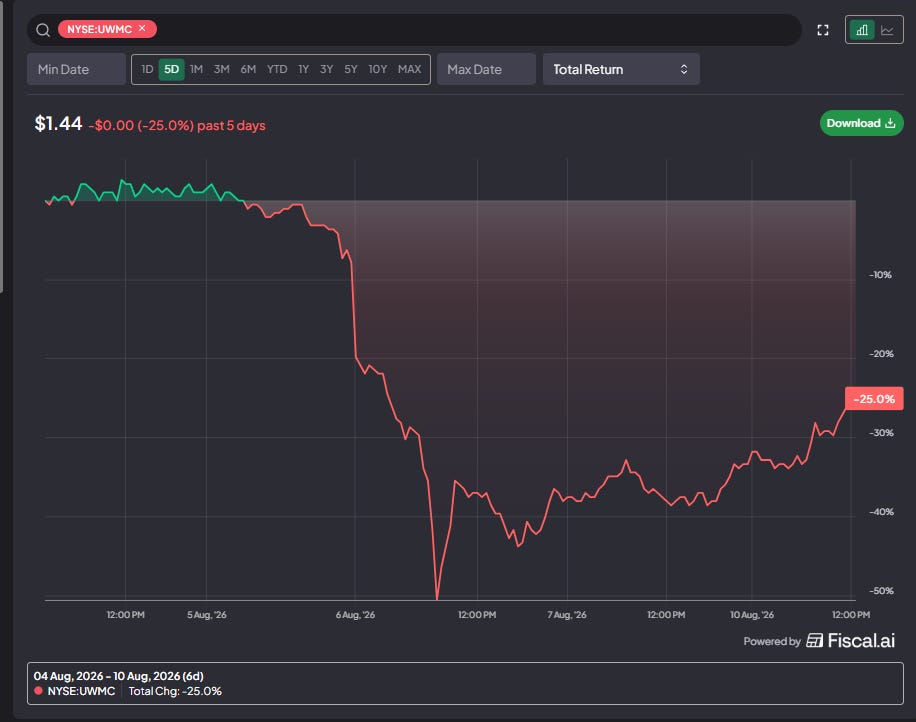
UWMC booked a roughly $600 million Q2 hedging loss tied to TWO months after the deal collapsed, contributing to an expensive capital raise.
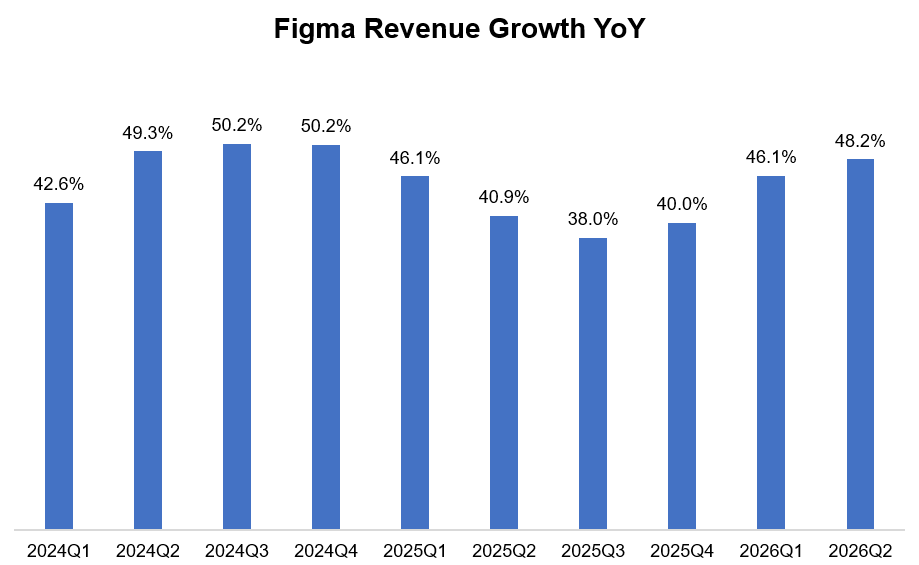
Figma raised its 2026 revenue growth guide to 39%, but a roughly 1% sequential 3Q outlook and unchanged $125-135 million operating-income…

Navient trades near 40% of tangible book as Gator Financial Partners argues private student-loan growth and restructuring can reverse its…

Hims & Hers investor Paul Cerro is long again on lab and patient data driving retention and LTV, despite management concerns, GLP-1…

Butler National Corporation is the subject of a stock pitch presented at the MS Microcaps Summer Virtual Conference.
Diversified Energy cut $233 million of debt in 1H26, repurchased $93 million of stock and sold $273 million of land and assets while…

Perimeter Solutions’ 2Q26 revenue rose 31%, while operating income fell 11% as USDA pricing and DLA delivery timing hurt Fire Safety; it…

Floor & Decor’s same-store sales improved to minus 2%, while $45 million of tariff refunds lifted second-quarter gross profit and operating…
Builders FirstSource reported Q2 2026 sales down 9% to $3.9 billion as weak housing demand and aggressive competitor pricing cut EBITDA…

Floor & Decor held 2026 guidance after a 2Q beat, with comps improving through June; tariff refunds lifted margins and may fund pricing…
 TDC · short
Teradata is a short as its on-premises analytics business declines while enterprises shift workloads to cloud-native platforms.

Vistance Networks plans a large post-Ruckus-sale dividend, leaving Aurora Networks valued below 4x guided EBITDA after $1.88 billion of…
OTC Markets gives smaller, distressed, and lightly disclosed companies a trading venue outside NYSE and Nasdaq, with lower listing barriers…

A debt-free American manufacturer now trades at roughly 7x annualized Q2 EBITDA, with $7.35 per share in net cash and a tender floor 18.5%…
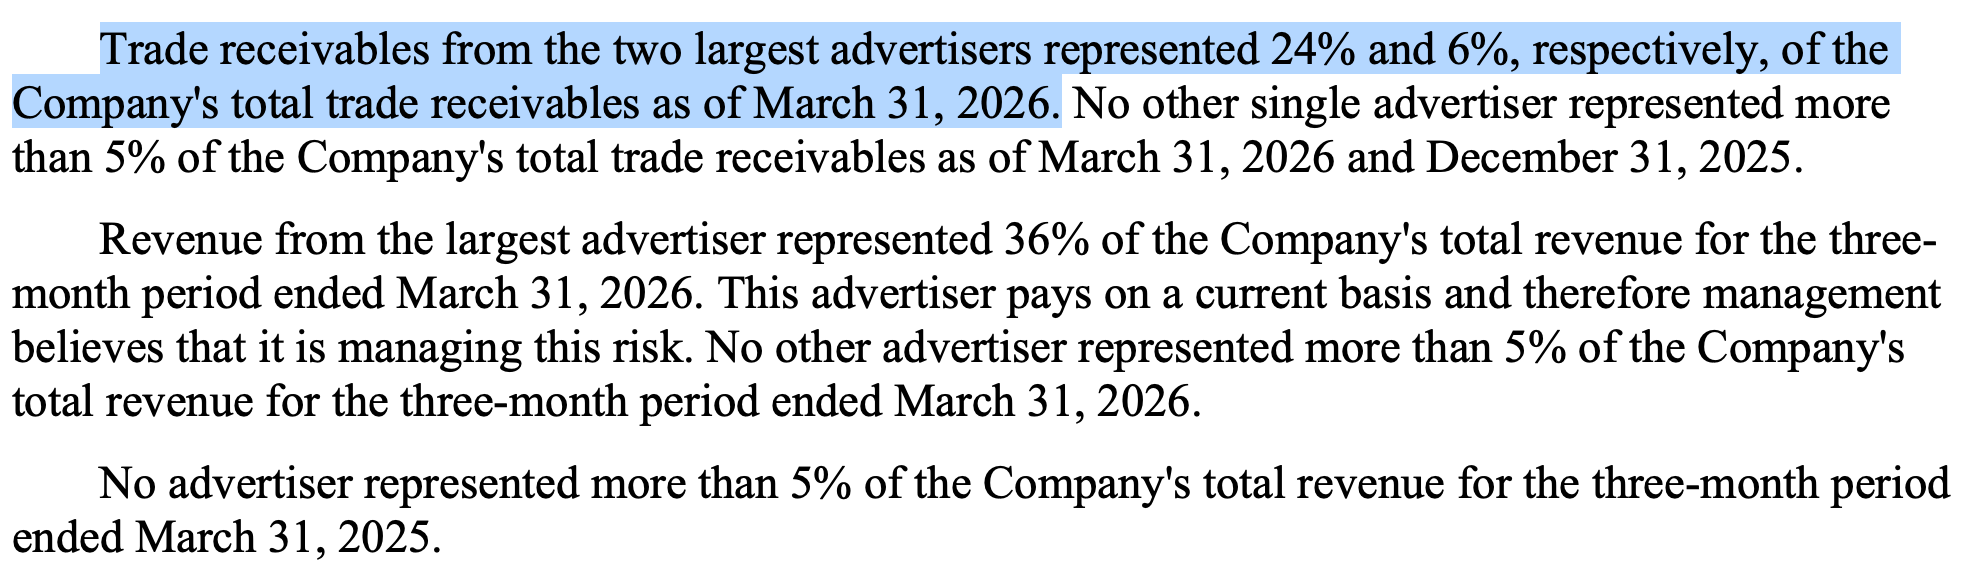
Entravision’s Q1 filings contain a new footnote disclosure pointing to a potential second large advertiser beyond its Hong Kong customer,…

United Parks trades at 8x EBITDA with an 8%+ unlevered cash yield, aggressive buybacks and roughly 80% effective short interest, while…

Diversified Energy (DEC) has paid $21.84 per share in dividends since June 2017 and trades at $13.35 amid a bullish U.S.

CBIZ activist Ryan Bunn urges ending buybacks, issuing equity and resuming bolt-on acquisitions to delever after the $2.3 billion Marcum…

Stitch Fix’s rushed Freestyle pivot cannibalized its profitable Fix business, driving active clients below 3.4 million, quarterly revenue…

Sprouts Farmers Market’s 483-store fresh-food format combines dedicated distribution, curated assortments and long-built site selection,…
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Atlas Diary
 Bay Area Ideas
 Benjamin C. Barry
 Bernard Zambonin
 Blake Winiecki
 Capital Connoisseur
 Chetan Woodun
 Crimson And Gold Research
 Cypriot Invests
 Dane Bowler
 Daniel Bell
 Daniel Jones
 Daniel Schönberger
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Gary Gambino
 Geneva Investor
 Gil Rotstein
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Kevin Avroutskii
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Louis Gerard
 M&M Capital
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Nicolas Bolsinger
 Oakoff Investments
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Sanjay Swamy
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 Terry Chrisomalis
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Yiannis Zourmpanos
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.