Monte Investments Market Brief Vol. CXXXVI
Monte Investments rotated Nvidia into Alphabet before earnings and reviews Knife River’s margin squeeze, AMD’s World Labs acquisition, and Diamondback’s $5 billion Permian deal.
Monte Investments rotated Nvidia into Alphabet before earnings and reviews Knife River’s margin squeeze, AMD’s World Labs acquisition, and Diamondback’s $5 billion Permian deal.

$NUAI - Trade the Pop, Then Short the Raise They just posted an S-3 resale last night suggesting insiders are poised to sell shares if there is a pop in the stock.

What are the top 10 activist situations globally right now? A few that come to mind: $MTN, $VOYA, $BYG.LN.

@ACapitalLP $STGW $CODI
Ondas reported $167.5 million in Q3 revenue but spent $562 million of cash, halved gross margin and fell below its $6 stop level.
Offshore Radar maps 160-plus listed offshore rigs, contracts, day rates and uncontracted capacity through 2029.
Travere Therapeutics' FILSPARI has two FDA approvals and is driving revenue growth, while TVTX shares have nearly tripled since August 2025.
 Out of Ignorance 3 clicks
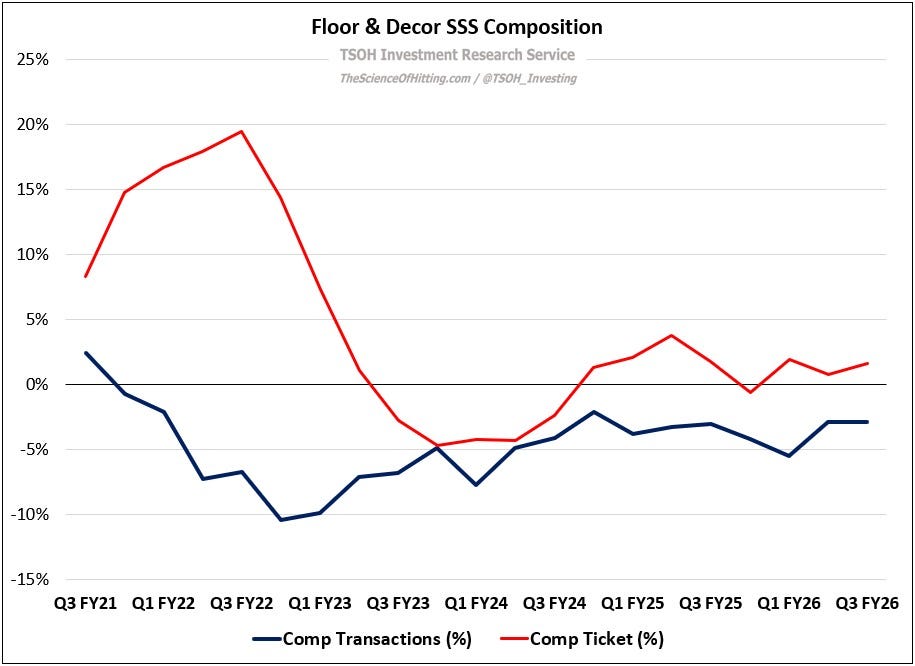
Floor & Decor has logged 20 straight quarters of comp transaction declines, with Q3 quarter-to-date same-store sales down about 3.8% as…
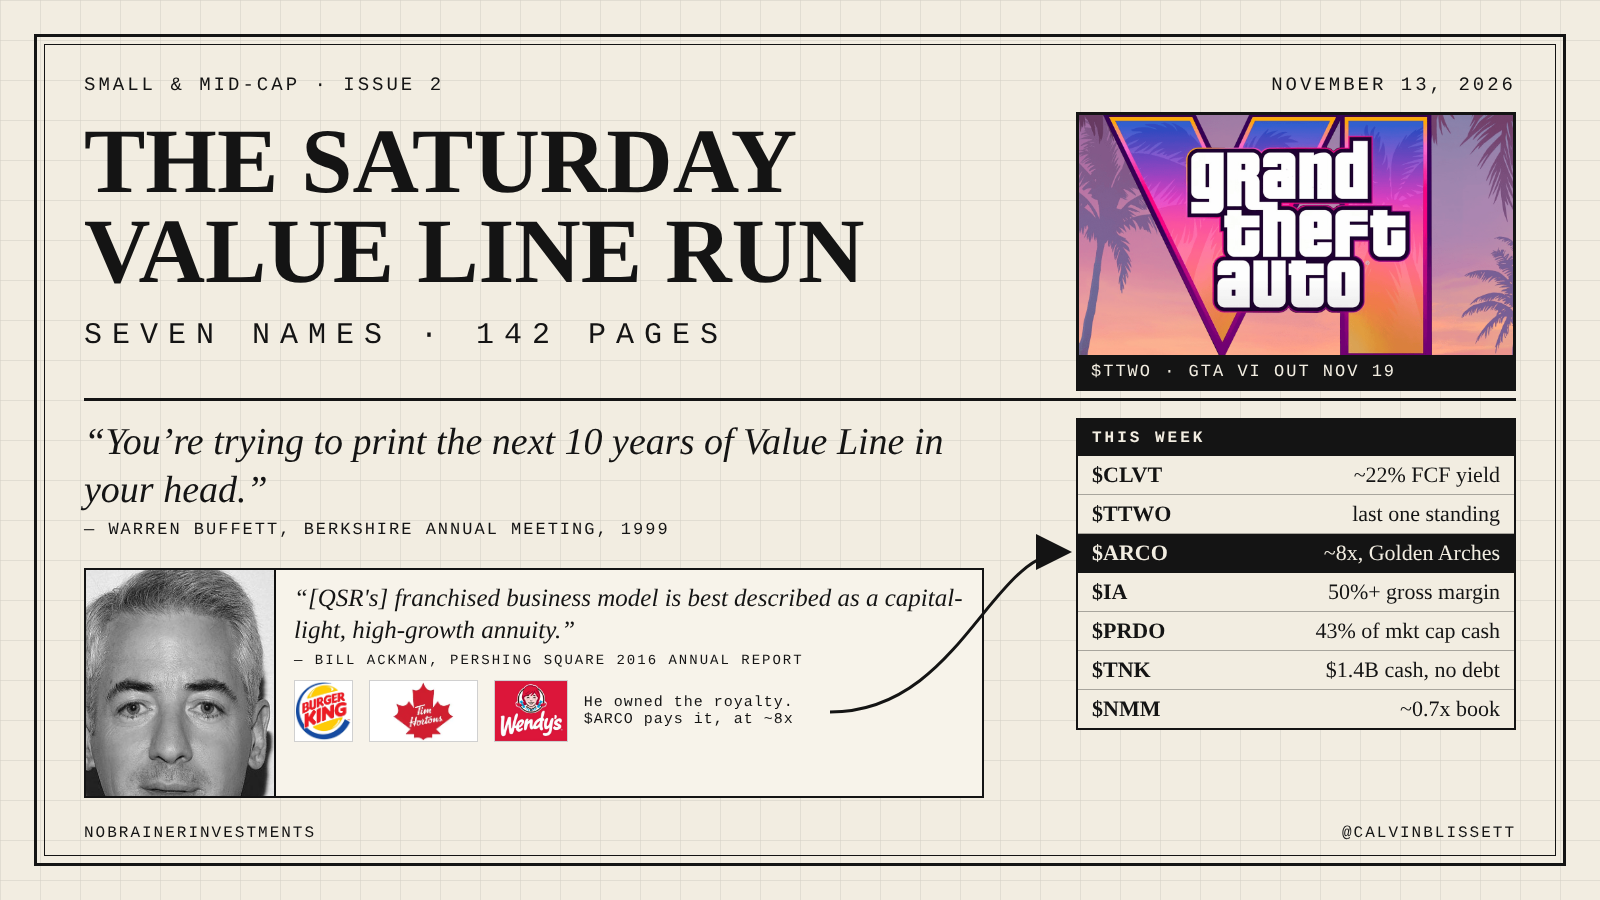
Clarivate, Take-Two and Arcos Dorados lead a seven-stock Value Line screen focused on debt paydown, GTA VI economics and Latin American…
Hyster-Yale remains under pressure as Americas revenue fell to $608.6 million from $732.7 million, while $100 million of planned cost…
 Daniel Jones

OTC Markets CEO Cromwell Coulson says the SEC’s proposed offering reforms could let OTCQX and OTCQB companies raise capital through…
Q3 updates cover Crocs, Entravision and Fiserv beats, coal and oil weakness, and Xerox’s sharp decline, testing the underlying cases for…
Sigma Lithium’s production disruptions, negative EBITDA and underutilized plant costs undermine its expansion case despite refinancing.
 CAN Analyst
 GLIBA · long
Liberty Capital Corp, GLIBA, is pitched long following its July 2025 spinoff from Liberty Broadband.
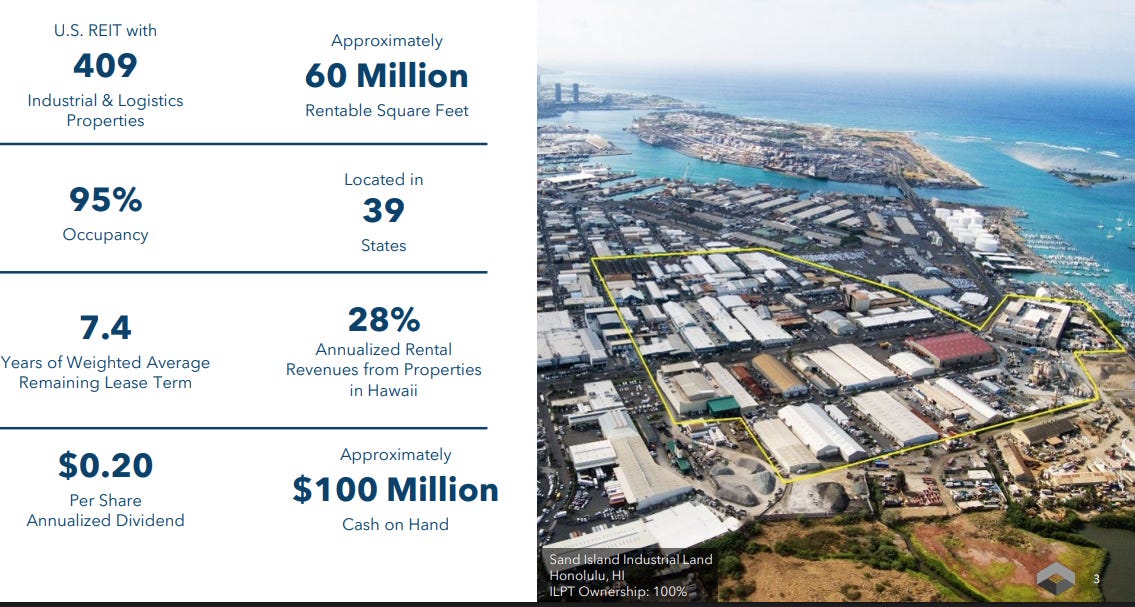
ILPT’s Hawaii ground leases and US warehouse portfolio are improving, while five-year fixed-rate refinancing eases the debt burden created…
Element Solutions sells consumable chipmaking chemistry, with a $75 target from $44 based on an AI-driven semiconductor-materials rerating.
Sureste Airports’ 20-airport Motiva acquisition and U.S. concessions are set to lift EBITDA, while shares trade at 7x forward EBITDA.

A software powerhouse posts a record quarter while trading at a 52-week low, raising a valuation disconnect between its business model and…
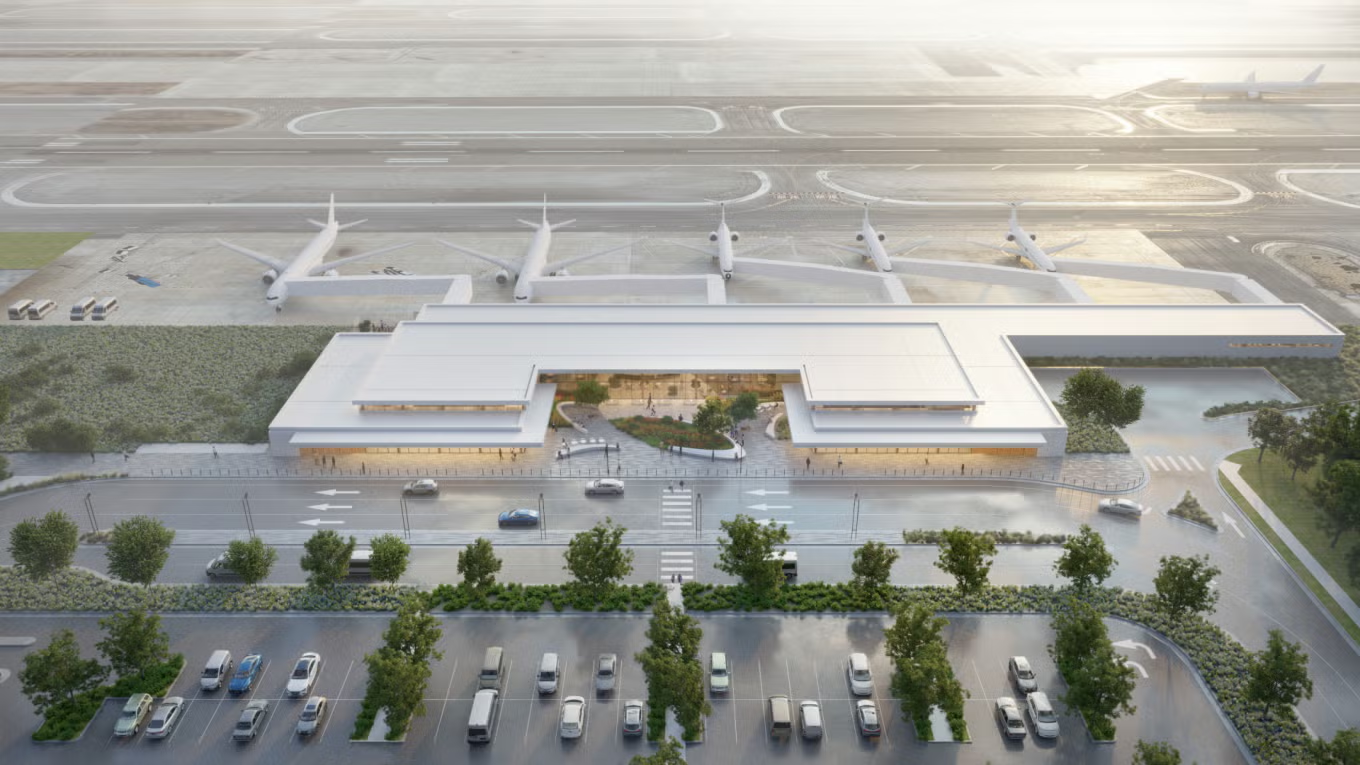
Grupo OMAB trades at 9 times EV/EBITDA after an 11% YTD decline, as Monterrey international traffic fell 2.9%; expansion, price hikes and…
Tenable’s $27 valuation reflects fears that AI commoditizes vulnerability scanning, while the thesis says AI increases demand for…

ADF Group’s Q1 FY2026 revenue rose 78% to $99.3 million and net income 37%, aided by the LAR acquisition despite steel and aluminum tariff…
Keiko Fujimori’s expected Peru victory and Abelardo’s win in Colombia reduce regulatory risk for AUNA, whose operations generate roughly…

MSGS, owner of the Knicks and Rangers, filed a Form 10 to explore a spinoff as comparable franchise sales support an $11 billion valuation.
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Atlas Diary
 Bay Area Ideas
 Benjamin C. Barry
 Bernard Zambonin
 Blake Winiecki
 Capital Connoisseur
 Chetan Woodun
 Crimson And Gold Research
 Cypriot Invests
 Dane Bowler
 Daniel Bell Daniel Jones
 Daniel Schönberger
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Gary Gambino
 Geneva Investor
 Gil Rotstein
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Kevin Avroutskii
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Louis Gerard
 M&M Capital
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Nicolas Bolsinger
 Oakoff Investments
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Sanjay Swamy
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 Terry Chrisomalis
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Yiannis Zourmpanos
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥 A Capital
 absreturnchaser Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.