BGIN: a $34mm tax bill and $31mm of cash
BGIN holds $31.4 million of cash against $34.1 million in taxes payable as first-half revenue fell 85% and self-mining costs exceeded coin output.
BGIN holds $31.4 million of cash against $34.1 million in taxes payable as first-half revenue fell 85% and self-mining costs exceeded coin output.

Also interesting given the increasing amount of M&A in the BDC sector…. See $ARCC / $MFIC today…

@CorpusCol Speaking of pretty smart- These were spot on. $MNSB $SOUB $NEWT et al

All gaps get closed. $MAMA
Coursera trades at roughly $150 million enterprise value after Pale Fire Capital took 14.7%, with cash and Treasuries covering 83% of its…
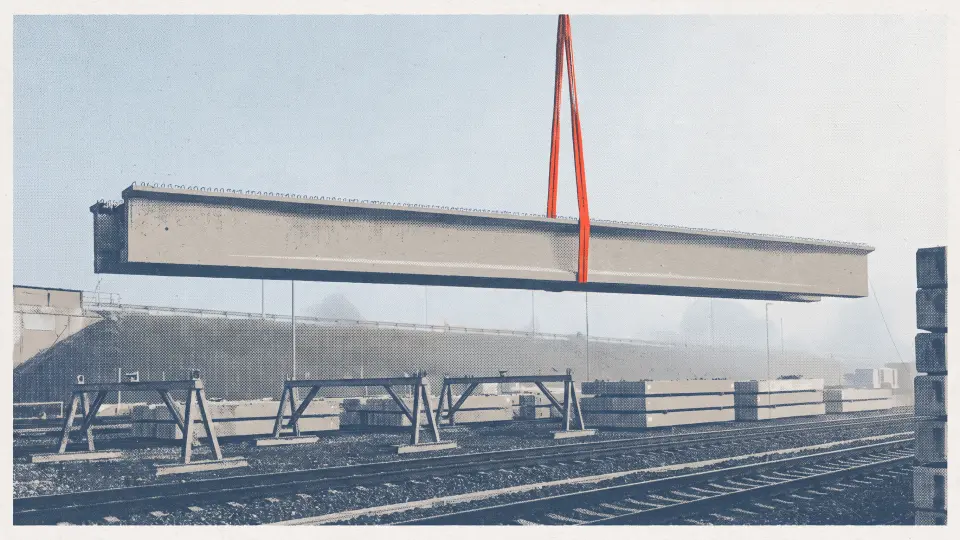
L.B. Foster's Q3 recovery reflects rail and infrastructure demand, government funding and precast concrete expansion, with operating…
 Value Capital Research
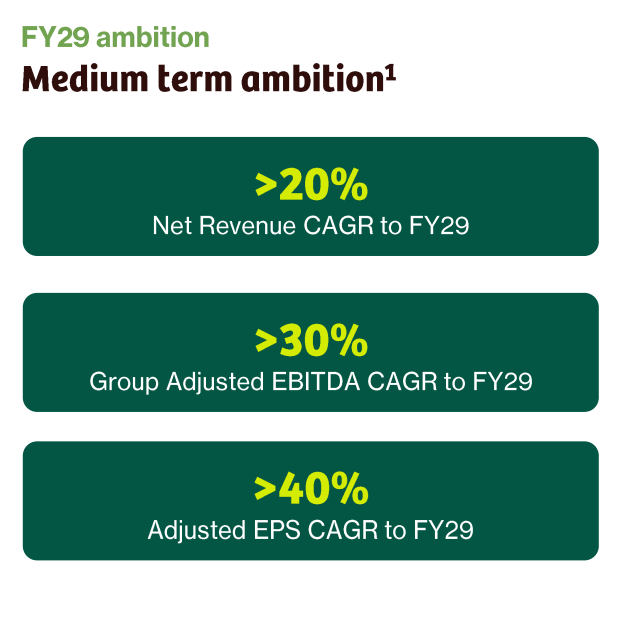
Lesaka expects its Bank Zero acquisition to close by end-January 2027, though it could still close this calendar year.
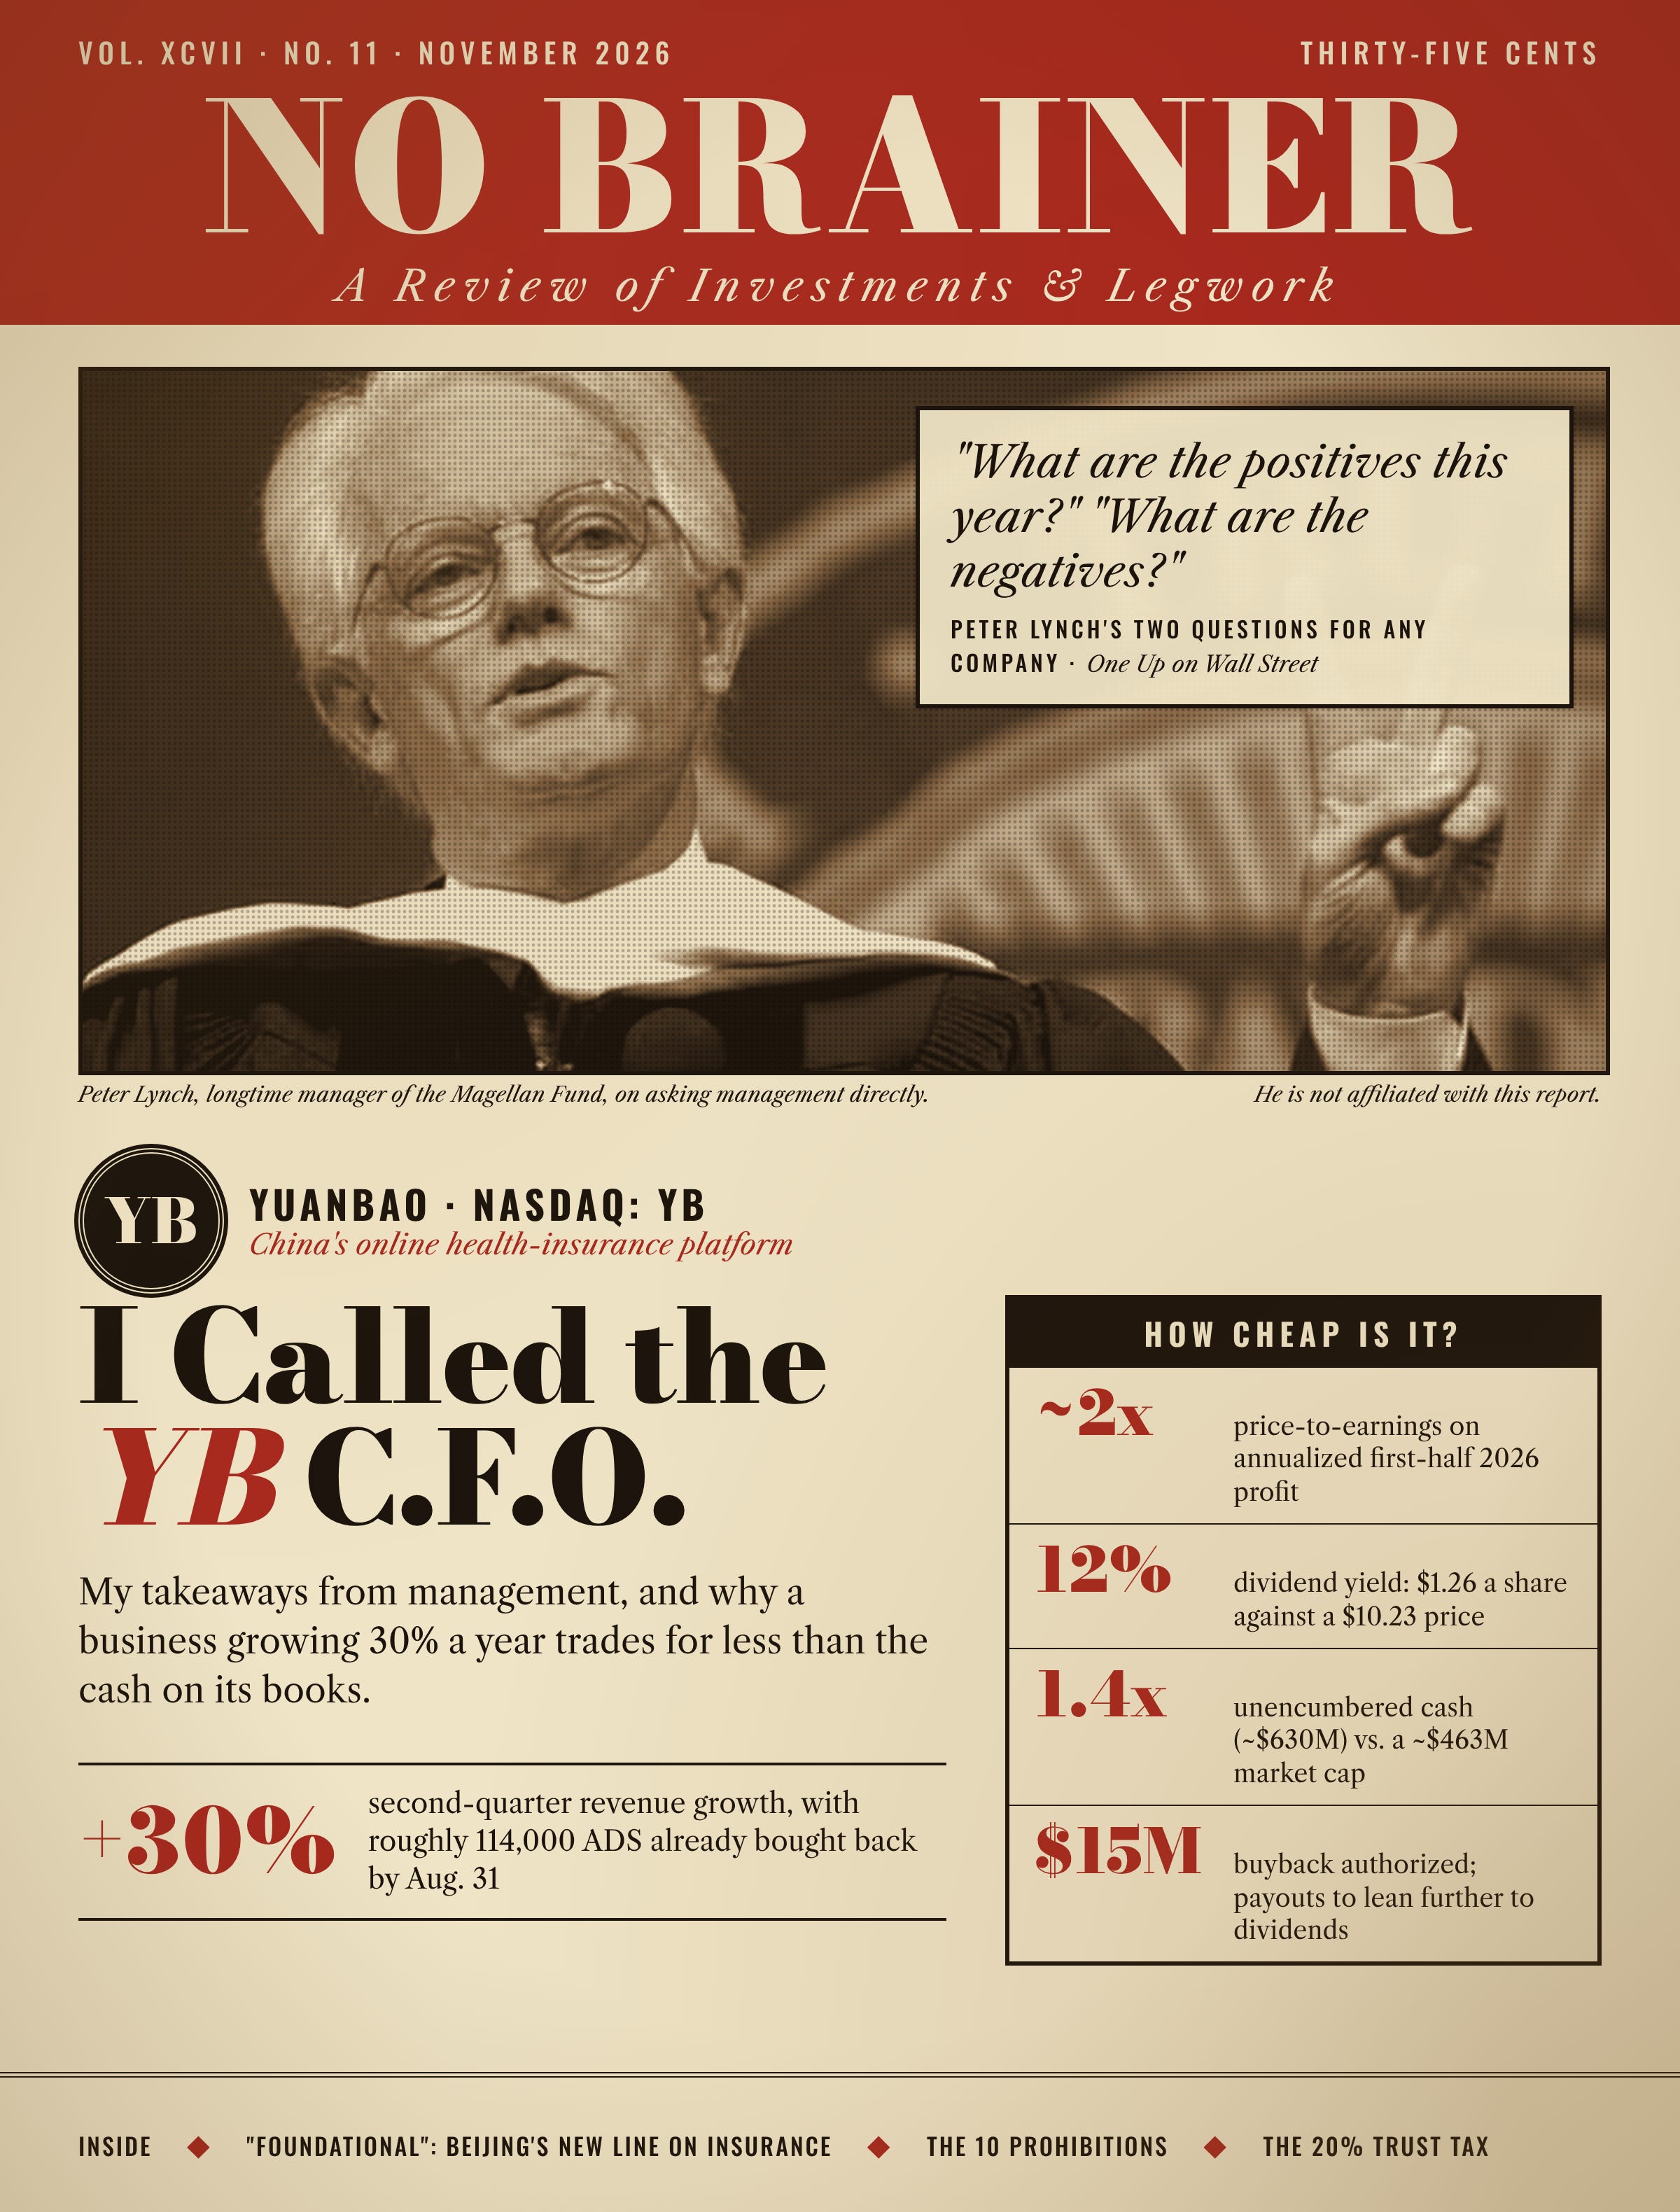
Yuanbao’s CFO says China’s new online-insurance rules target abusive sales practices, while Beijing increasingly frames commercial health…
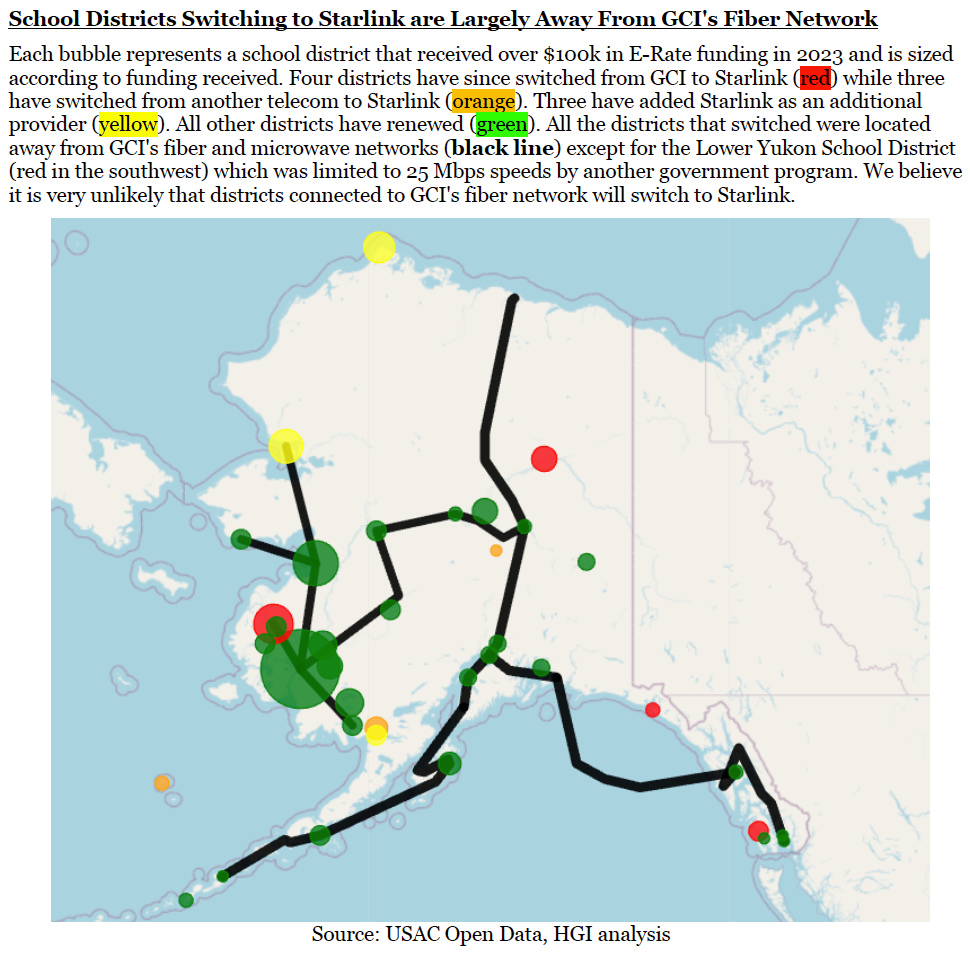
Liberty Capital’s GCI business grew 5% in high-margin healthcare and school contracts, while Quintillion could lift EBITDA to $440 million…
Cars.com is assessed through Buffett-style owner earnings, focusing on cash retained after maintenance capital spending rather than GAAP…
Quantum Corp. surged while Quantum Computing slumped again after their Tuesday reports.
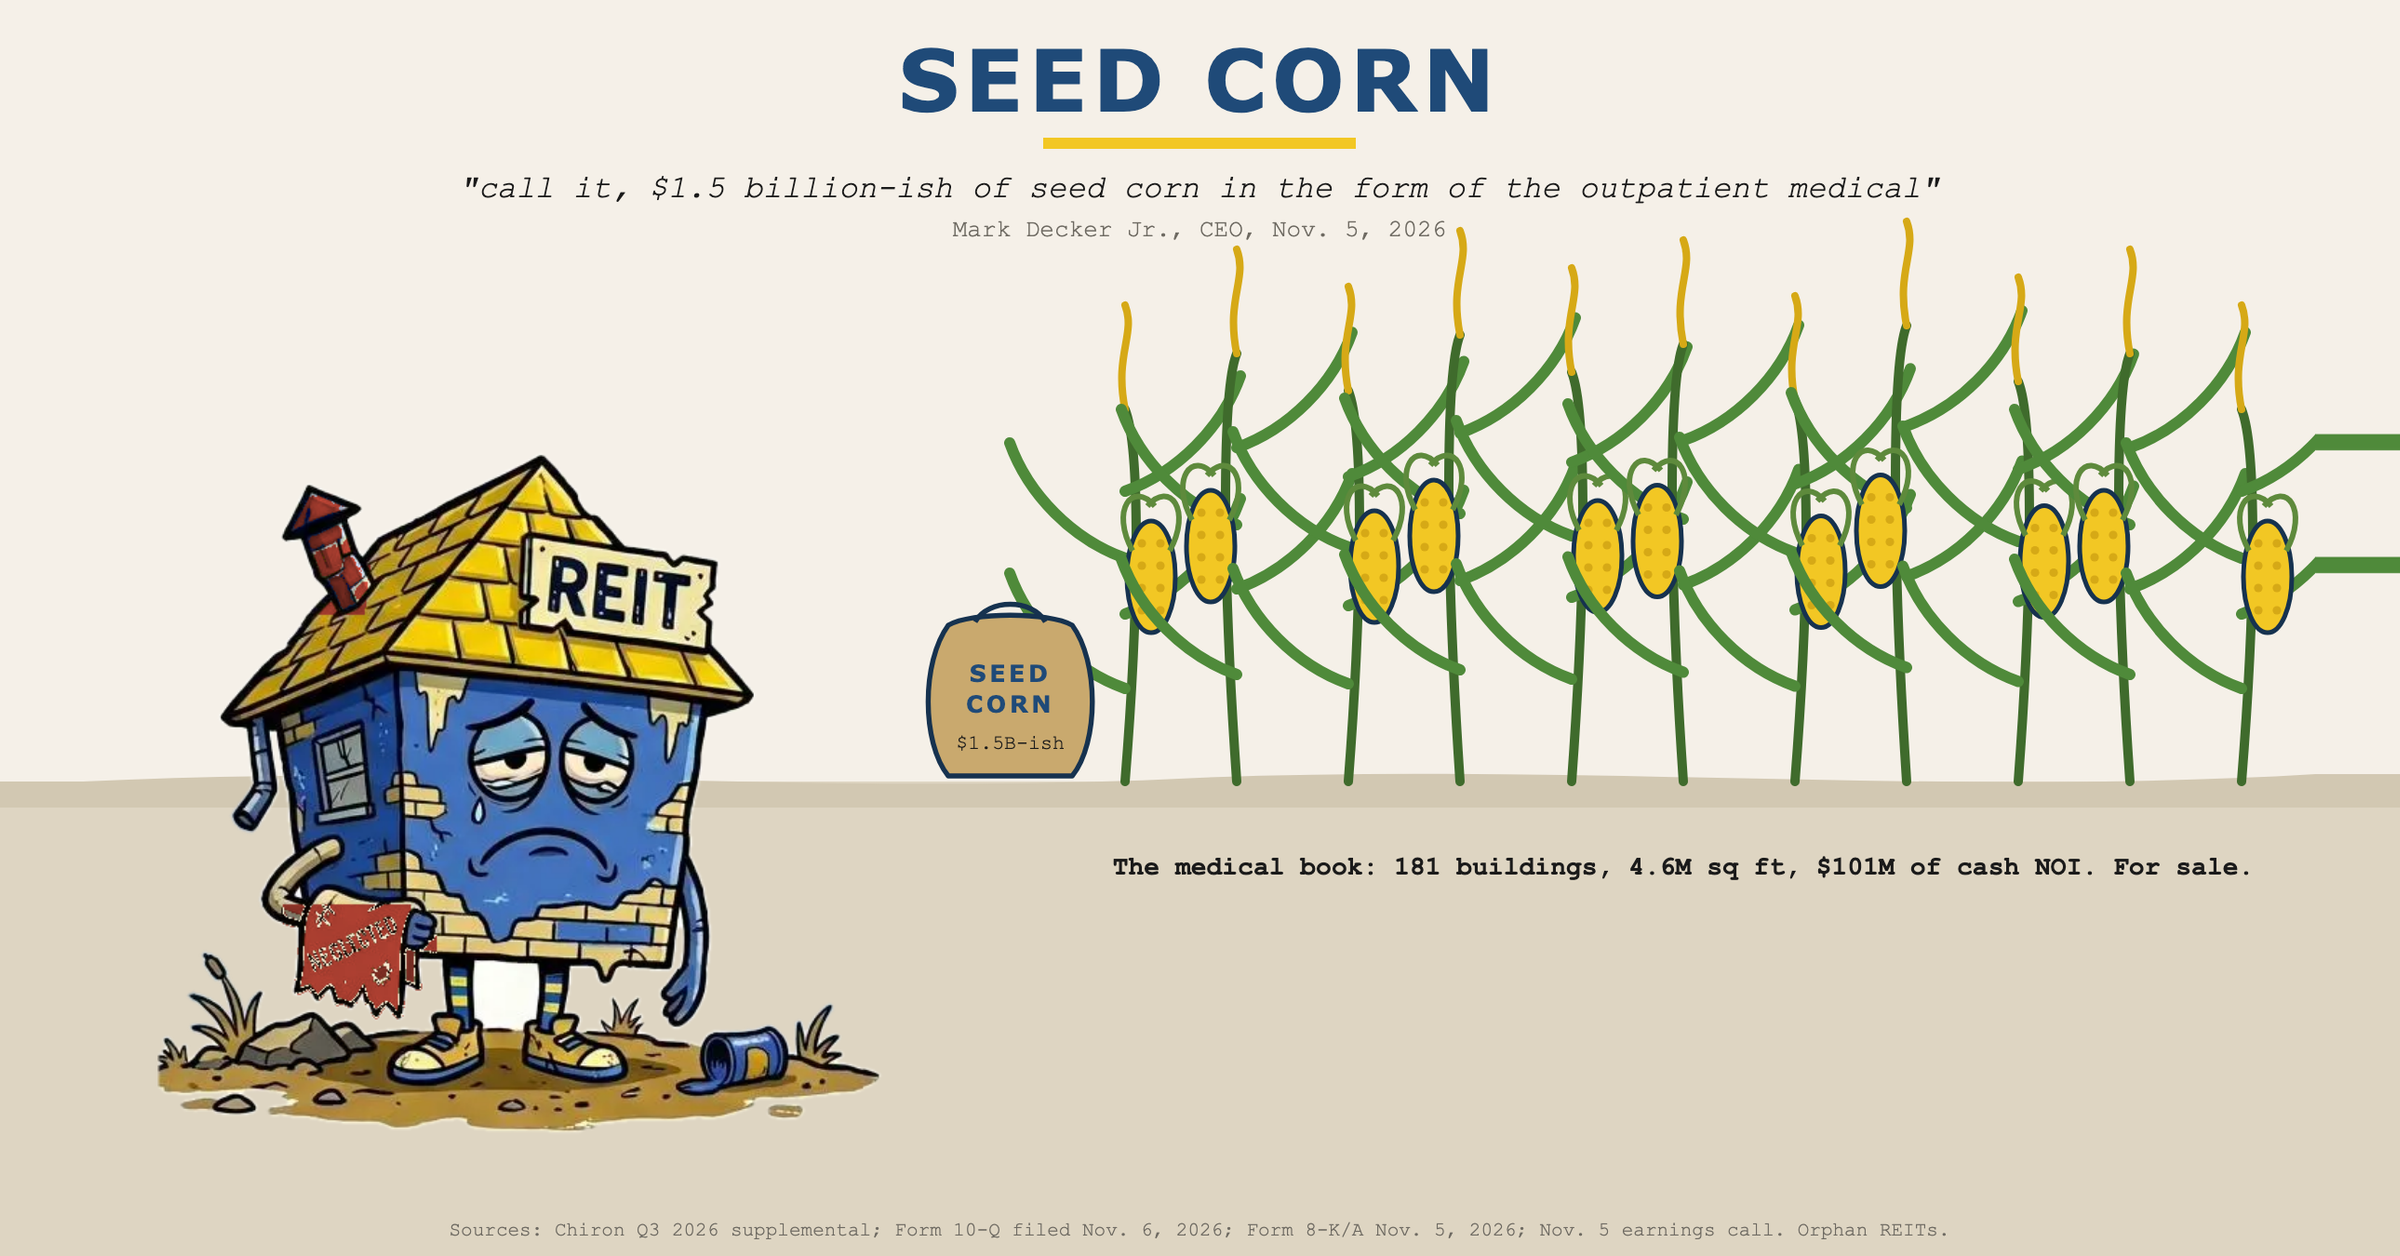
Chiron’s failed $49 million Beaumont sale and $178 million Pinnacle acquisition leave XRN with $70 million of liquidity and medical-office…
 Crimson And Gold Research 3 clicks
EVC's Q3 update cites $30 million for a single station, a broadcast-business sale and stronger positioning for 2027.
 NGVC · long
Natural Grocers (NGVC) returned to $27.80 after a prior long entry at $21 and exit recommendation at $46.
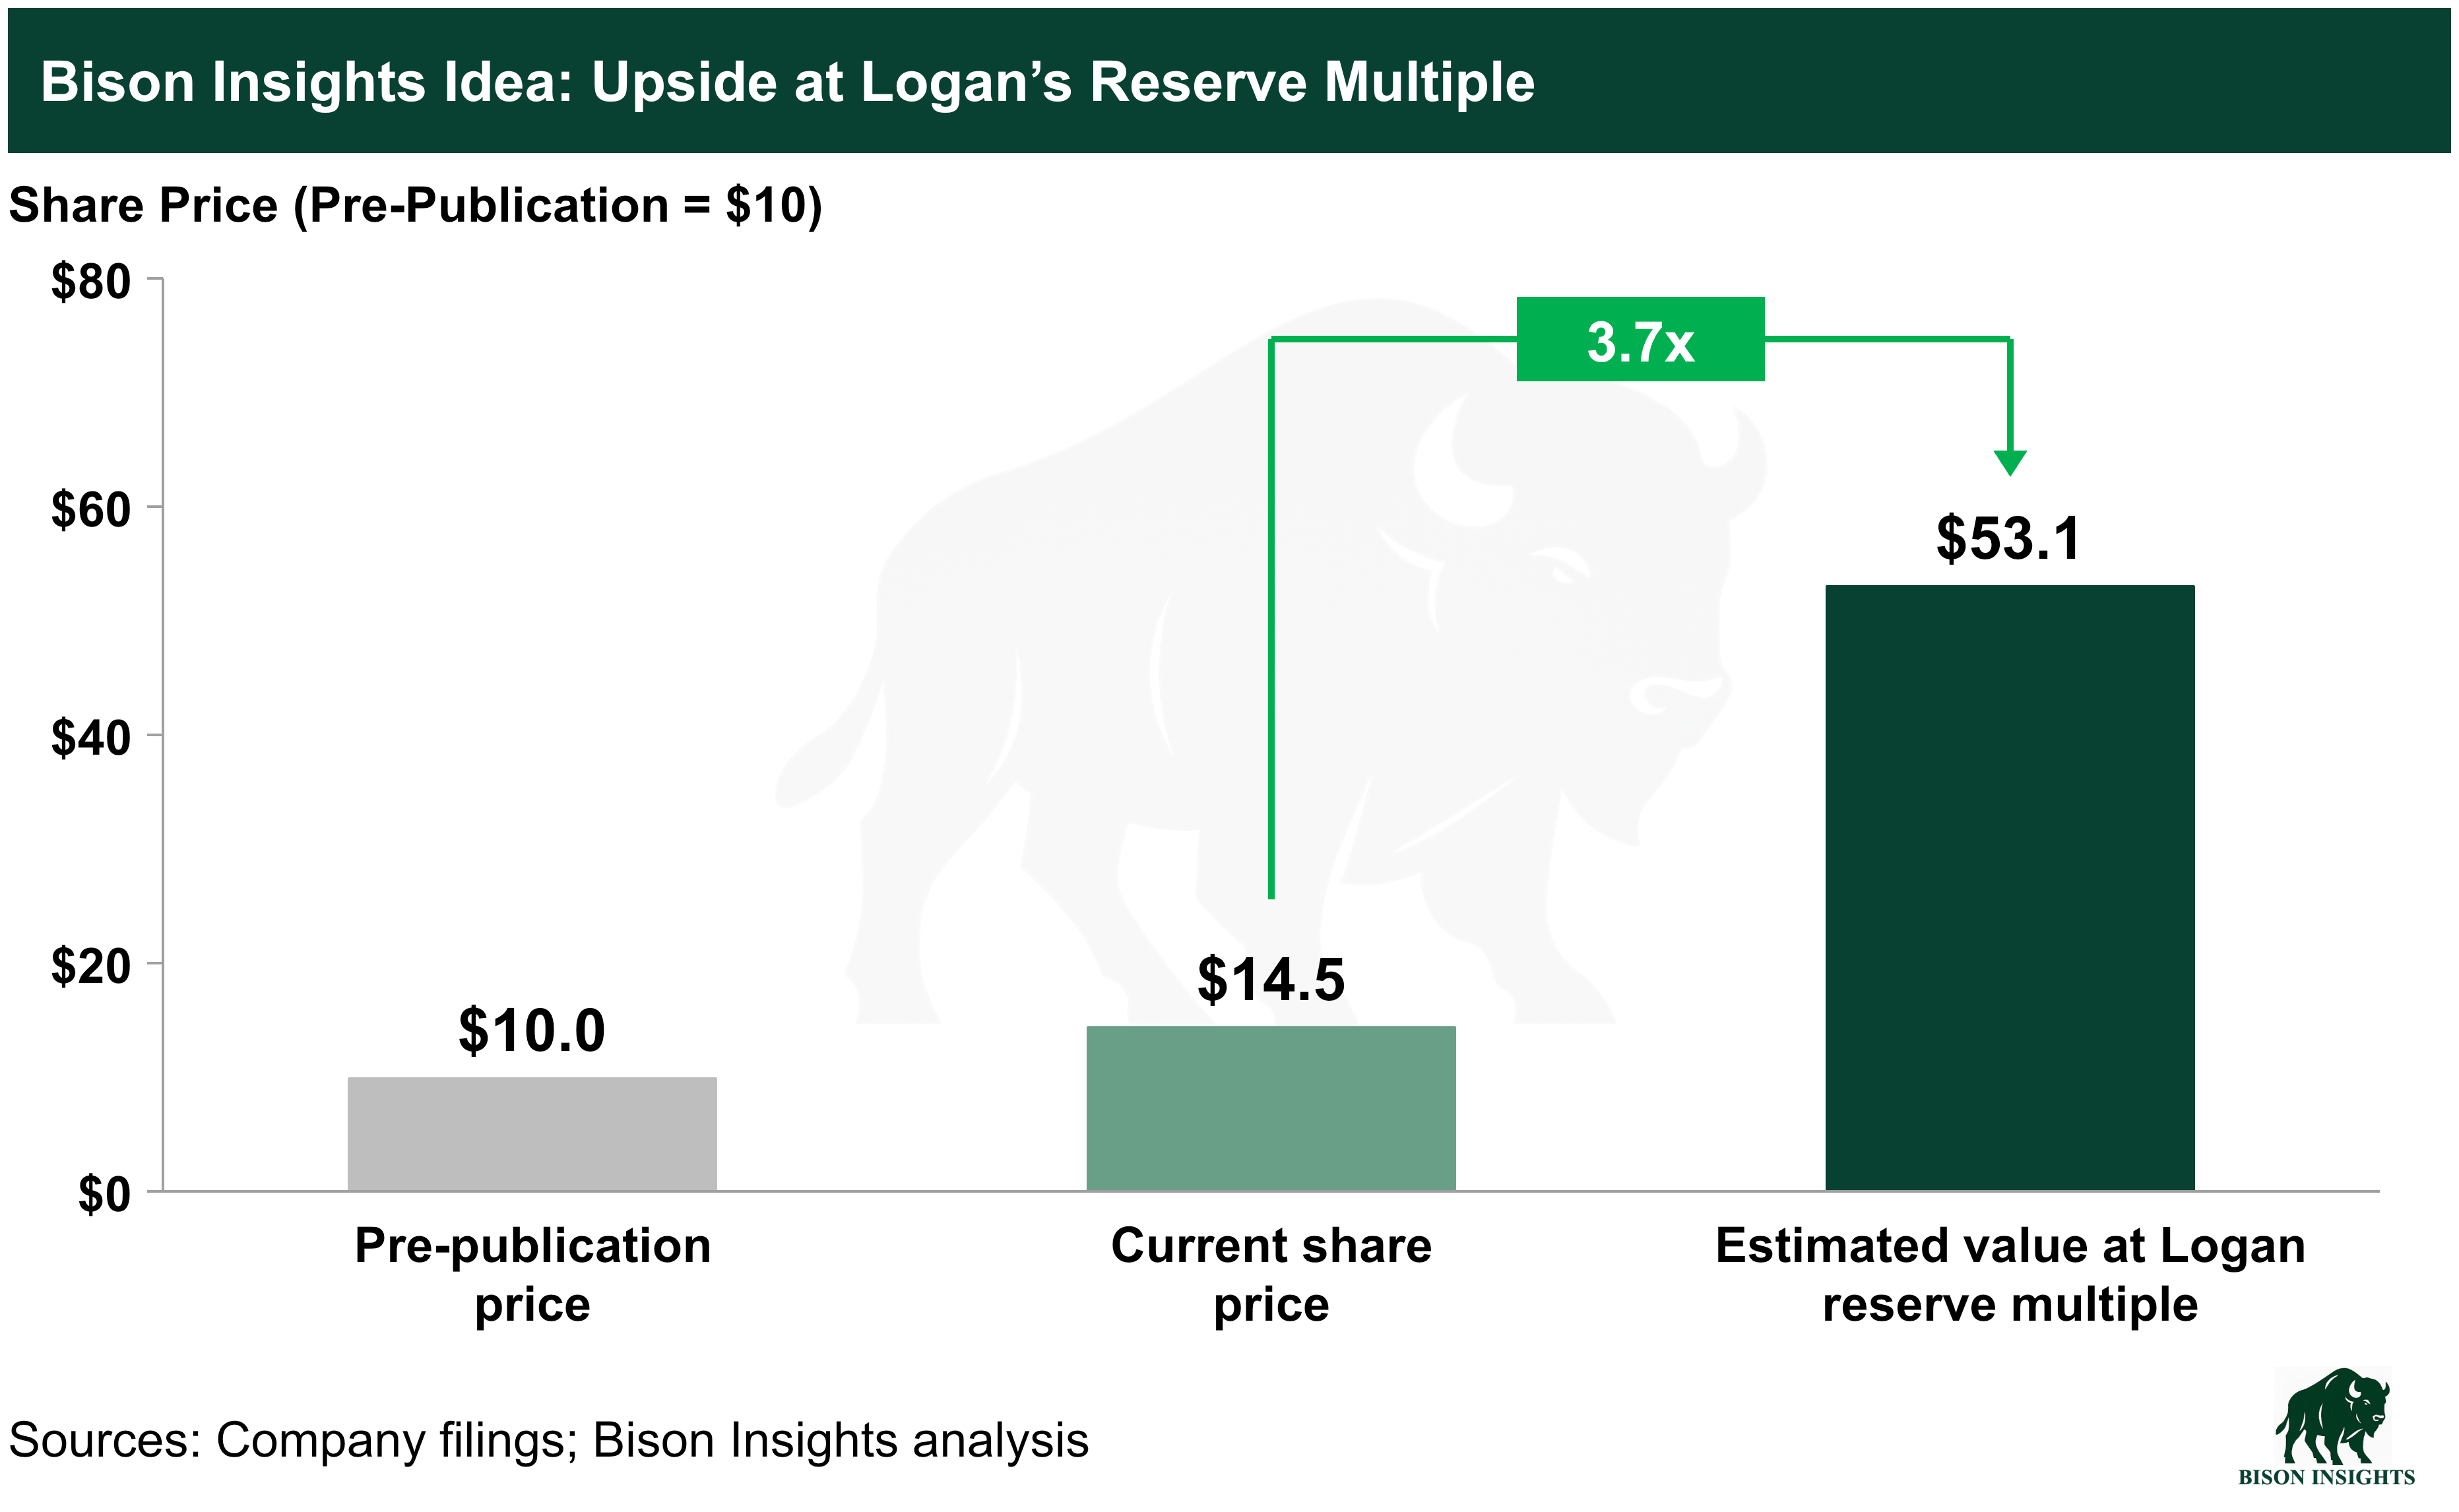
Ovintiv’s C$1.26 billion purchase of Logan Energy at roughly 2x proved reserve value points to further consolidation among Canadian oil…
Entravision’s Q3 ad-tech revenue reached $177.2 million, up 133% year over year, while total revenue rose 88% to $226.3 million and diluted…
Diversified Energy reported $255.6 million of “true” nine-month free cash flow, while its $1.8 billion Birch acquisition would shift…
AutoNation, Lear, NexPoint, AudioCodes and Xponential Fitness lead a 52-situation screen spanning buybacks, insider purchases, M&A and…
Array Technologies and Shoals Technologies plan to merge, targeting cross-selling and cost synergies as ARRY's order book holds firm and…
 Caffital Research 3 clicks
Capital Employed rounds up 48 stock pitches, led by Greystone’s $14.50 target for organ-transplant logistics firm Strata Critical Medical,…
Aura Biosciences expects pivotal Phase 3 bel-sar data in early choroidal melanoma in 2027, funded by $323.8 million of cash into the first…
 Equity Eagle

Markel spent $315 million repurchasing shares in Q3 as Thrive agreed to buy ADT for $7.6 billion and Hasbro cited rising adult toy demand.
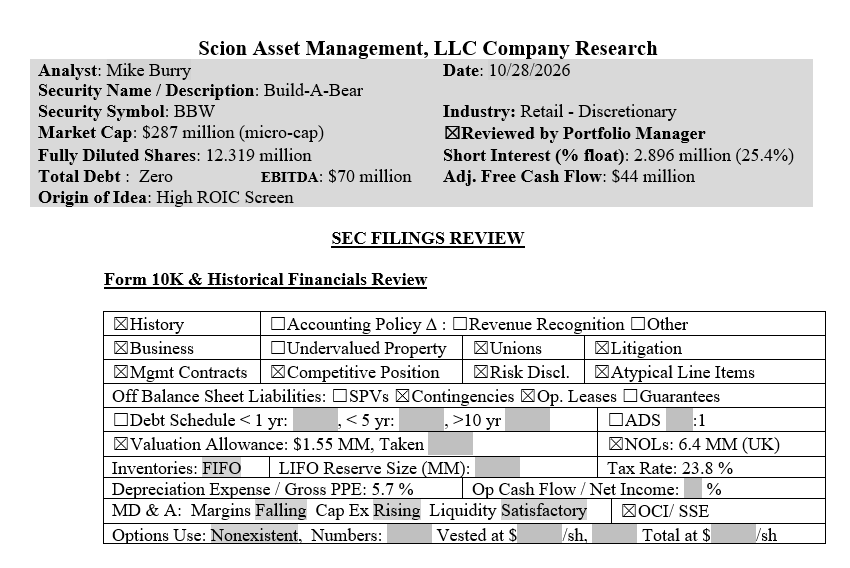
Build-A-Bear’s lease overhaul, off-mall expansion and partner-led wholesale growth reshaped a debt-free retailer with $80 million EBITDA,…
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Atlas Diary
 Bay Area Ideas
 Benjamin C. Barry
 Bernard Zambonin
 Blake Winiecki
 Capital Connoisseur
 Chetan Woodun Crimson And Gold Research
 Cypriot Invests
 Dane Bowler
 Daniel Bell
 Daniel Schönberger
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Gary Gambino
 Geneva Investor
 Gil Rotstein
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Kevin Avroutskii
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Louis Gerard
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Nicolas Bolsinger
 Oakoff Investments
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Sanjay Swamy
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.