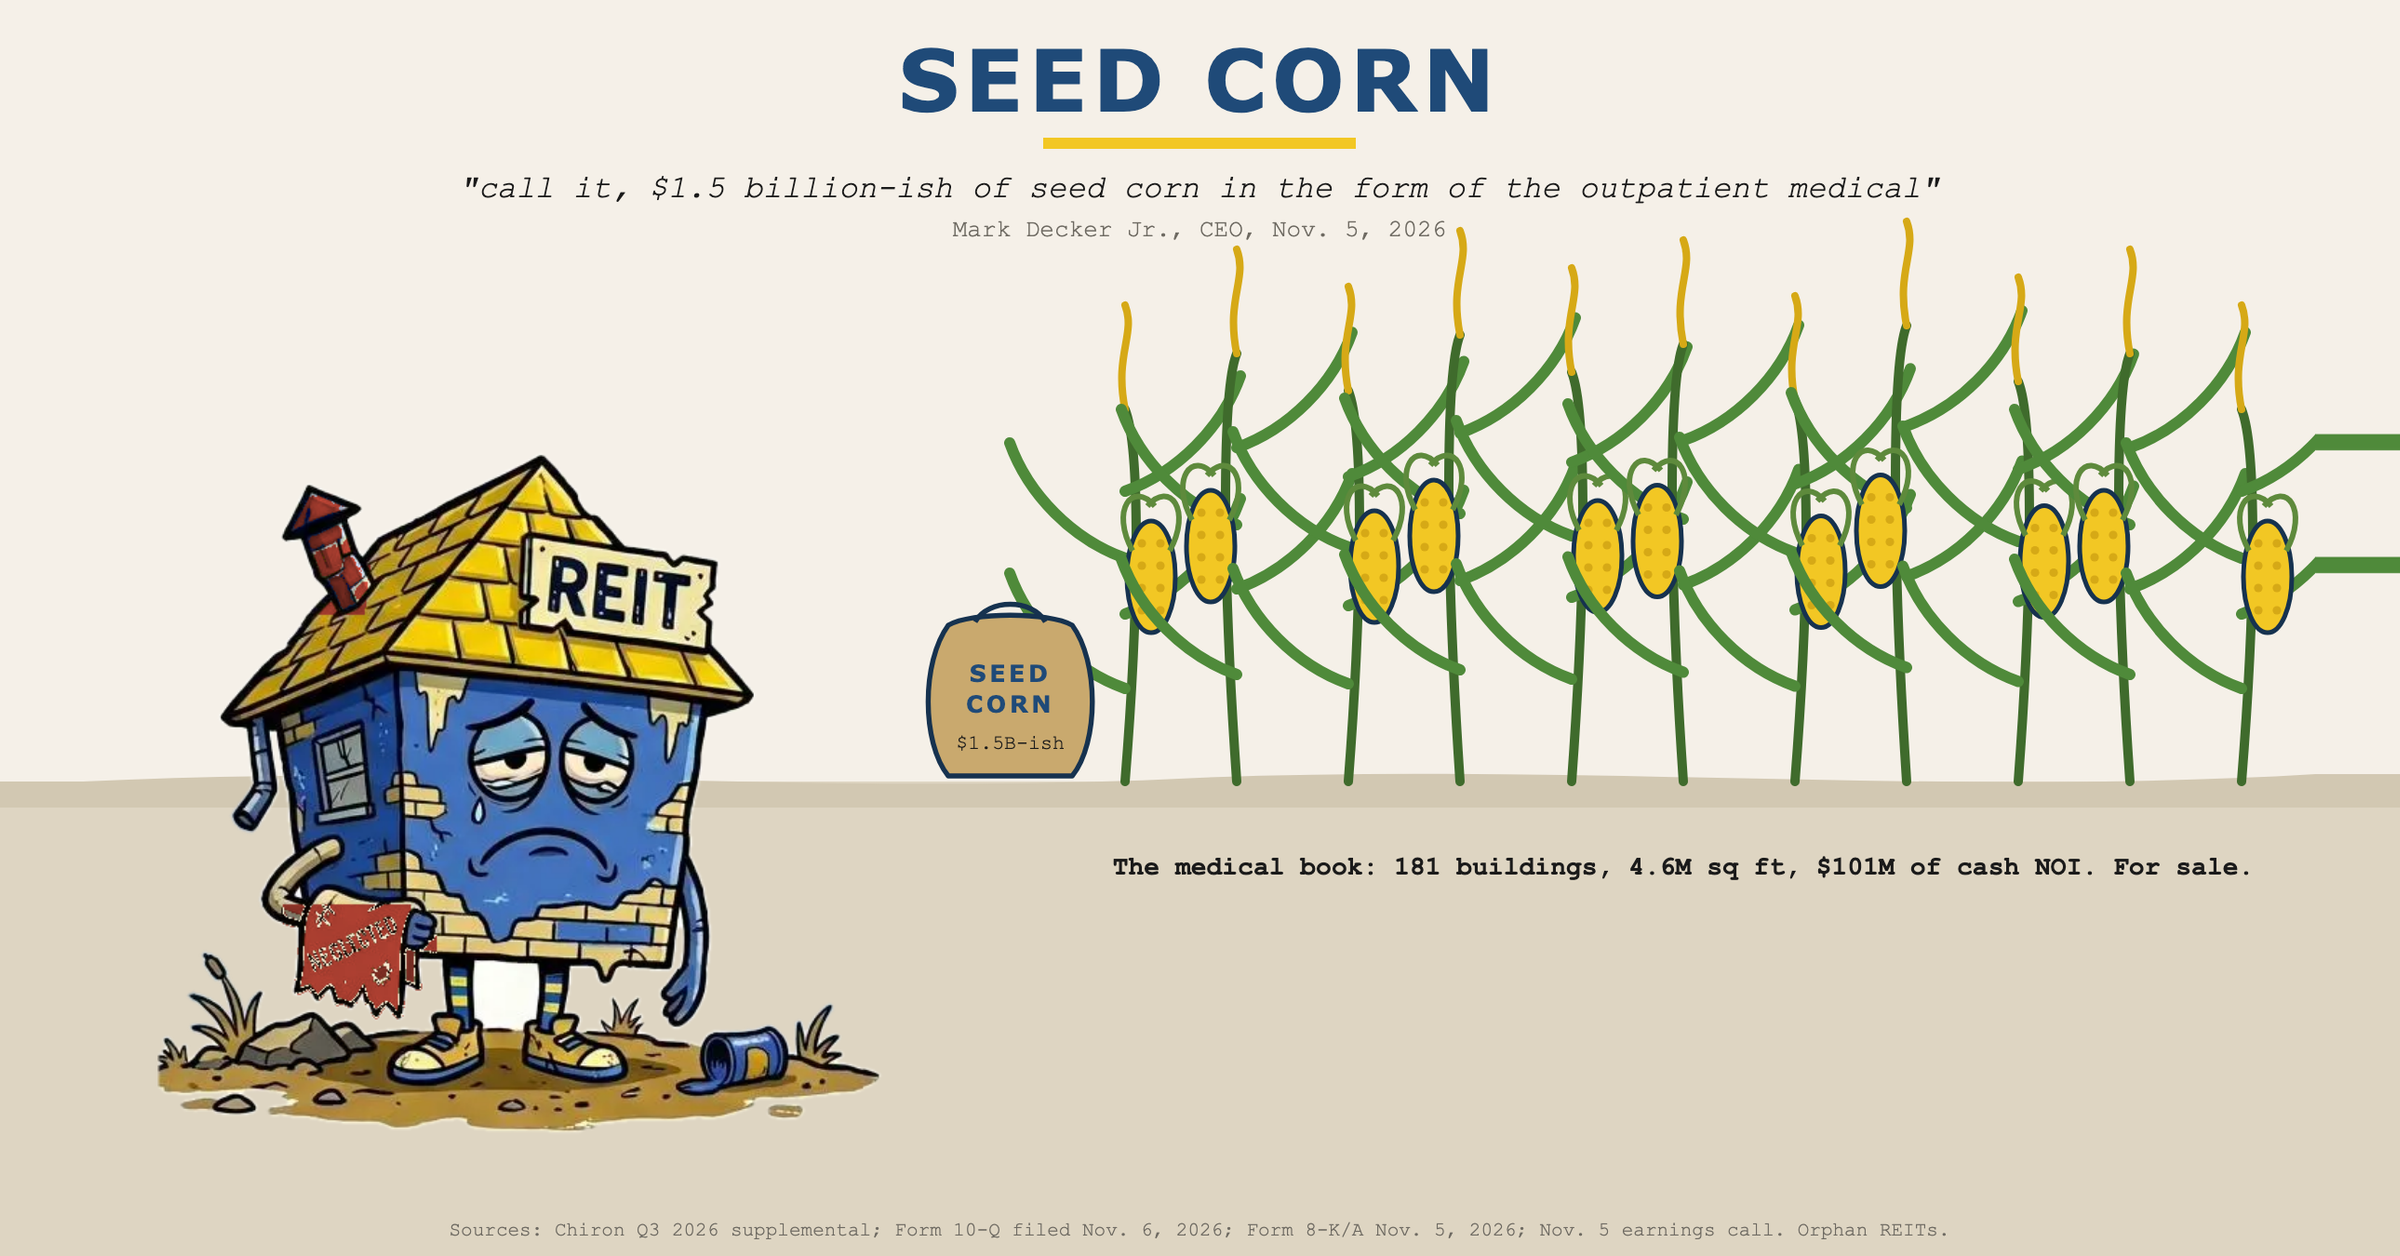
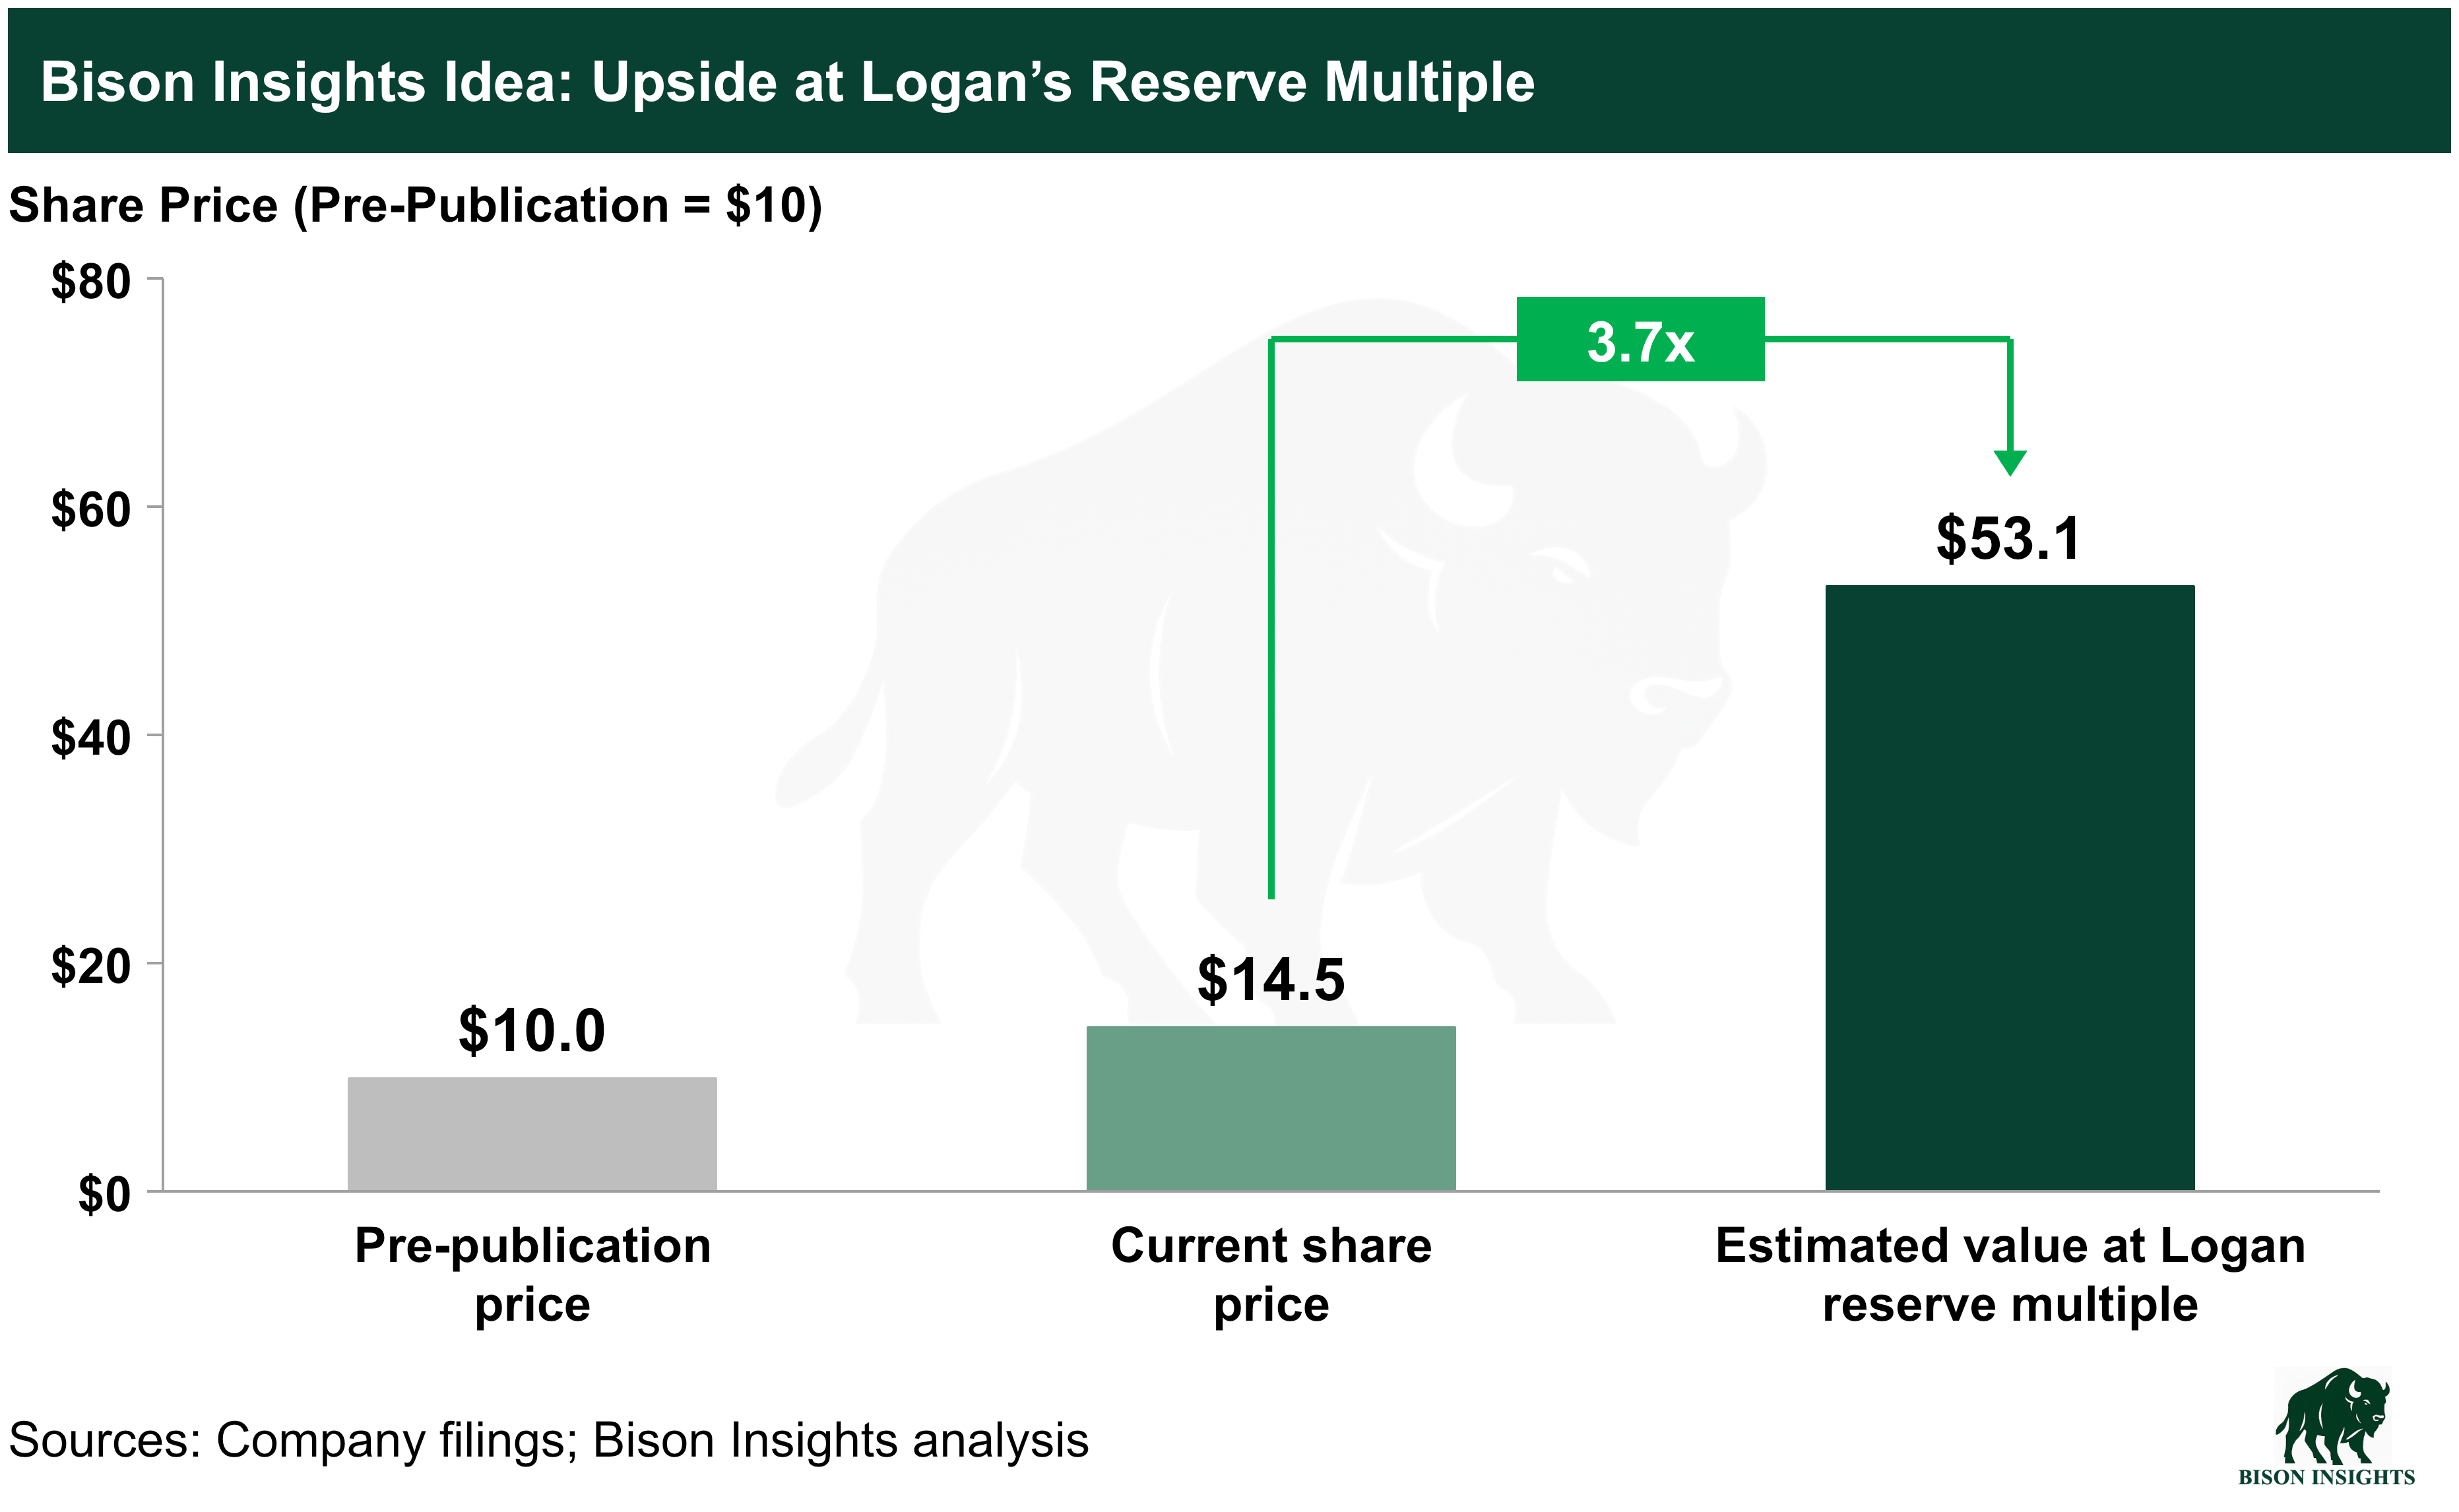Chiron’s failed $49 million Beaumont sale and $178 million Pinnacle acquisition leave XRN with $70 million of liquidity and medical-office…
S Orphan REITs 41h ago 3 clicks
SA Crimson And Gold Research 46h ago 3 clicks EVC's Q3 update cites $30 million for a single station, a broadcast-business sale and stronger positioning for 2027.
S Nat Stewart - Stock Picking Newsletter Nov 6 26 clicks
Ovintiv’s C$1.26 billion purchase of Logan Energy at roughly 2x proved reserve value points to further consolidation among Canadian oil…
S Bison Insights Nov 6 4 clicks
Entravision’s Q3 ad-tech revenue reached $177.2 million, up 133% year over year, while total revenue rose 88% to $226.3 million and diluted…
S The Value Road Nov 6 4 clicks
Diversified Energy reported $255.6 million of “true” nine-month free cash flow, while its $1.8 billion Birch acquisition would shift…
S The Oak Bloke Nov 6 4 clicks
AutoNation, Lear, NexPoint, AudioCodes and Xponential Fitness lead a 52-situation screen spanning buybacks, insider purchases, M&A and…
S Latticework by MOI Global Nov 5 6 clicks
Array Technologies and Shoals Technologies plan to merge, targeting cross-selling and cost synergies as ARRY's order book holds firm and…
SA Caffital Research Nov 5 3 clicks Capital Employed rounds up 48 stock pitches, led by Greystone’s $14.50 target for organ-transplant logistics firm Strata Critical Medical,…
S Capital Employed Nov 1 14 clicks
Verra Mobility’s Avis termination threatens 2027 earnings, while Government Solutions profit rose 25% and implied fourth-quarter guidance…
S The Oak Bloke Oct 31 3 clicks
NGVC · long Natural Grocers (NGVC) returned to $27.80 after a prior long entry at $21 and exit recommendation at $46.
BL Value Investors Club Aug 11
CytomX Therapeutics trades near its $367 million cash balance as Varseta-M moves toward a 2027 pivotal colorectal cancer trial after 20–32%…
SA Cypriot Invests Nov 5 Markel spent $315 million repurchasing shares in Q3 as Thrive agreed to buy ADT for $7.6 billion and Hasbro cited rising adult toy demand.
S TSOH Investment Research Oct 30 1 click
Build-A-Bear’s lease overhaul, off-mall expansion and partner-led wholesale growth reshaped a debt-free retailer with $80 million EBITDA,…
S Cassandra Unchained Oct 29 3 clicks
Mattel, Winnebago and PayPal lead 37 special situations spanning activist campaigns, buybacks, M&A and strategic alternatives.
S Latticework by MOI Global Oct 29 3 clicks
Daktronics, the leader in U.S. sports video boards, targets 10-12% EBIT margins after shifting production to China and Mexico and exiting…
S Hidden Gems Investing Oct 28 6 clicks
Build-A-Bear Workshop’s failed pre-made toy line compressed margins, but resilient children’s sales support a $39.39 fair value estimate…
SA Rafa F. Oliver, CFA Oct 26 4 clicks A four-layer 10-K framework tests revenue timing, receivables, reserves and depreciation against cash flow, using Hertz’s 2012-14…
S Jimmy's Journal Oct 26 70 clicks
Kingstone Company is replacing quota-share cessions with catastrophe reinsurance, lifting quarterly EBIT margin to 29% from a 24% sector…
SA Given Mahlangu Oct 25 3 clicks ERock’s modular microgrids bridge data-center power gaps years before grid interconnects, with Meta and Anthropic projects filling capacity…
S Monte Independent Investment Research Oct 23 11 clicks