Entravision’s Q3 ad-tech revenue reached $177.2 million, up 133% year over year, while total revenue rose 88% to $226.3 million and diluted…
S The Value Road Nov 6 4 clicks
CareCloud rebuilt its sales organization under Christopher Langehaug after 18 months without a sales leader, with a second sales rep…
S Calvin Blissett 43h ago 5 clicks
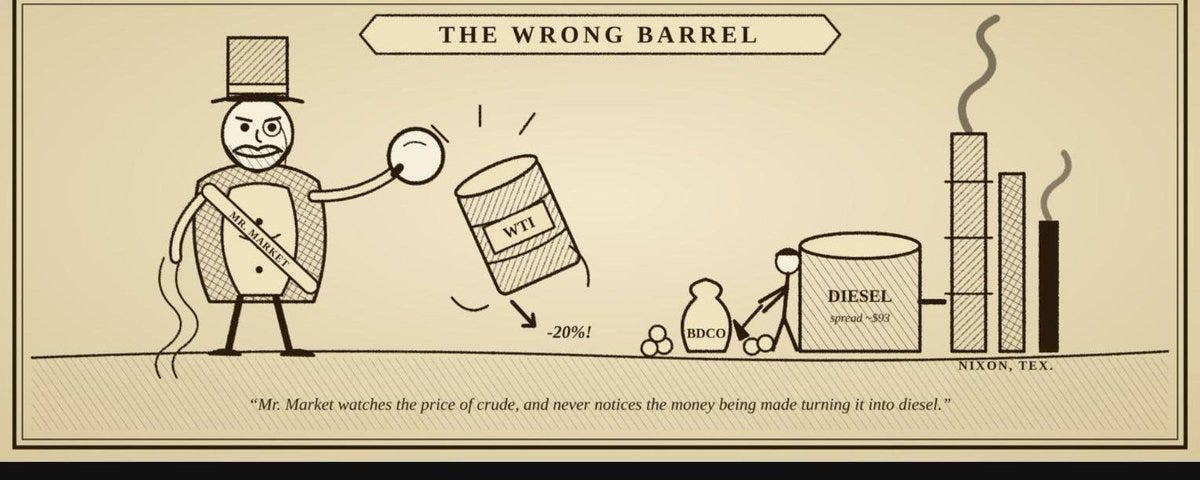
Diversified Energy reported $255.6 million of “true” nine-month free cash flow, while its $1.8 billion Birch acquisition would shift…
S The Oak Bloke 47h ago 3 clicks
CareCloud’s Q3 revenue rose 9% through acquisitions but fell 8% pro forma; the RCM consolidator targets 25–30% margins by shifting acquired…
S Calvin Blissett Nov 6 1 click
BL Clark Street Value Nov 5 5 clicks
AutoNation, Lear, NexPoint, AudioCodes and Xponential Fitness lead a 52-situation screen spanning buybacks, insider purchases, M&A and…
S Latticework by MOI Global Nov 5 5 clicks
Array Technologies and Shoals Technologies plan to merge, targeting cross-selling and cost synergies as ARRY's order book holds firm and…
SA Caffital Research Nov 5 3 clicks Site Centers' $3 per-share return-of-capital distribution and December delisting leave a discounted liquidation stub, with two properties…
S Real Assets, Real Value Nov 4 5 clicks
Diana Shipping’s Genco stake equals nearly 60% of its market cap, leaving its 36-ship fleet valued at about $1 per share as charter…
SA The Market Auditor Nov 4 Capital Employed rounds up 48 stock pitches, led by Greystone’s $14.50 target for organ-transplant logistics firm Strata Critical Medical,…
S Capital Employed Nov 1 14 clicks
TNLIF · long Trainline’s buyback and high free-cash-flow yield support a long thesis.
BL Value Investors Club Aug 10 1 click
SA Cypriot Invests Nov 5 TurnMark Capital’s Jamil Tahir describes buying entrepreneur-led microcaps at fundamental inflection points and using Claude to automate…
S Sunday's Idea Brunch Nov 1 3 clicks
Travelzoo’s roughly 400,000 prepaid members generate deferred revenue while acquisition costs hit GAAP earnings immediately, masking the…
S Calvin Blissett Nov 1 2 clicks
Verra Mobility’s Avis termination threatens 2027 earnings, while Government Solutions profit rose 25% and implied fourth-quarter guidance…
S The Oak Bloke Oct 31 3 clicks
Markel spent $315 million repurchasing shares in Q3 as Thrive agreed to buy ADT for $7.6 billion and Hasbro cited rising adult toy demand.
S TSOH Investment Research Oct 30 1 click
One Stop Systems grew Q3 continuing-operations revenue 36% to $12.6 million, raised FY2026 revenue guidance to $45 million, and used $11.8…
BL Cestrian Capital Research Oct 29 1 click
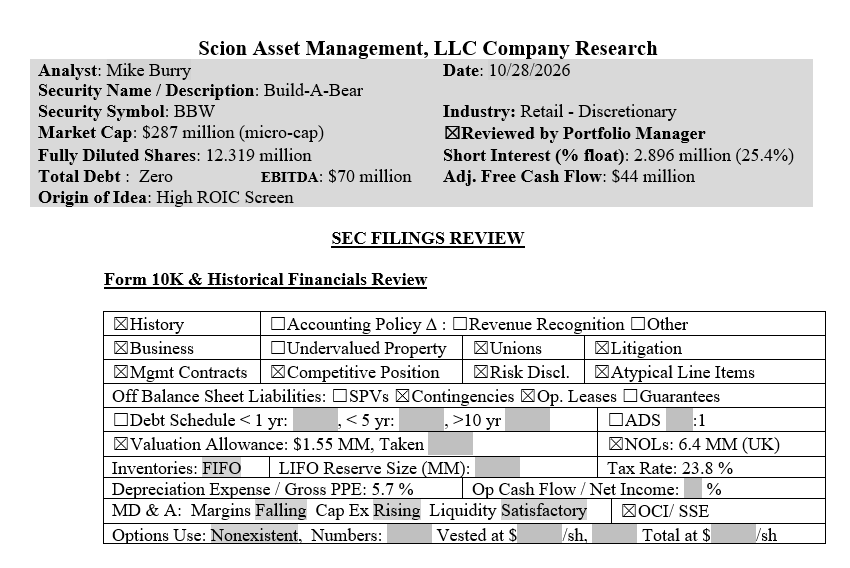
Build-A-Bear’s lease overhaul, off-mall expansion and partner-led wholesale growth reshaped a debt-free retailer with $80 million EBITDA,…
S Cassandra Unchained Oct 29 3 clicks
Mattel, Winnebago and PayPal lead 37 special situations spanning activist campaigns, buybacks, M&A and strategic alternatives.
S Latticework by MOI Global Oct 29 3 clicks
Duos Technologies, DUOT, has shifted to modular edge data center pods, with Q2 revenue up 30% to $6.18 million and FY27 revenue guided…
SA Shareholders Unite Oct 29 2 clicks