48 Top Stock Pitches (26th-1st November) [NO PAYWALL] 🖨️
Capital Employed rounds up 48 stock pitches, led by Greystone’s $14.50 target for organ-transplant logistics firm Strata Critical Medical, versus $4.70.
Capital Employed rounds up 48 stock pitches, led by Greystone’s $14.50 target for organ-transplant logistics firm Strata Critical Medical, versus $4.70.
Continue reading here for my bear, base, and bull cases on $QMCO: https://t.co/GXzV3AQBgs
@SurgeonInvests1 Great point .. $MUEL is a great case study to show what growth capex looks like (started getting aggressive in 2024). https://t.co/3uNLncefjD
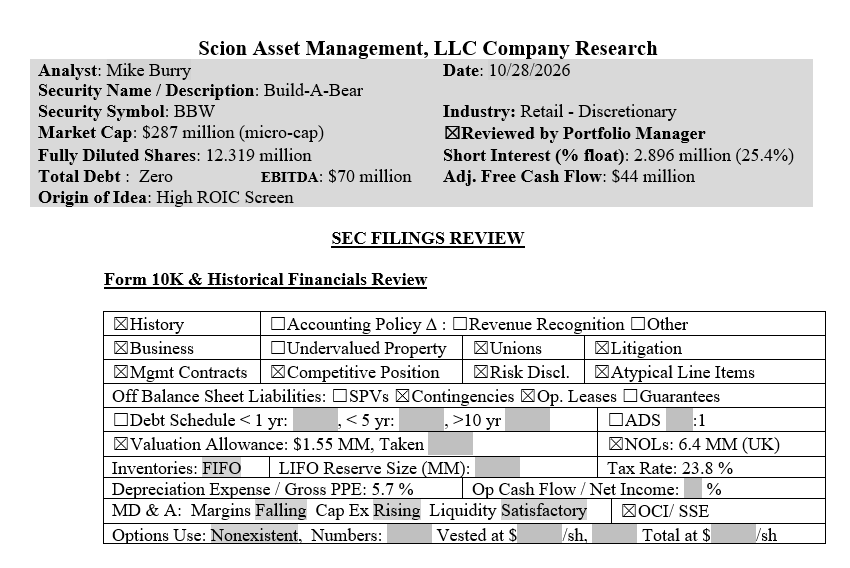
Build-A-Bear’s lease overhaul, off-mall expansion and partner-led wholesale growth reshaped a debt-free retailer with $80 million EBITDA,…
Mattel, Winnebago and PayPal lead 37 special situations spanning activist campaigns, buybacks, M&A and strategic alternatives.
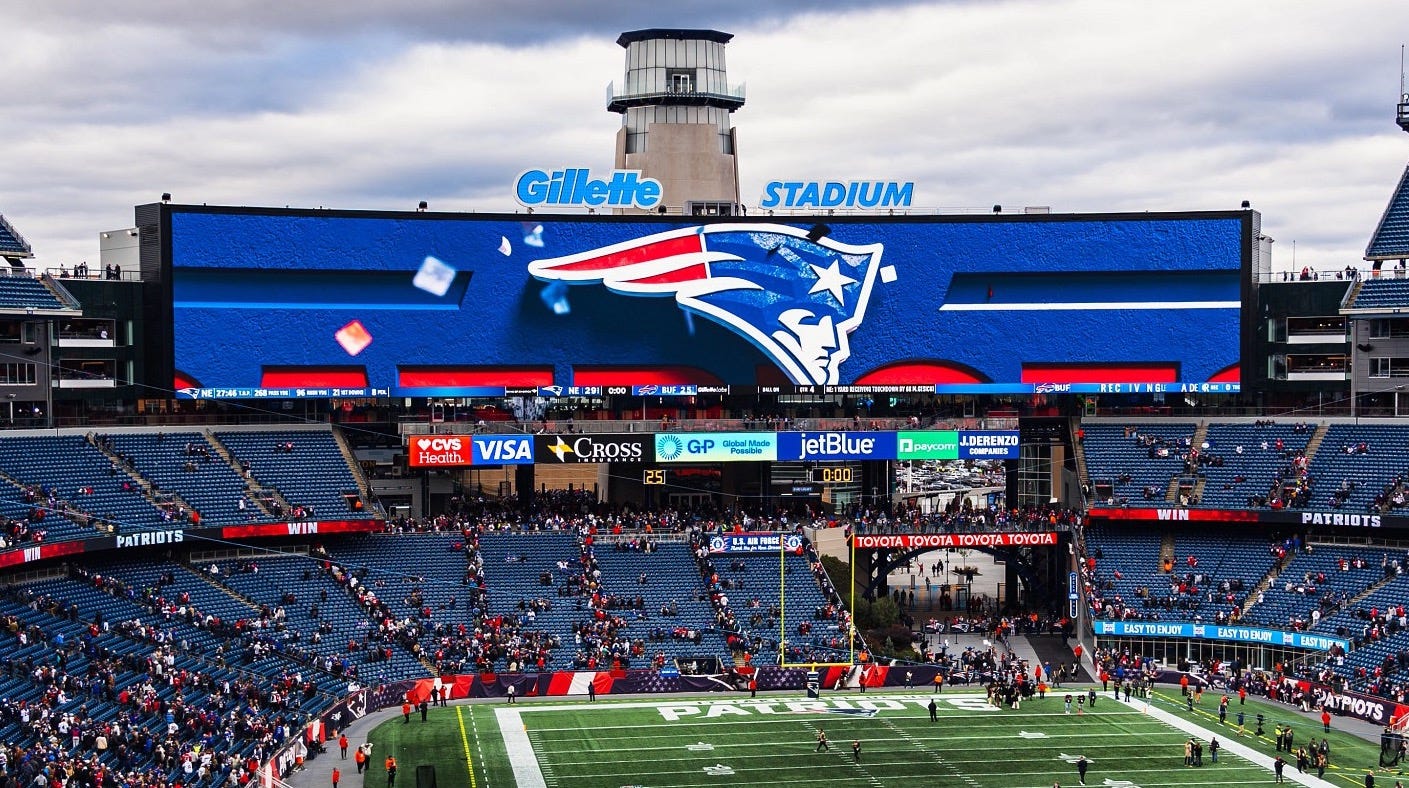
Daktronics, the leader in U.S. sports video boards, targets 10-12% EBIT margins after shifting production to China and Mexico and exiting…
Build-A-Bear Workshop’s failed pre-made toy line compressed margins, but resilient children’s sales support a $39.39 fair value estimate…
 Rafa F. Oliver, CFA 4 clicks
A four-layer 10-K framework tests revenue timing, receivables, reserves and depreciation against cash flow, using Hertz’s 2012-14…
Avalo Therapeutics' Abdakibart enters a pivotal hidradenitis suppurativa trial after positive LOTUS data, with monthly dosing and…
 Myriam Alvarez 3 clicks
Six Value Line small caps including Blackbaud, Marqeta, Ranger Energy and Definitive Healthcare trade on net cash, buybacks, low multiples…
ERock’s modular microgrids bridge data-center power gaps years before grid interconnects, with Meta and Anthropic projects filling capacity…
Bumble agreed to a $6.05-per-share cash sale to Ithaca Holdings, 136% above its October 2 share price.
Sagimet Biosciences' denifanstat enters a fully funded U.S. acne registration trial after Phase 3 results, with SGMT trading below cash and…
 Equity Eagle 3 clicks
 MG · long
Mistras Group is a rare publicly traded US non-destructive testing pure play, providing quality assurance for materials, components and…
Turning Point Brands awaits FDA pouch approval, Meitec benefits from Japan’s engineer shortage, and Viemed gains from Medicare’s…
T1 Energy’s G2_Austin factory is expected to lift margins and add vertical integration from 2027, but requires substantial financing that…
 Investor Overview
Groupon CEO Dušan Šenkypl and CFO Rana Kashyap discuss rebuilding the local-experiences marketplace with AI infrastructure, better…

Independence Realty Trust is buying Centerspace in stock to create an $8.1 billion apartment REIT, targeting 5% 2027 Core FFO per-share…
 Dane Bowler

Sofwave Medical grew Q2 revenue 43% as recurring usage fees reached 46% of sales for its non-invasive ultrasound skin-tightening devices.
Priority Technology’s chairman offered $6.00 to $6.15 a share to take PRTH private, while Zack Buckley argues Treasury Solutions and…
GeoPark’s Bare Block acquisition targets $1.2 billion of 2030 EBITDA, but 42.1 million to 47.6 million new shares and Gilinski control…
Farmland Partners trades at 70% of NAV, with farmland appreciation, commodity prices and crop insurance supporting earnings beyond AFFO.
Dane Bowler 
ContextLogic will acquire specialty-solvent maker gChem for $850 million, funded by a $650 million rights offering and $250 million of…
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.