TSOH Weekly Roundup (10/30/2026)
Markel spent $315 million repurchasing shares in Q3 as Thrive agreed to buy ADT for $7.6 billion and Hasbro cited rising adult toy demand.
Markel spent $315 million repurchasing shares in Q3 as Thrive agreed to buy ADT for $7.6 billion and Hasbro cited rising adult toy demand.
Its crappening! $CD drops again. https://t.co/34xgZuhj5F
Punted on some $MNRO at the open.
$HTZ - IBKR borrow is out again. Positioning for next weeks earnings likely happening. https://t.co/vIuwLhQQNc
Continue reading here for my bear, base, and bull cases for $TOYO at those multiples: https://t.co/76t1GCSzlU
Read the 20-F’s line on VSun China’s wafers here: https://t.co/VORm0Lw2wt Continue reading here for what each possible Commerce ruling does to my valuation of $TOYO: https://t.co/76t1GCSzlU
Mattel, Winnebago and PayPal lead 37 special situations spanning activist campaigns, buybacks, M&A and strategic alternatives.
Duos Technologies, DUOT, has shifted to modular edge data center pods, with Q2 revenue up 30% to $6.18 million and FY27 revenue guided…
 Shareholders Unite 2 clicks
Daktronics, the leader in U.S. sports video boards, targets 10-12% EBIT margins after shifting production to China and Mexico and exiting…
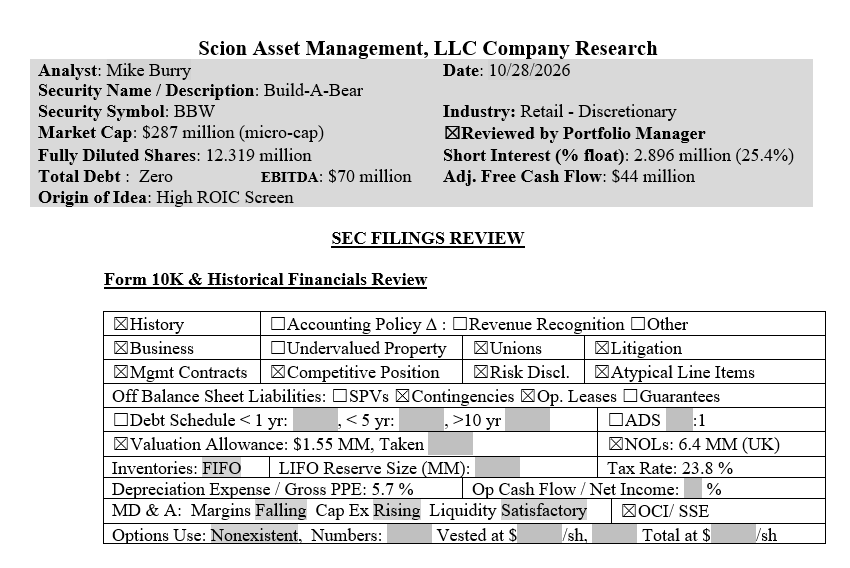
Build-A-Bear Workshop’s failed pre-made toy line compressed margins, but resilient children’s sales support a $39.39 fair value estimate…
 Rafa F. Oliver, CFA 4 clicks
A four-layer 10-K framework tests revenue timing, receivables, reserves and depreciation against cash flow, using Hertz’s 2012-14…

Getty Images' 2026 Chapter 11 filing is challenged as a prepack after warrant litigation, a failed Shutterstock merger and AI pressure.
Kingstone Company is replacing quota-share cessions with catastrophe reinsurance, lifting quarterly EBIT margin to 29% from a 24% sector…
 Given Mahlangu 3 clicks
Six Value Line small caps including Blackbaud, Marqeta, Ranger Energy and Definitive Healthcare trade on net cash, buybacks, low multiples…
ERock’s modular microgrids bridge data-center power gaps years before grid interconnects, with Meta and Anthropic projects filling capacity…
Unicycive’s oxylanthanum carbonate NDA earned a March 25, 2027 PDUFA date after two manufacturing-related rejections, with no FDA clinical…
 SAMG · long
Silvercrest Asset Management is framed as undervalued while funding an ambitious investment cycle.
Bumble agreed to a $6.05-per-share cash sale to Ithaca Holdings, 136% above its October 2 share price.
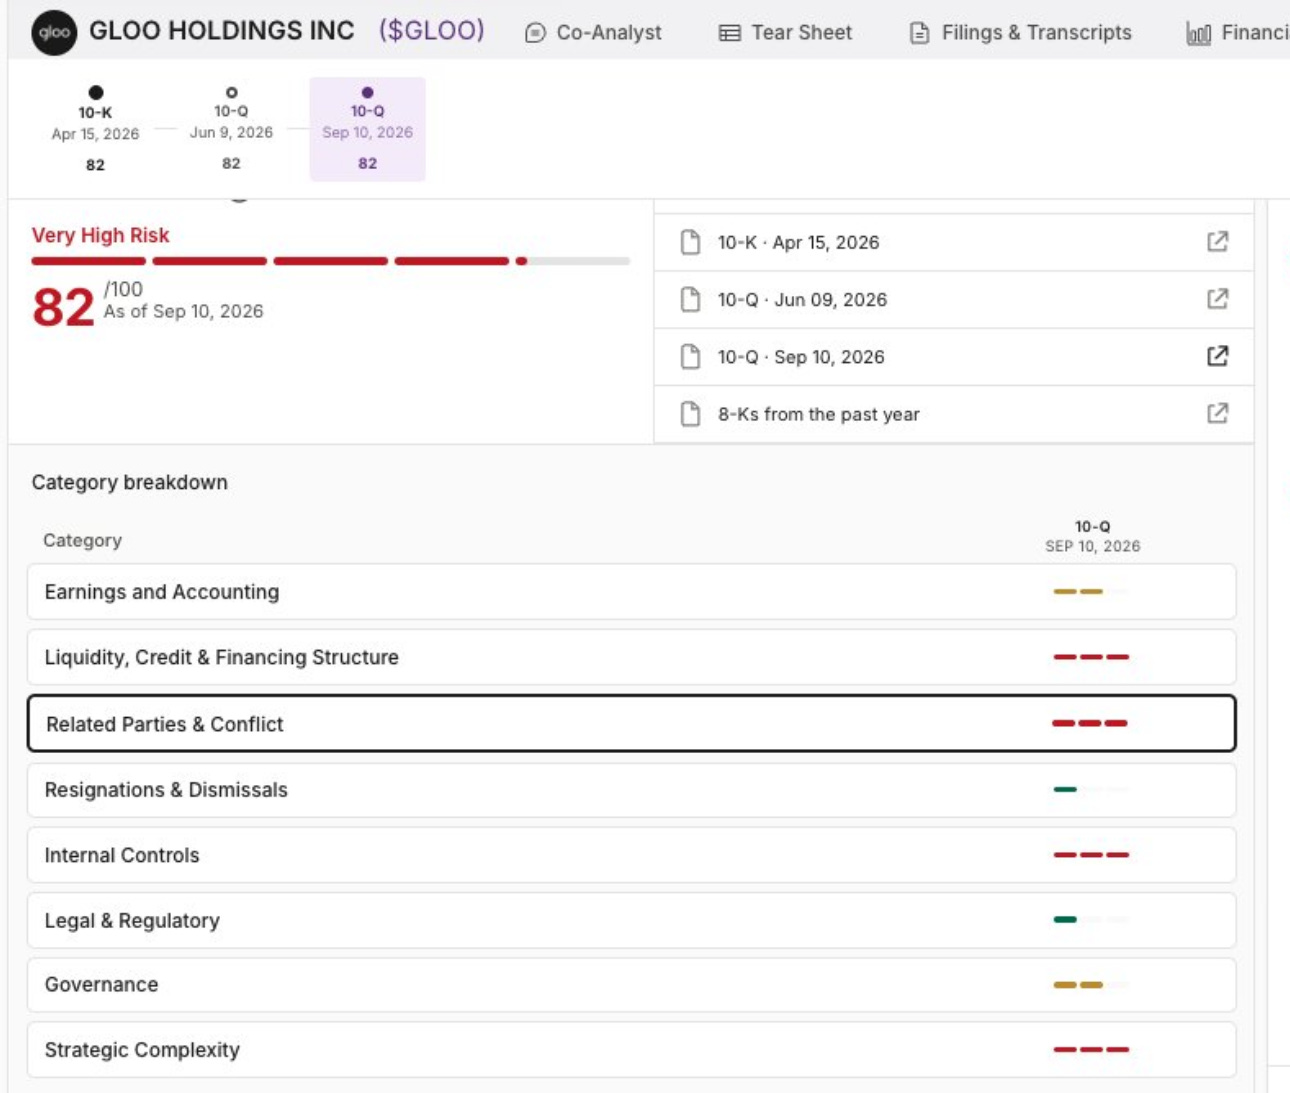
Gloo faces related-party deals, insider-heavy IPO ownership, acquisition losses and $84.5 million of CEO-backed puts as it burns cash and…
Sagimet Biosciences' denifanstat enters a fully funded U.S. acne registration trial after Phase 3 results, with SGMT trading below cash and…
 Equity Eagle 3 clicks
CareCloud may attract a private-equity buyer after its Q3 call, with acquiring enough shares the main obstacle to a take-private deal.
AGI Inc trades at 5.6x earnings after a 35% post-IPO decline, despite roughly 30% ROE and resilient INSS payroll-loan growth.
 Multiplo Invest 14 clicks
Lanxess can force Advent to buy at least half its Envalior stake in April 2028, potentially raising about €745 million to reduce net debt.
Eagle Point Credit's NAV is down 25% YTD and shares nearly 50%, while its expense ratio climbed to 9.21% despite a 25% yield.
 Anthony Cataldo 5 clicks
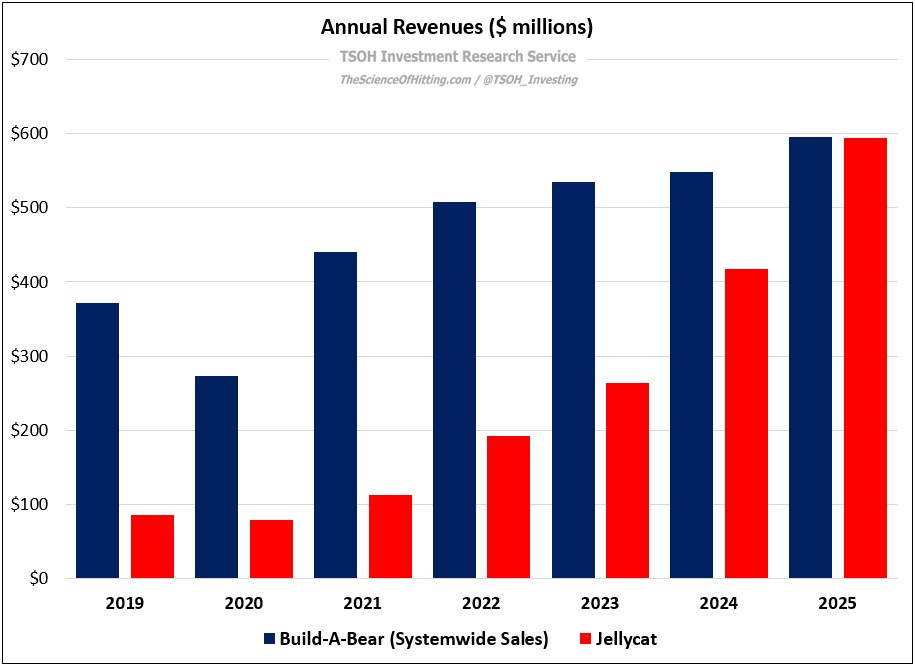
Build-A-Bear's push into prestuffed toys and broader retail distribution tests brand stretchability, but recent results warrant caution.
LendingTree derives roughly two-thirds of revenue from insurance and trades near 4 times expected adjusted earnings despite record revenue,…
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.