Group 1 Automotive (GPI): Q3 2026 Earnings
Group 1 Automotive trades at 5.5 times earnings as aging gasoline vehicles and EV repairs sustain service profits; insiders bought while short interest rose.
Group 1 Automotive trades at 5.5 times earnings as aging gasoline vehicles and EV repairs sustain service profits; insiders bought while short interest rose.
CXMT capex is $ACMR revenue https://t.co/kB7DGSKyOl
@ada_lawren $FLNC starts reporting U.S. output vs its own forecast with these results, and Houston was at ~3 units/day in September vs the 11/day plan. FY27 already has ~$2.9B of scheduled backlog, so it comes down to whether they can build it. https://t.co/nFgH33tMPV
Just posted the $QMCO update here (you can read most of it for free): https://t.co/GXzV3AQBgs
Some thoughts on $TDOC ahead of Q3 results this evening from @pinealcapital 👇 https://t.co/aDbpzJ9Rpc
Rick Bensignor is on fire Long $OIH vs $XOP The insane alpha valuation continues. Join our conference today. John Roque on deck. Mary Ann Bartels in the hole. Replays to follow. @InTheKnowTrader @dachartlife @RyanDetrick @alphatrends @MarkNewtonCMT @FrankCappelleri @davevermilion https://t.co/24kumycsvc
Innodata shares fell 25% to $44.74 after India Today reported 550 job cuts in India.

AppFolio grew third-quarter revenue 19% as Realm-X AI agents gained adoption, lifting guidance to $1.122 billion to $1.127 billion.
TTM Technologies’ record Q3 and data-center exposure drove a 27.7% stock drop as investors questioned debt-funded growth, leverage and the…
 Nicolas Bolsinger 1 click
Monte Investments updates Carpenter Technology after a 25% sell-off, tracks EQT’s $12.83 billion Range Resources acquisition and assesses…
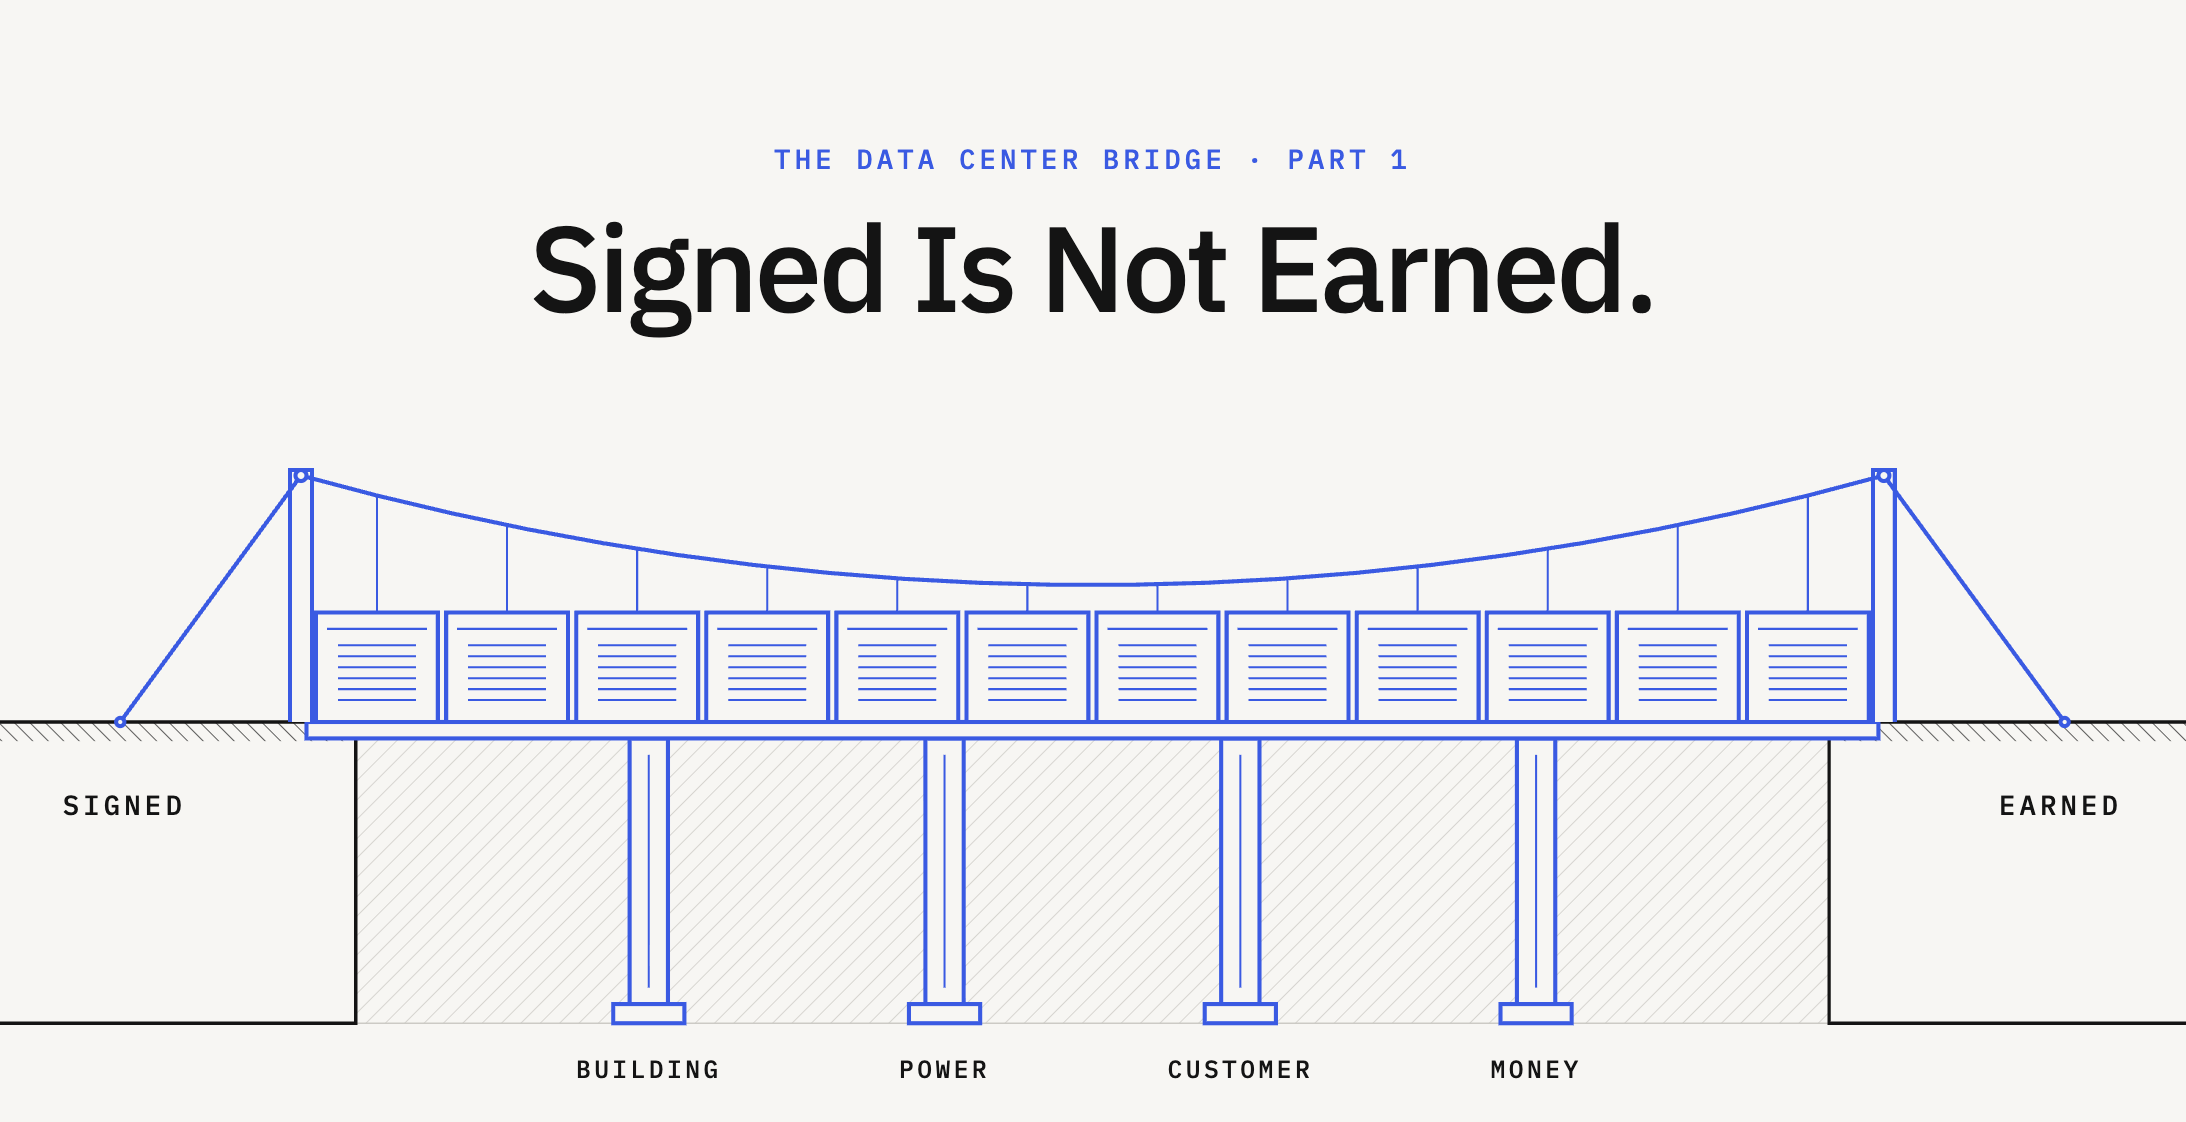
Small- and mid-cap data center stocks trade as one despite sharply different funding bridges: 12 of 15 cover fixed costs on signed…
A Brazilian digital bank with 45 million clients fell 36% after Lula’s election, despite 16.3% ROE, 13 record quarters and a 7.4x earnings…
Build-A-Bear Workshop’s failed pre-made toy line compressed margins, but resilient children’s sales support a $39.39 fair value estimate…
 Rafa F. Oliver, CFA 4 clicks
Molina Healthcare and Kinsale Capital’s earnings are reassessed through a long-term lens, emphasizing conviction and detachment during…
Duolingo sacrificed over $50 million of 2026 bookings to reduce free-app friction, reaccelerate daily users and target 100 million DAUs by…
 Geneva Investor 4 clicks
A four-layer 10-K framework tests revenue timing, receivables, reserves and depreciation against cash flow, using Hertz’s 2012-14…
 WULF · long
TeraWulf is shifting from bitcoin mining toward data centers, seeking a higher-quality and more defensive business model.
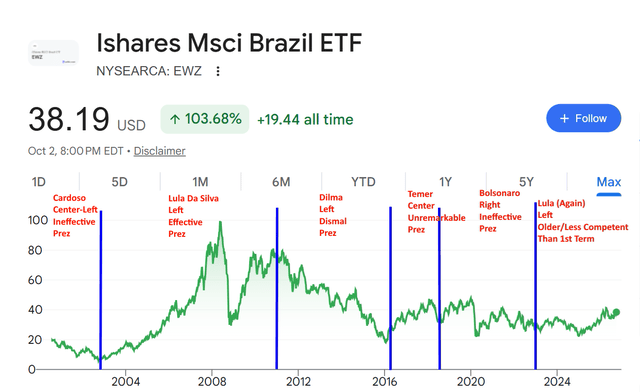
Brazil’s Lula victory leaves Nu and Inter’s thesis intact, while JetBlue heads toward bankruptcy and Mexican airlines pursue a merger.
Klaviyo's customer-data platform and new AI Composer product underpin a bullish growth case, with Salesforce's Braze acquisition cited as a…
 Fountainhead 2 clicks
Signet Jewelers cut its share count from 87 million to 38 million since 2012 as short interest reaches 15%, amid a hated diamond market.
Avalo Therapeutics' Abdakibart enters a pivotal hidradenitis suppurativa trial after positive LOTUS data, with monthly dosing and…
 Myriam Alvarez 3 clicks
Six Value Line small caps including Blackbaud, Marqeta, Ranger Energy and Definitive Healthcare trade on net cash, buybacks, low multiples…
EXLService's AI-led business, 61% of revenue and growing 30% year over year, trades at 18 times forward earnings after legacy digital…
 Ignacio Planas Gonzalez 4 clicks
ERock’s modular microgrids bridge data-center power gaps years before grid interconnects, with Meta and Anthropic projects filling capacity…
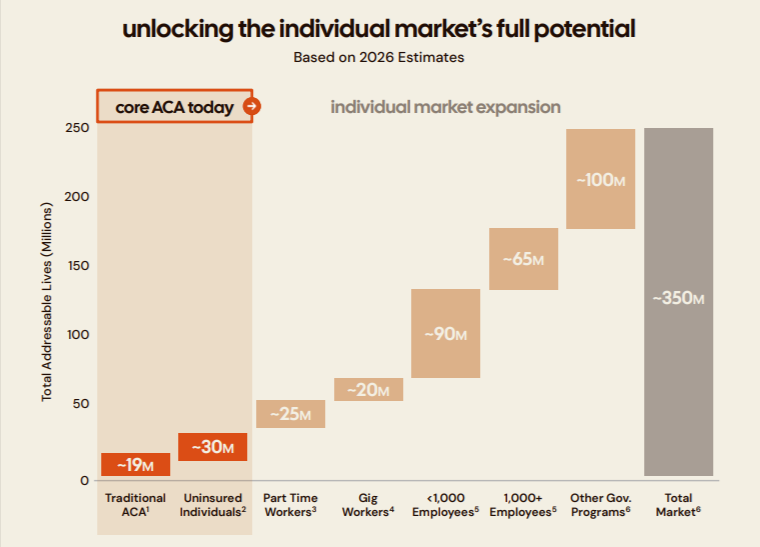
Oscar Health raised 2026 operating earnings guidance to $600 million-$800 million after ACA-marketplace expansion drove 60% membership and…

HFI Portfolio bought 94,214 shares of Transocean, RIG, for $570,000 at $6.05 per share.
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil Fountainhead Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.