I went through all 142 companies in Value Line this morning. Here are the 6 that made it
Six Value Line small caps including Blackbaud, Marqeta, Ranger Energy and Definitive Healthcare trade on net cash, buybacks, low multiples or a takeover bid.
Six Value Line small caps including Blackbaud, Marqeta, Ranger Energy and Definitive Healthcare trade on net cash, buybacks, low multiples or a takeover bid.
@DivinelyLevered They rug pulled them twice. Car wash and then restatement…bigger issue is that mgmt clearly has no agency here. They often just read off a script. If mgmt could speak freely and convince holders they r in control would also help. $DRVN
@DivinelyLevered The market is apathetic to apathy. If Roark starts actioning value creation activity, I doubt the stock will be here. The buyback is a start. The money is in selling collision and glass. $DRVN
Yes they can…. But they said it was substantially undervalued at 18. $drvn https://t.co/zi6dKZflsf
$FUBO asymmetric @ $8.85
I wonder if Russia/Ukraine will come to some sort of agreement soon? 🤷♂️ $KYIV https://t.co/kkm1TDJbPf
MYR Group’s Q3 2026 preview cites data-center and power transmission demand, with long-term service agreements supporting margin growth and…
Mosaic’s potash business generated $930 million after capital spending and closure cash in 2025, while phosphate operations consumed $207…
Mosaic’s history traces the 2004 Cargill-IMC merger and the phosphate and potash mines that shaped NYSE: MOS.
Mosaic, NYSE: MOS, is the subject of a second audio program for professional investors analyzing fertilizer producers.
Unicycive’s oxylanthanum carbonate NDA earned a March 25, 2027 PDUFA date after two manufacturing-related rejections, with no FDA clinical…
Group 1 Automotive and Lithia Motors divide two longtime value investors: David Abrams switched to Lithia in 2018, while Greg Alexander…
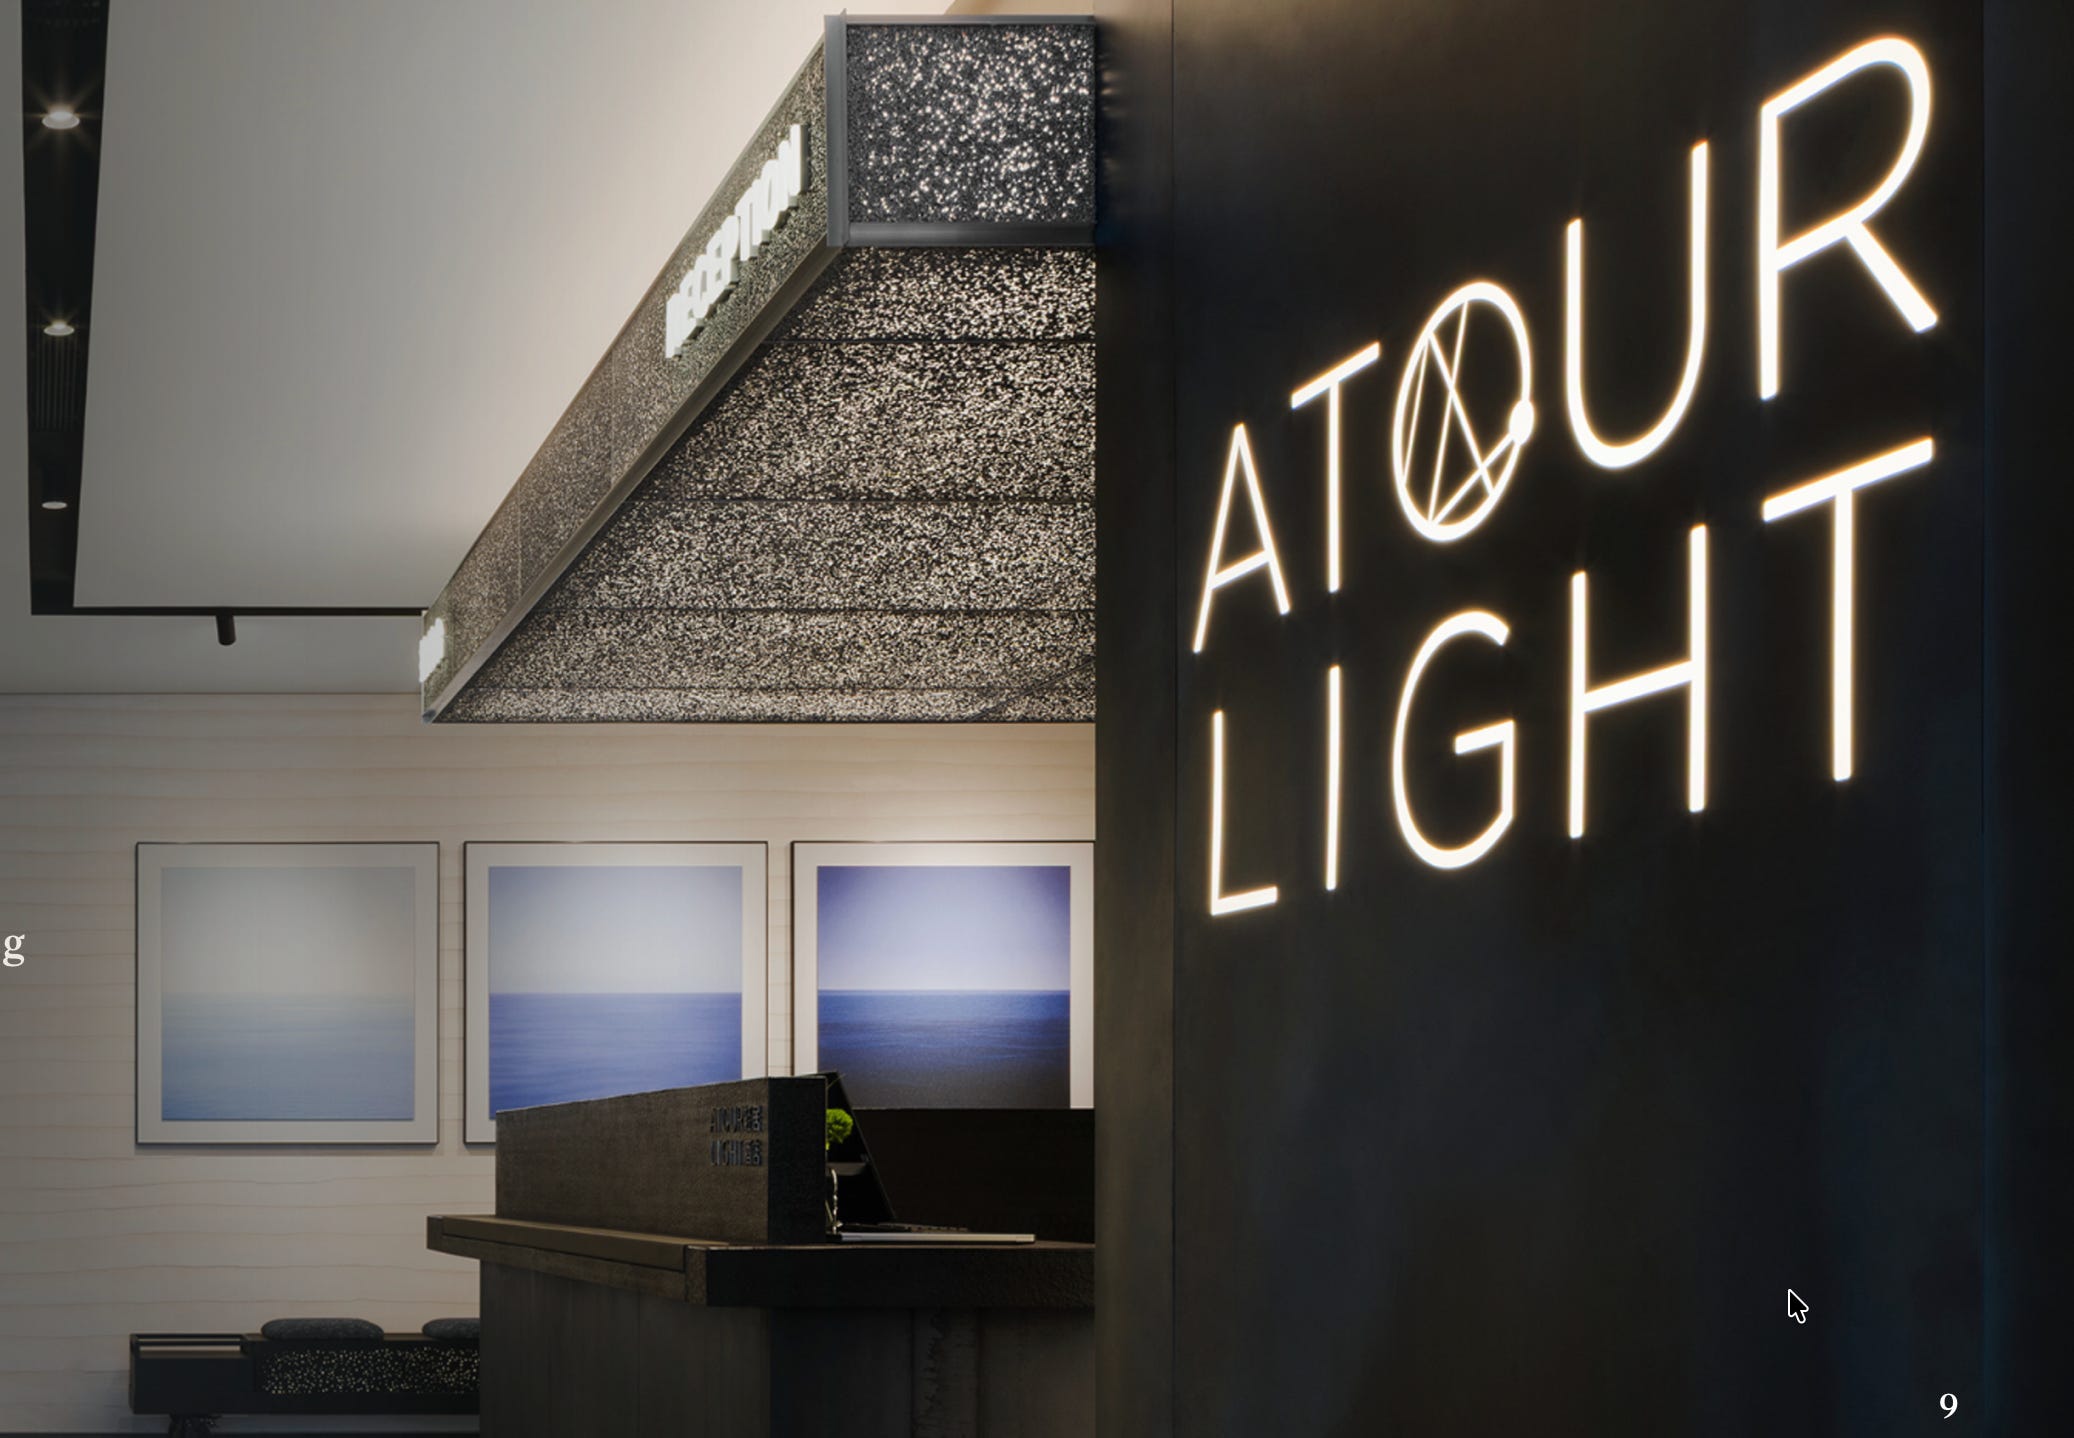
Atour Lifestyle combines an asset-light Chinese hotel franchise network with Atour Planet sleep-product sales, using guest rooms as product…

Bumble agreed to a $6.05-per-share cash sale to Ithaca Holdings, 136% above its October 2 share price.
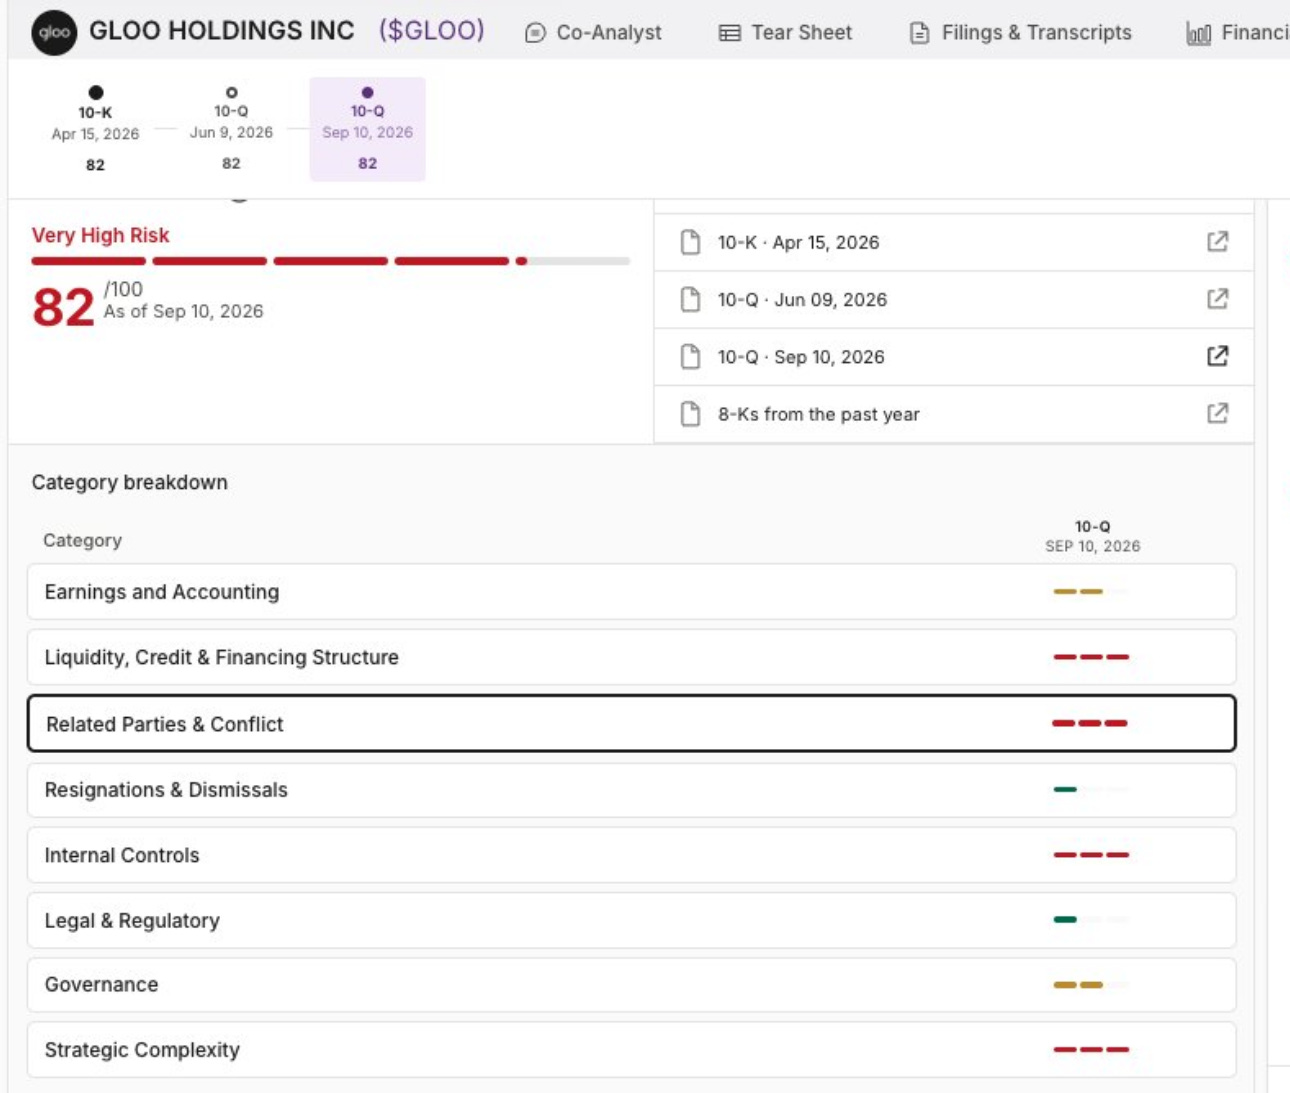
Gloo faces related-party deals, insider-heavy IPO ownership, acquisition losses and $84.5 million of CEO-backed puts as it burns cash and…
 PropNotes 3 clicks
 PYPD · long
PolyPid, an $80 million Israeli biotech, fell nearly 30% despite solving a clinical problem.
 The Undercovered Dozen 17 clicks
Solstice, Albertsons, Brockhaus and GM anchor a 34-case survey of activism, buybacks, M&A and strategic reviews, led by Starboard’s…
Sagimet Biosciences' denifanstat enters a fully funded U.S. acne registration trial after Phase 3 results, with SGMT trading below cash and…
 Equity Eagle 3 clicks
Silvercorp’s falling Ying grades, prolonged GC suspension, El Domo execution risk and Chaarat funding needs weaken its valuation despite…
Vicor’s $66.6 million in AI power-delivery royalties generated about $50 million of operating profit, eclipsing its module business as…
CareCloud may attract a private-equity buyer after its Q3 call, with acquiring enough shares the main obstacle to a take-private deal.
Novo Nordisk has only floated hair loss, while Veradermics’ Phase 3 oral minoxidil data lead a field of licensing and takeover candidates.
AGI Inc trades at 5.6x earnings after a 35% post-IPO decline, despite roughly 30% ROE and resilient INSS payroll-loan growth.
 Multiplo Invest 14 clicks
CoreWeave and neocloud peers face financing pressure, but sold-out GPU capacity and rising H100 and B200 rental rates support continued AI…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Ryan Canady
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.