Unicycive (UNCY):
Unicycive’s oxylanthanum carbonate NDA earned a March 25, 2027 PDUFA date after two manufacturing-related rejections, with no FDA clinical or safety concerns.
Unicycive’s oxylanthanum carbonate NDA earned a March 25, 2027 PDUFA date after two manufacturing-related rejections, with no FDA clinical or safety concerns.
$FIRY raises $55m by selling noncore asset. I'm long. https://t.co/GiavAqfObB
@shallowdives1 @peter_mantas Yeah it’s a nice little industry bubble forming. $DNA is also a Shitco
$DNA - Looks like another genetics short too.
Huron Valley Bank to merge into Bank of Ann Arbor. A few $OXBC holders may be pleased to see it transact for 180% of book value. https://t.co/8buSKj0oh2
CareCloud may attract a private-equity buyer after its Q3 call, with acquiring enough shares the main obstacle to a take-private deal.
LCNB’s Q3 2026 net interest income rose 8.6% year over year as the bank beat revenue and EPS estimates, while trading at a 27% discount to…
 Sorrento Research 2 clicks
Lanxess can force Advent to buy at least half its Envalior stake in April 2028, potentially raising about €745 million to reduce net debt.
Eagle Point Credit's NAV is down 25% YTD and shares nearly 50%, while its expense ratio climbed to 9.21% despite a 25% yield.
 Anthony Cataldo 5 clicks
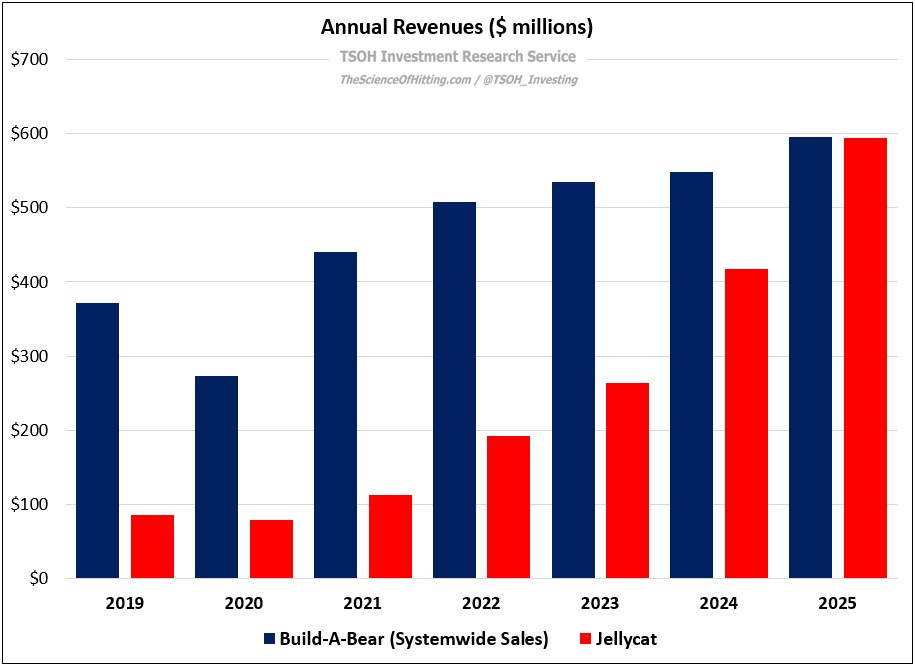
Build-A-Bear's push into prestuffed toys and broader retail distribution tests brand stretchability, but recent results warrant caution.
LendingTree derives roughly two-thirds of revenue from insurance and trades near 4 times expected adjusted earnings despite record revenue,…
First Financial’s merger with First Illinois Financial is expected to lift net interest income and ROE from 2027 after Q2 net income rose…
Sorrento Research 2 clicks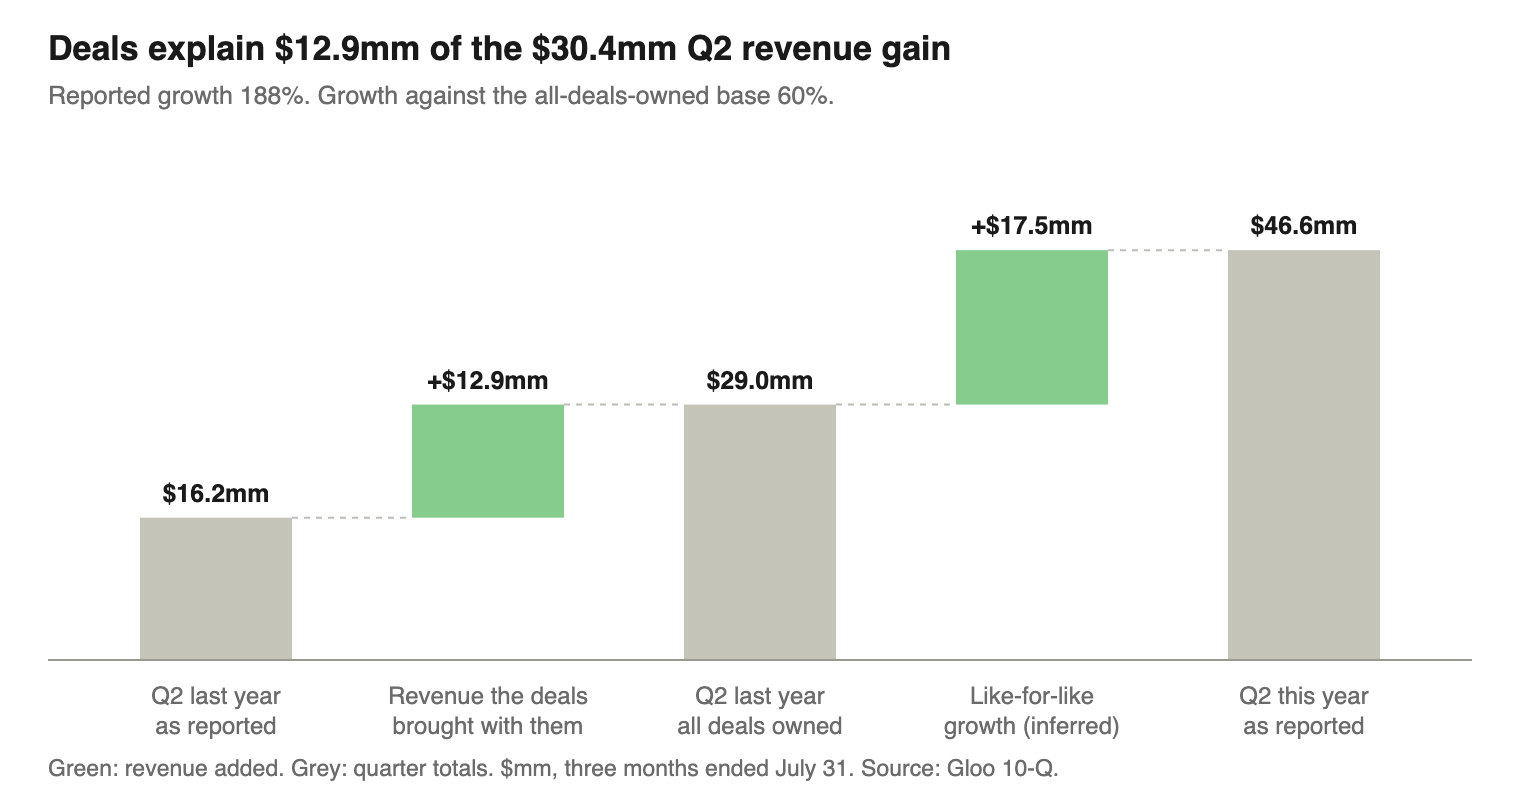
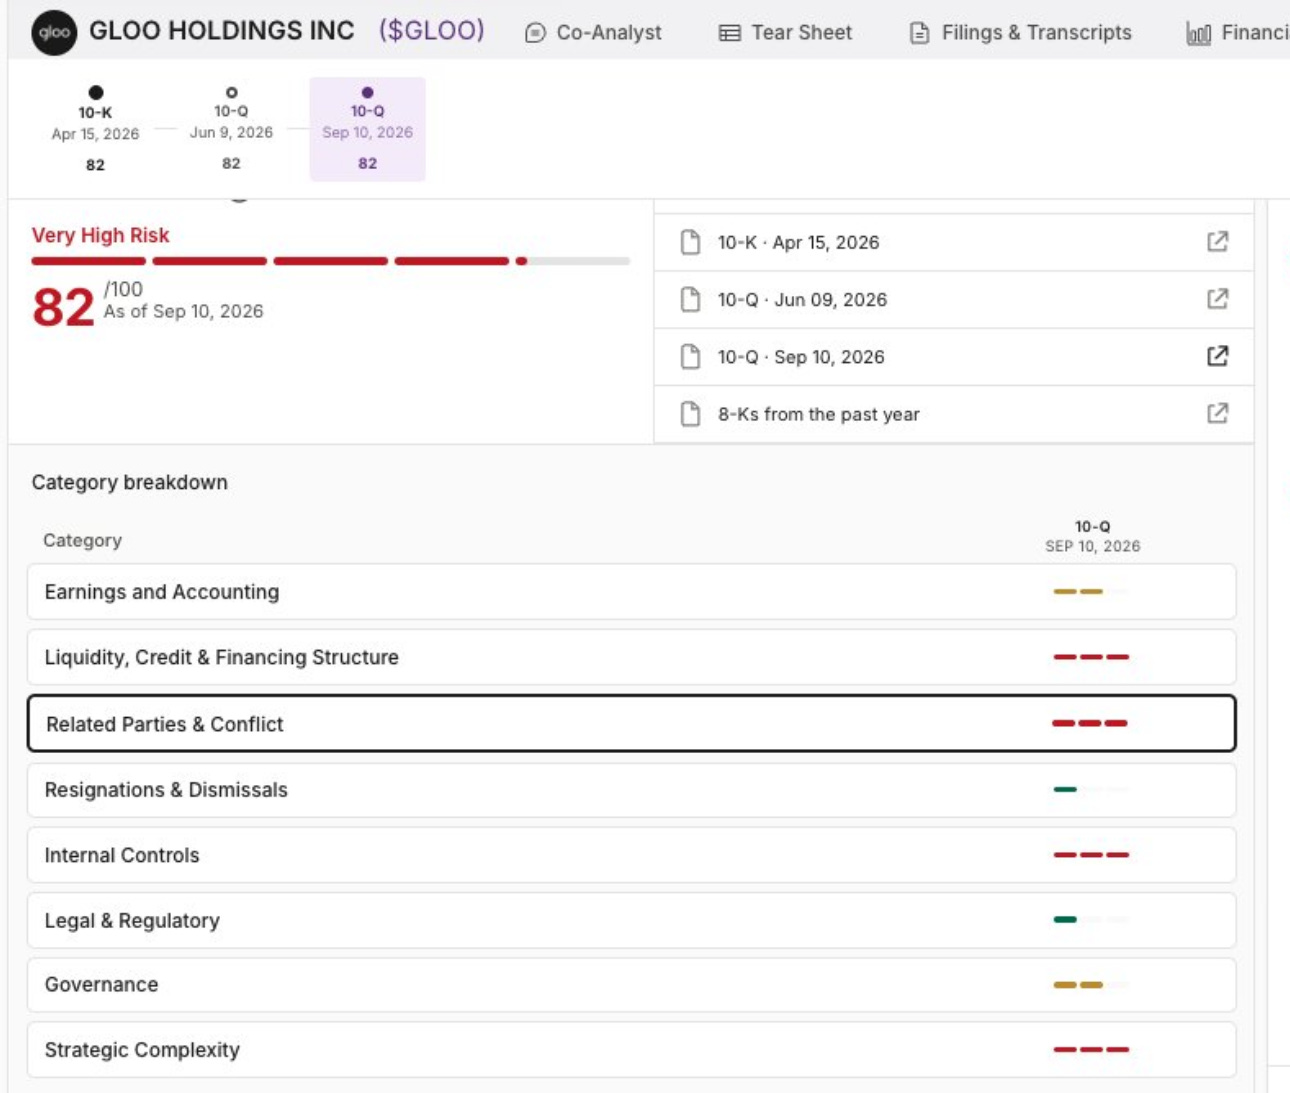
Gloo's $3.25 follow-on, going-concern warning and $28.0 million first-half cash burn frame the short case against its acquisition-driven…
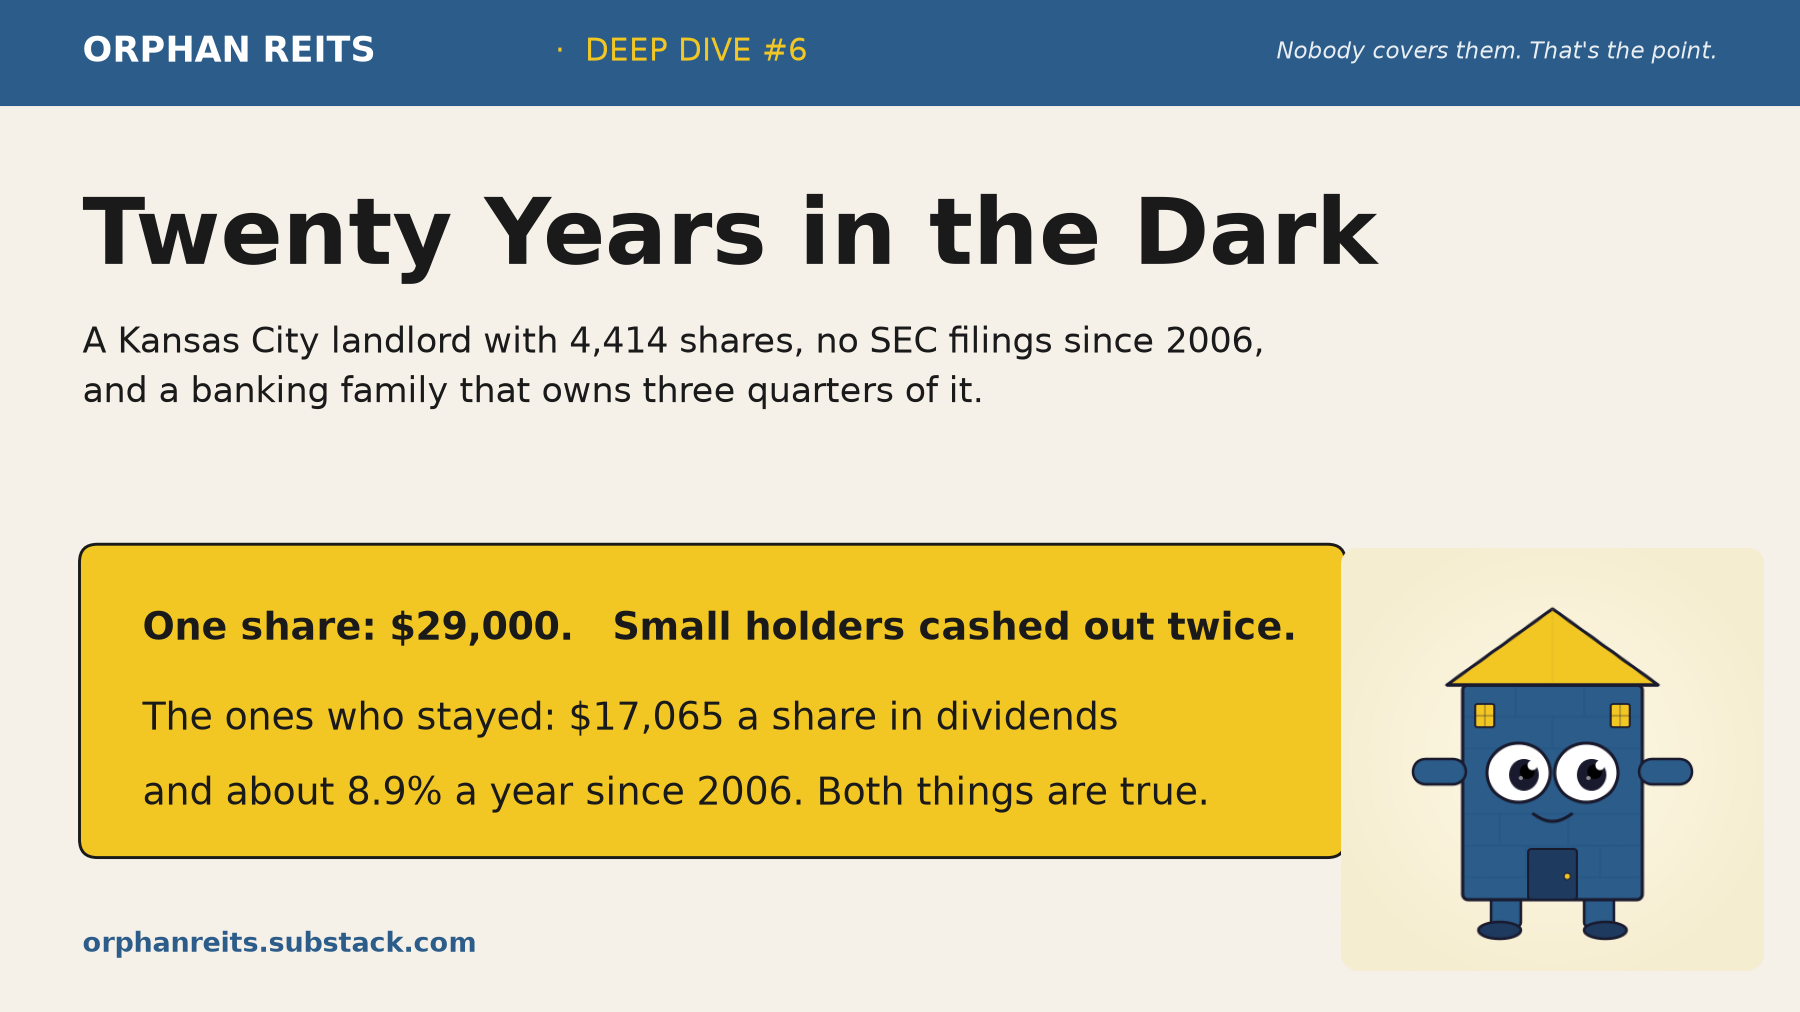
Tower Properties, $TPRP, went dark after a 2006 squeeze-out cut holders below 300, leaving a Kemper-controlled apartment and office…
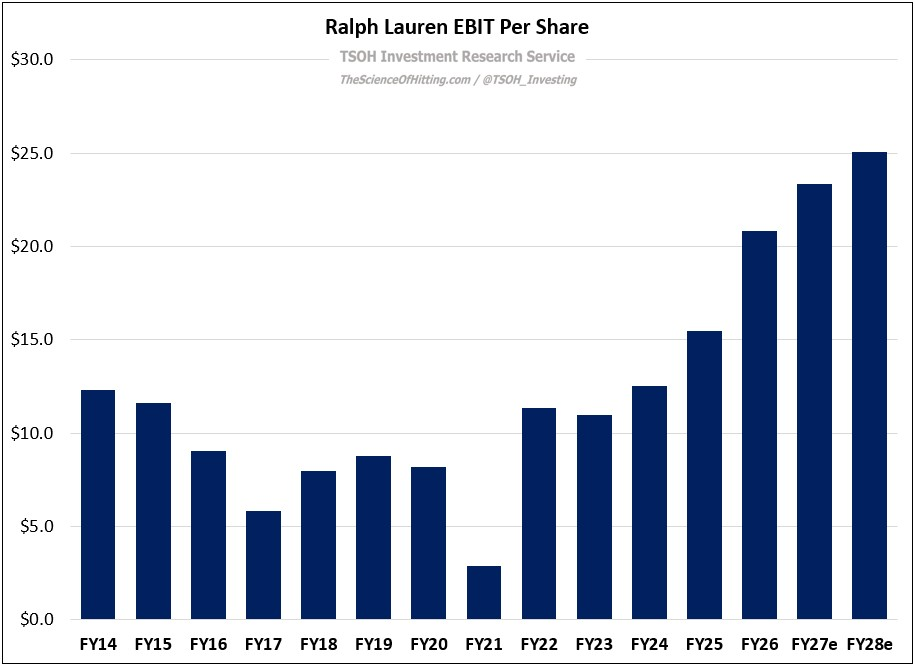
Bumble agreed to a $1.3 billion take-private deal, while Netflix cut about 1,000 jobs and Meta discussed its Muse superintelligence models.
 UNCY · long
Unicycive Therapeutics fell nearly 50% after a second FDA Complete Response Letter tied to a third-party manufacturer for its primary…
Dream Finders Homes’ controlling owner borrowed against DFH stock before the homebuilder agreed to finance an acquisition with costly…
Park Aerospace’s 11% Q2’27 sell-off overlooks sole-source PAC-3 rocket-motor materials and A320neo engine composites, with missile capacity…
FlyExclusive posted 22% Q2 revenue growth and a 20.4% gross margin, but negative free cash flow, net debt and preferred capital leave…
 Dhierin Bechai 1 click
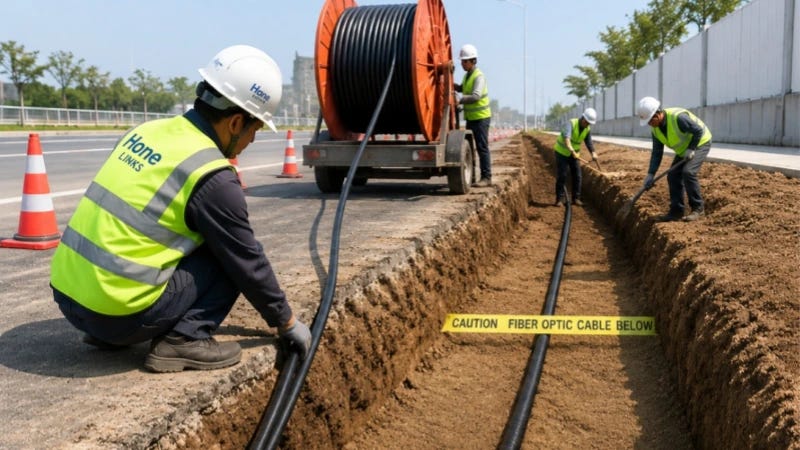
Shenandoah Telecommunications’ Glo Fiber buildout ends this year, and private infrastructure investors’ repeated fiber deals frame a…
El Pollo Loco plans 18 to 20 FY26 openings, including 15 franchised New York stores over five years, as asset-light expansion and…
 Pedro Goulart 1 click
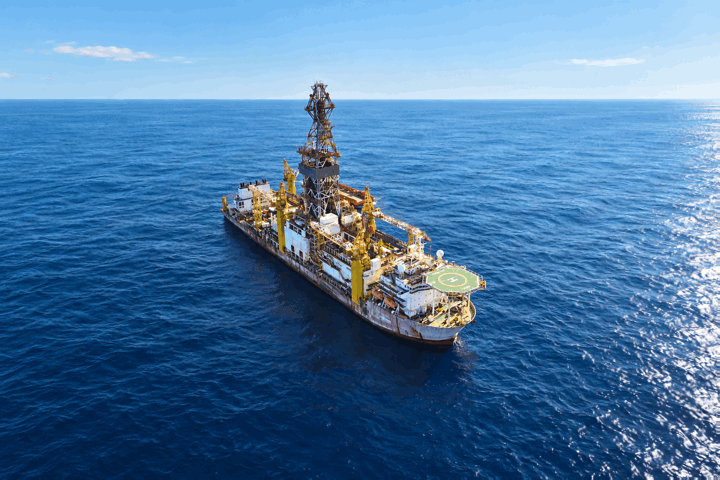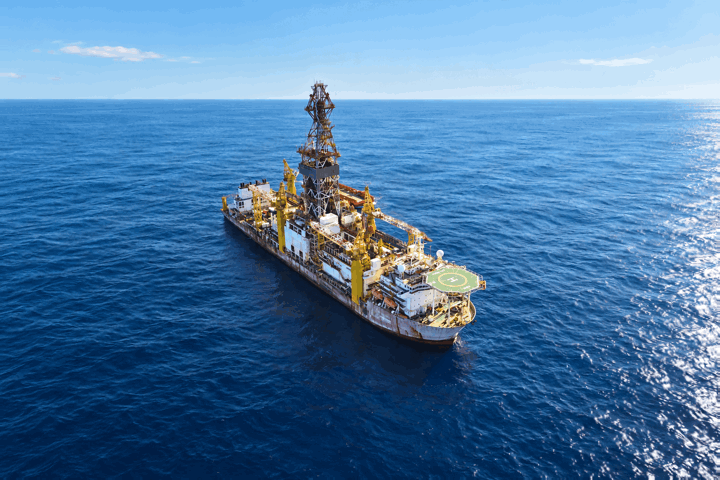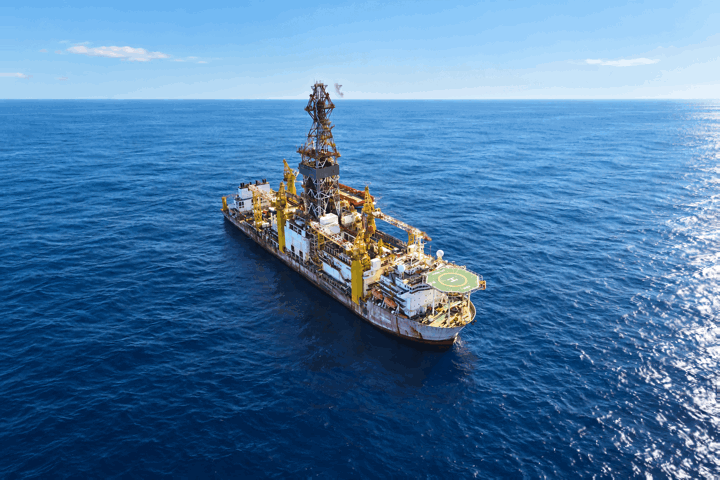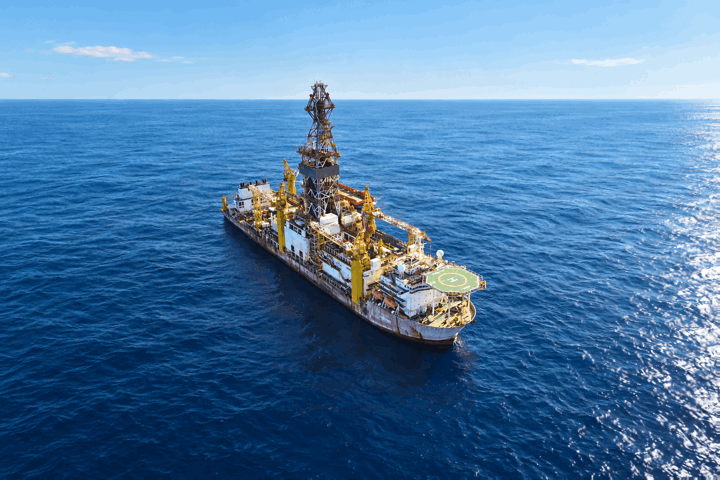
SED Energy's proposed Ventura merger projects a 22% to 40% dividend yield, but idle tender barges, debt and repayments materially reduce…
Park Aerospace reported 27% revenue growth and 72% EPS growth, supported by composite materials for Airbus engines and PAC-3 rocket motors.
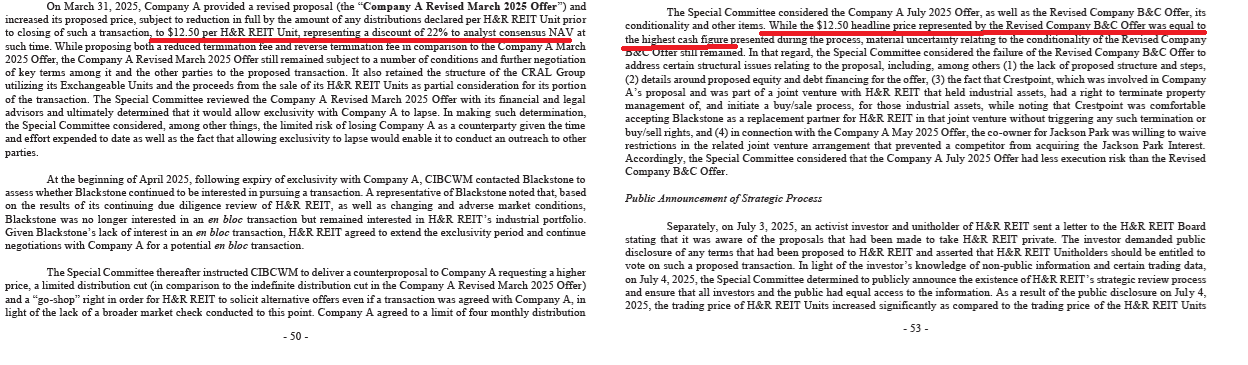
H&R REIT's proposed GO Residential transaction faces investor opposition over rejected $12.50 cash bids, insider benefits and tax…
Helus Pharma's HLP003 Phase 3 depression data is due in 4Q26, with $166.4 million in cash and dilution risk from a $100 million ATM…
 Petri Dish Reports 3 clicks
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Ryan Canady
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.