SiriusXM: Dirt Cheap, Looming Catalysts, Short Squeeze Candidate
SiriusXM trades at 6.5 times free cash flow, a 15% yield, with high short interest and catalysts that could drive a short squeeze.
SiriusXM trades at 6.5 times free cash flow, a 15% yield, with high short interest and catalysts that could drive a short squeeze.
Evercore appoints co-presidents for the first time in leadership reshuffle $EVR https://t.co/XTqr3gW9jX
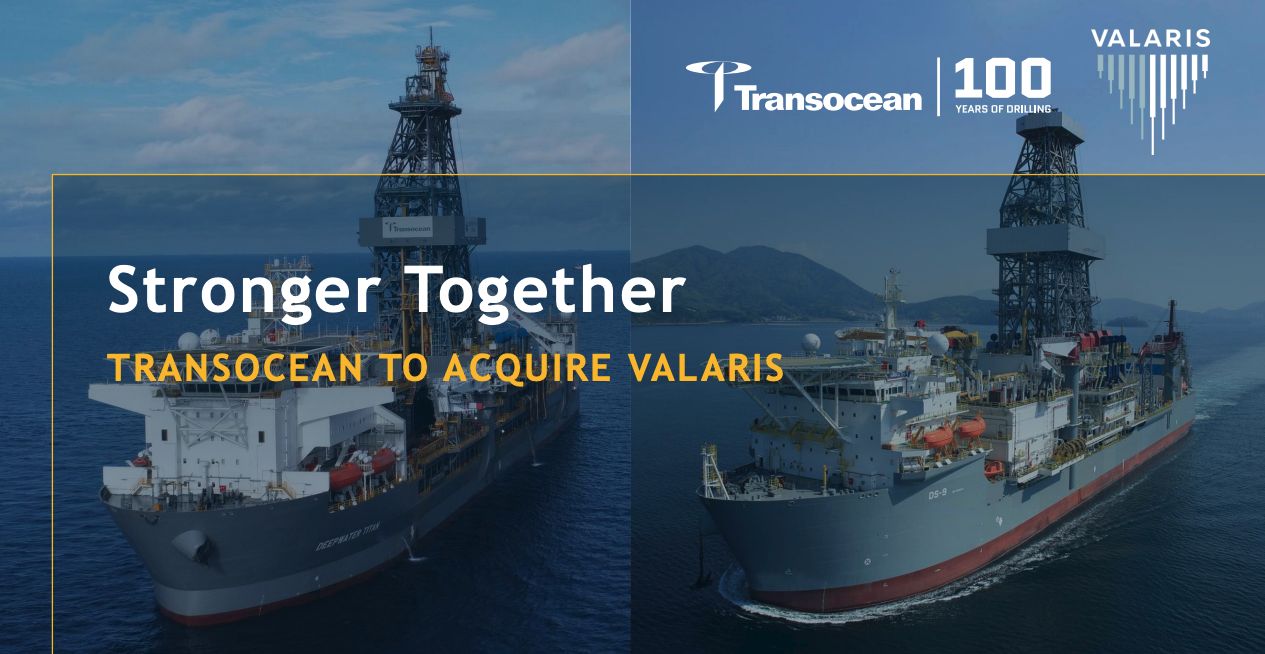
Transocean’s Valaris merger clears regulators, creating a 68-rig offshore driller controlling four in 10 global drillships.
October 2026 market commentary covers SOLS’s cancelled merger, a hypothetical Starbucks-Chipotle deal, Russell 2000 weakness and AI…
Peabody Energy’s recovery case hinges on Centurion, coal-market leverage, capital allocation and balance-sheet strength amid commodity…
 CAN Analyst 1 click
CarGurus, the largest U.S. auto-shopping marketplace, trades near $29 despite roughly $1 billion in expected revenue, $300 million in free…

Charles Lemonides argues the 18-year bull market has not reached its late-stage liftoff, pairing value-oriented semiconductor longs with…
Bristlemoon Global Fund lost 8.4% in the September quarter and added shorts in Campbell’s, REA Group, MasterBrand and Polaris amid narrow…
Liquidia’s Yutrepia sales reached $170.4 million in Q2 2026, while a patent ruling threatens its PH-ILD label but leaves PAH sales and a…
Cognex expects 15% revenue growth this year as its RealSense acquisition expands machine-vision exposure to robotic perception, logistics,…
 Fountainhead 2 clicks
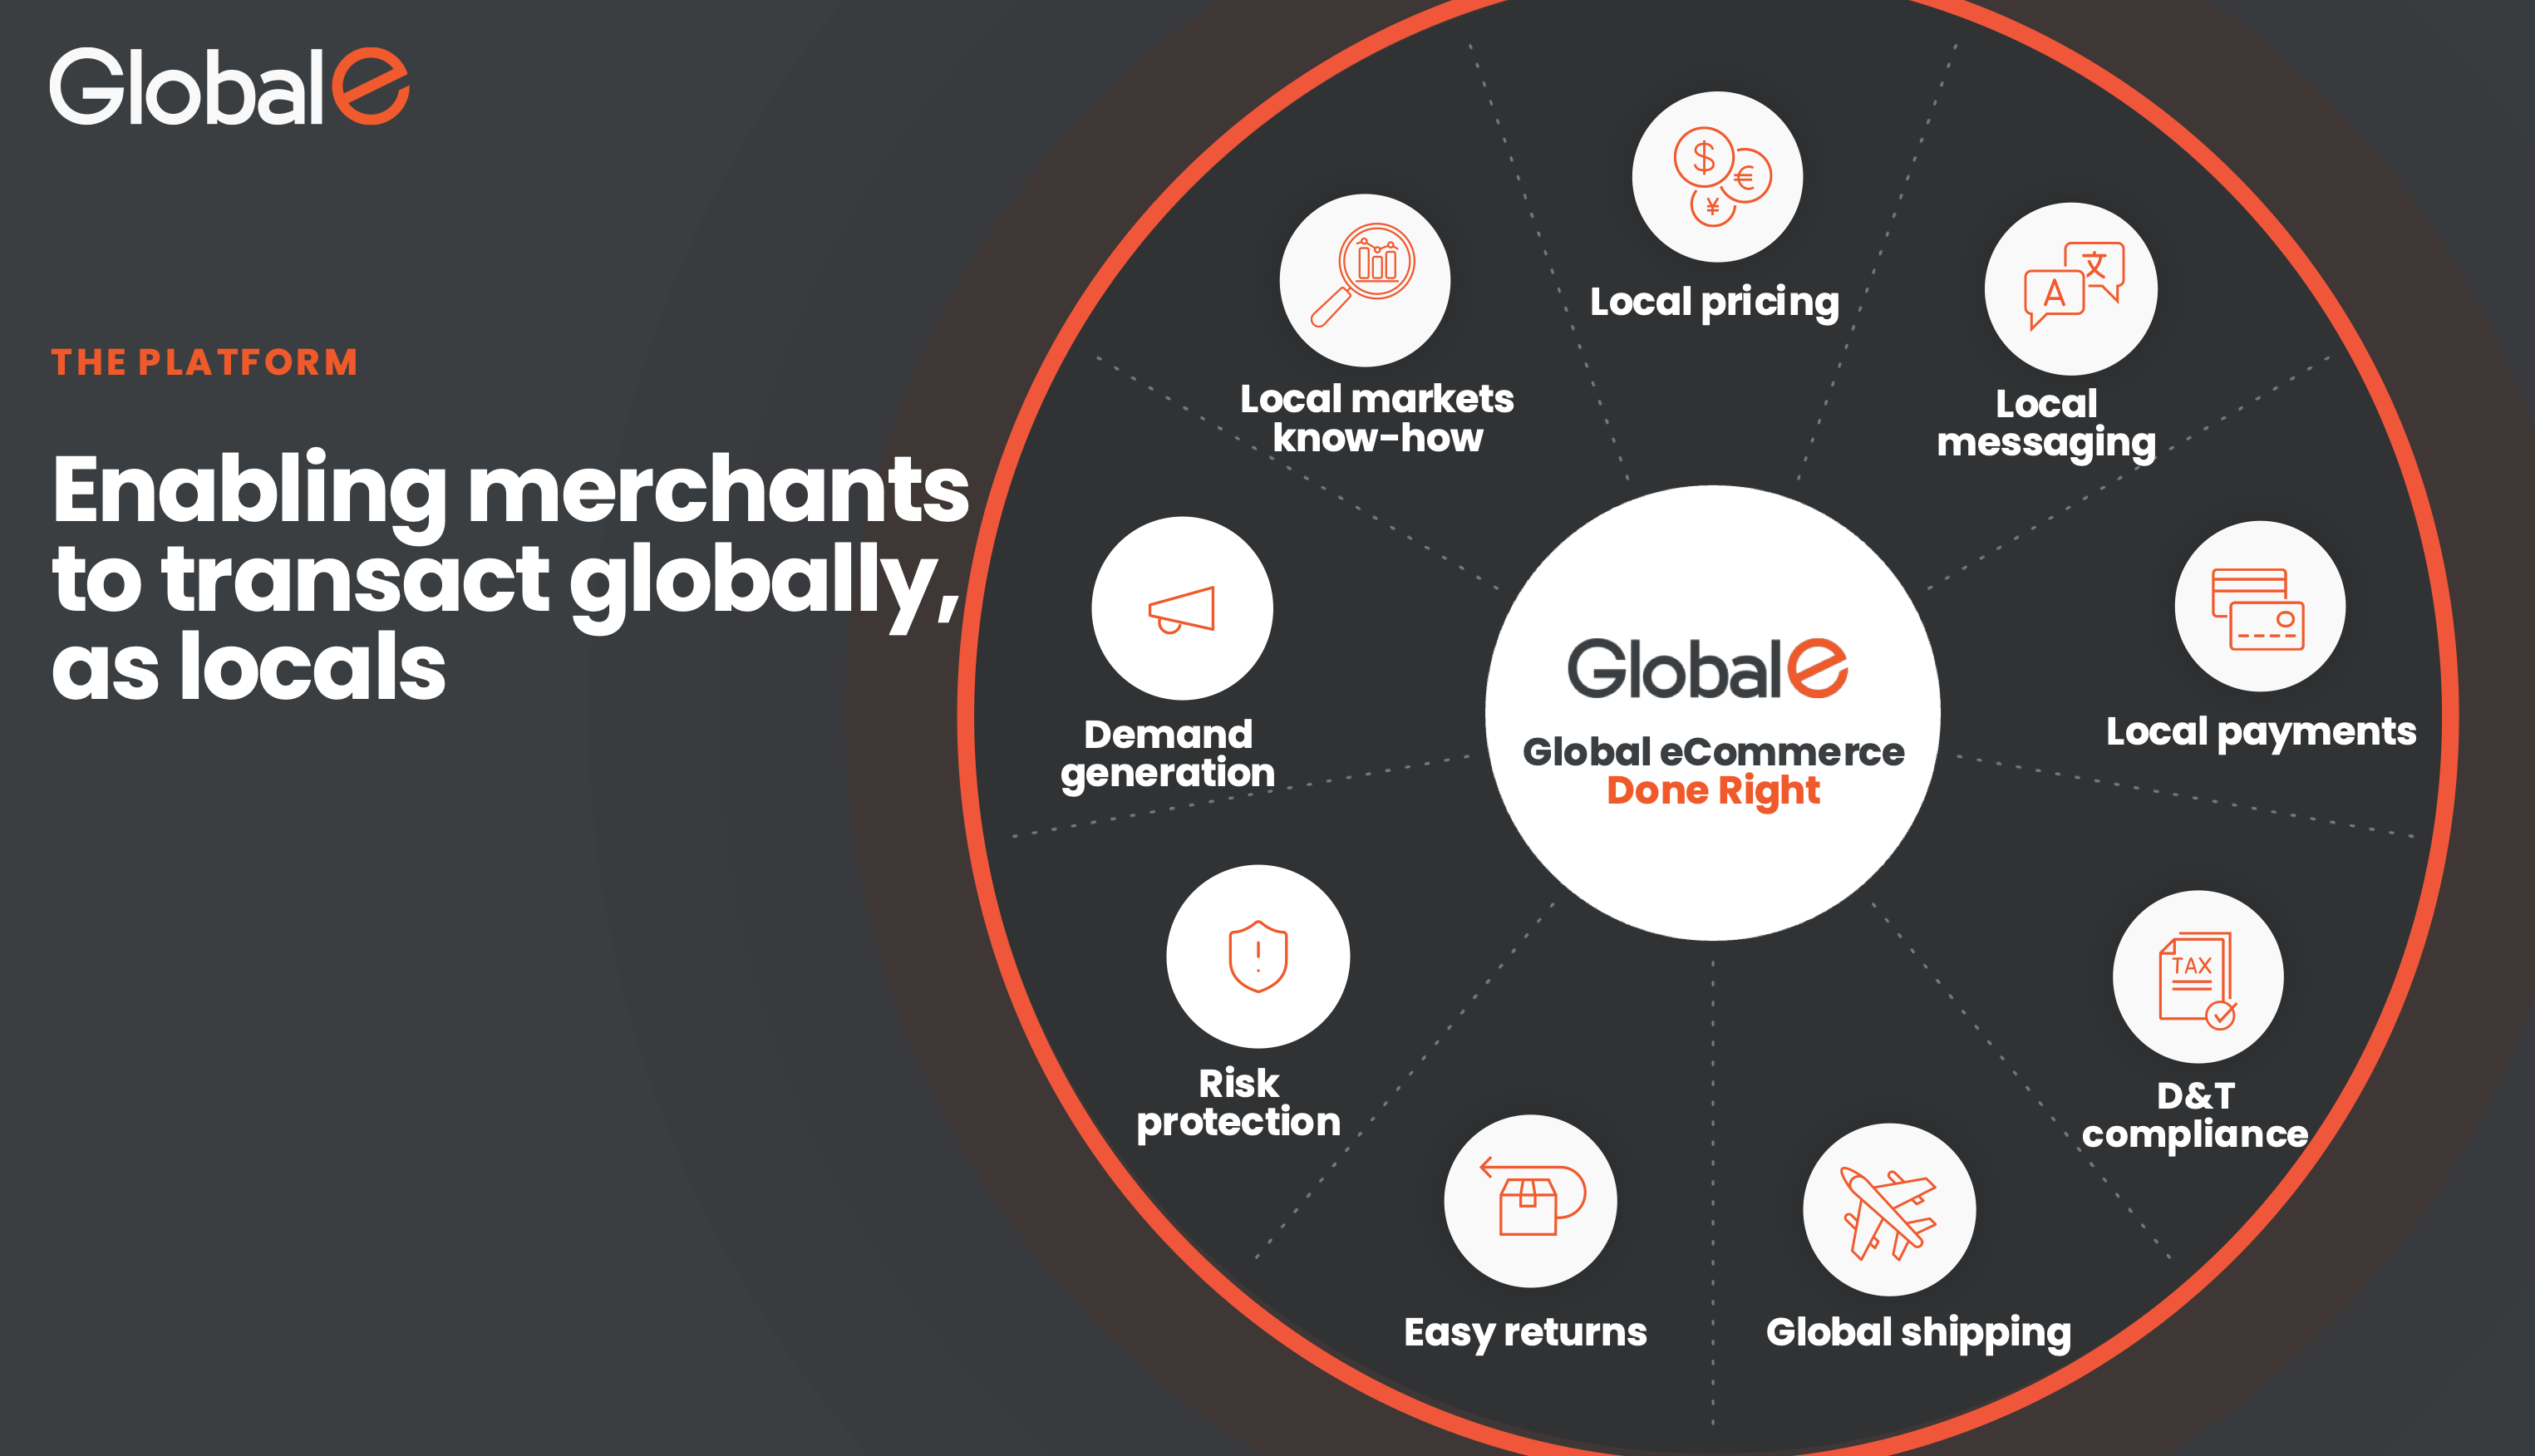
Global-e provides cross-border merchant-of-record, payments, tax and fulfillment services to more than 1,500 brands, including Shopify…
Penguin Solutions grew FY2026 revenue 26% as AI data-center and memory demand expanded, while negative free cash flow and cyclical memory…
 Investor Overview 5 clicks
 ELALF · long
El Al Israel Airlines, $ELAL, cut costs 20% in its 2020 COVID restructuring and was taken over by U.S. investors.
Corteva will spin off its Pioneer seed business, Vylor, on October 1, leaving crop protection RemainCo that could trade at 6.5-8.5x 2026…
CoStar spent more than $1 billion building Homes.com to challenge Zillow, betting seller-agent leads, proprietary listing content and…
Crocs, CNX and Group 1 are tested against Dillard’s buyback-driven share-count reduction, with Group 1 leading and CNX’s convertible notes…
Vail Resorts, down 60% since 2022, is pitched for an El Niño-driven ski-season rebound; the portfolio also buys ORR and shorts GEO.
Crocs CEO Andrew Rees turned around the core brand, then borrowed $2 billion for HEYDUDE, whose $737 million write-down followed wholesale…
Karman Holdings (KRMN) is upgraded after a 68% drop, with 24% organic growth, a $1.3 billion backlog and higher 2026 guidance offset by…
 Dhierin Bechai
Ultra Clean Holdings targets a $4 billion annualized revenue run rate by H2 2027 through manufacturing expansion and a broader…
STMicroelectronics, Navitas and Wolfspeed offer contrasting power-semiconductor cases tied to NVIDIA’s 800V AI data-center architecture,…
Offshore drillers have secured 105 rig-years by September, 42% above all of 2025, as national oil companies lock up long-term capacity.
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing Dhierin Bechai
 Dilantha De Silva
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.