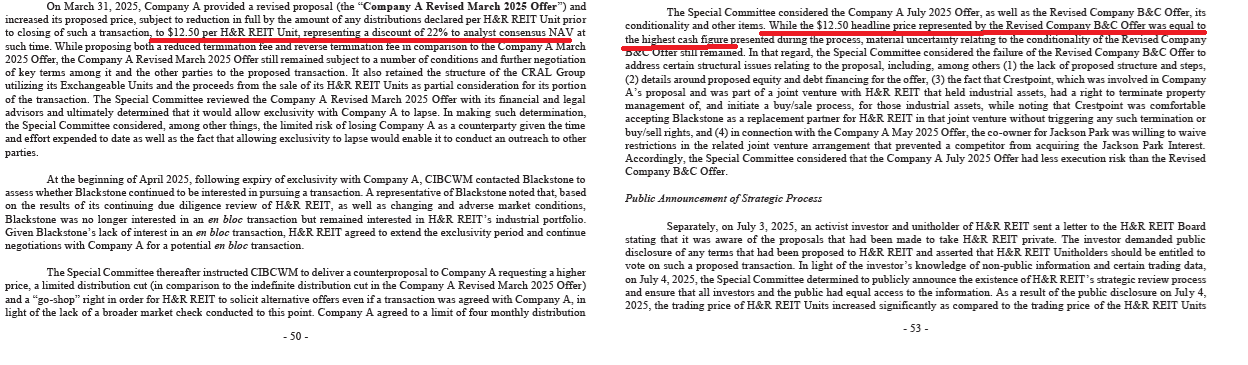
H&R REIT's proposed GO Residential transaction faces investor opposition over rejected $12.50 cash bids, insider benefits and tax…
S Nugget Capital Partner's Substack 2 clicks
Helus Pharma's HLP003 Phase 3 depression data is due in 4Q26, with $166.4 million in cash and dilution risk from a $100 million ATM…
SA  Petri Dish Reports 3 clicks
Hippo’s insurance platform posted 61% premium growth, a 95.8% combined ratio and a fifth profitable quarter as it shifted toward carrier…
S Substack von Philipp 8 clicks
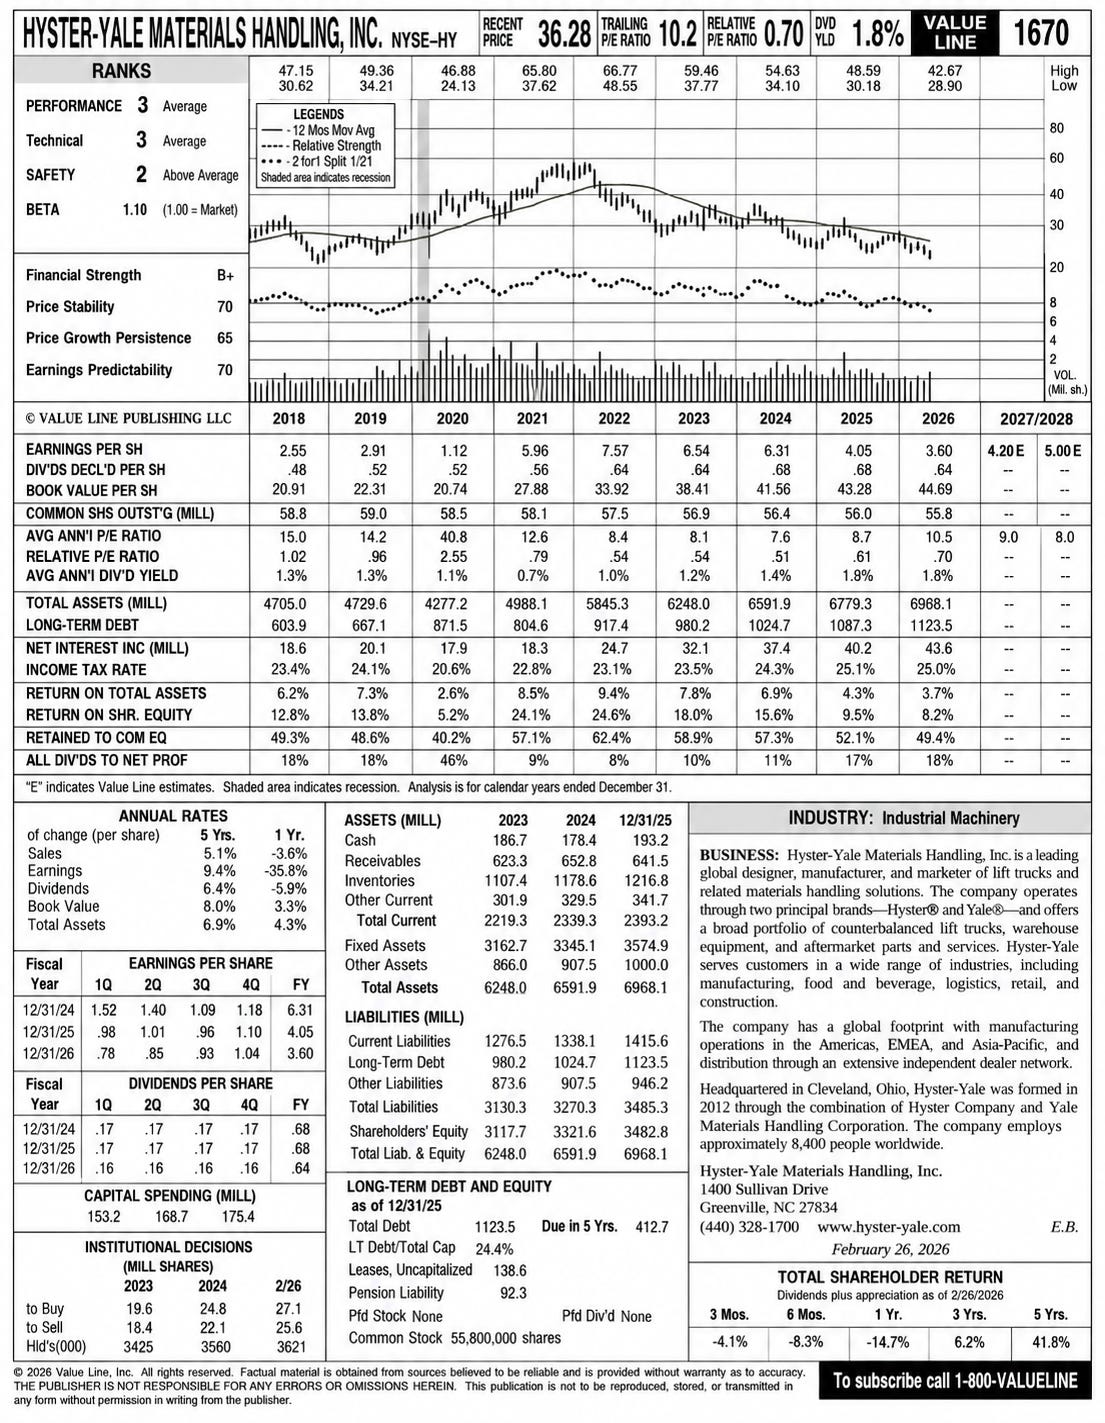
Hyster-Yale trades at 0.16 times sales as lift-truck bookings rebound and restructuring targets $85 million to $100 million in annual…
S Calvin Blissett 3 clicks
Lesaka CEO Ali Mazanderani has bought more than $10 million of stock while pursuing a $20 to $30 valuation case through targeted…
S Mispriced Assets 5 clicks
Cogent Communications and AI data-center bottlenecks feature in a newsletter update on recruiting, financial media and conference takeaways.
S Stock Thoughts 4 clicks
Lesaka’s executive chairman has invested more than $10 million personally and targets EPS compounding above 40% through consumer, merchant…
S Mispriced Assets 2 clicks
VersaBank's Q3 revenue rose 23% and adjusted net income 27%, while a 2.19% net interest margin and 19.15x forward earnings temper its 2027…
SA  Grassroots Trading 2 clicks
MGP Ingredients trades at 0.74 times tangible book after whiskey oversupply drove sales declines and more than $400 million of impairments.
S Dismissed & Asset-Backed 1 click
Solid Power reported a $0.11 Q2 loss and $419.3 million of cash, with its electrolyte pilot line and BMW and SK On validation central to…
SA  Quad 7 Capital 2 clicks
 SRTA · long
Strata Critical Medical, SRTA, supplies organ-transport products tied to U.S. transplant growth.
BL Value Investors Club 3 clicks
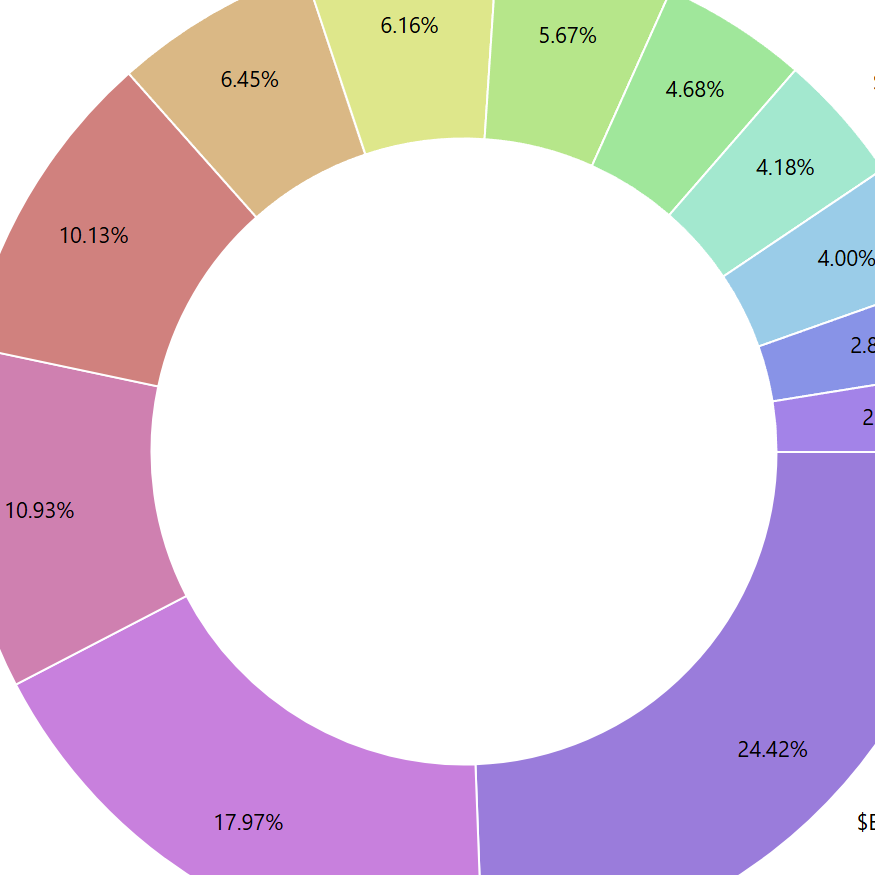
Entravision, the portfolio’s largest position, fell more than 40% from its highs as Q3 returns dropped to 37.8% YTD.
S The Mikro Kap 5 clicks
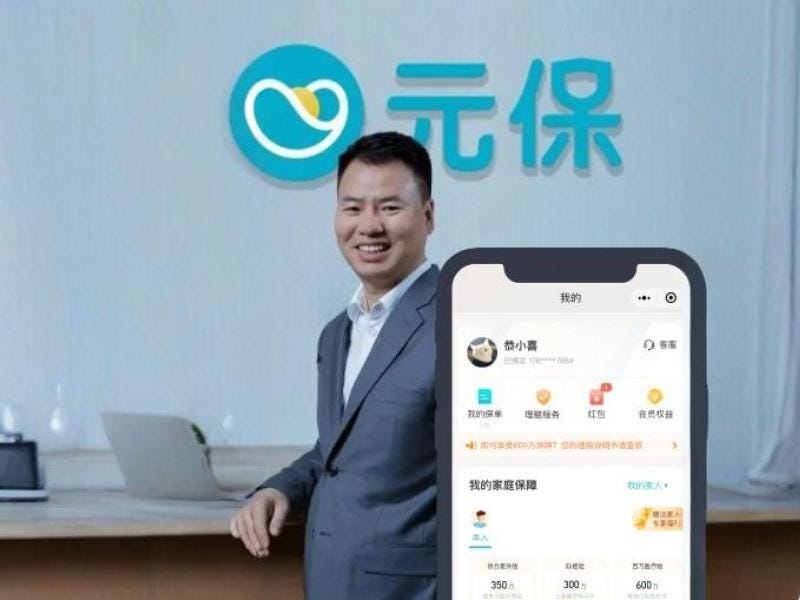
Yuanbao pairs a 10.2% dividend and cash exceeding its market value with 33.5% first-half profit growth from AI-enabled Chinese insurance…
S Calvin Blissett 4 clicks
Stratus Properties liquidates Austin real estate below projected distributions, while Atlantic Lithium and Intermex await approvals for…
S Triple S Special Situations Investing
Cullinan Therapeutics plans December 2026 autoimmune updates for CLN-978, while zipalertinib awaits an FDA decision in previously treated…
SA  Myriam Alvarez 2 clicks
VersaBank uses cash holdbacks and put-backs to buy point-of-sale loan cash flows, with C$7 billion in assets and AI-enabled real-time…
S Substack von Philipp 7 clicks
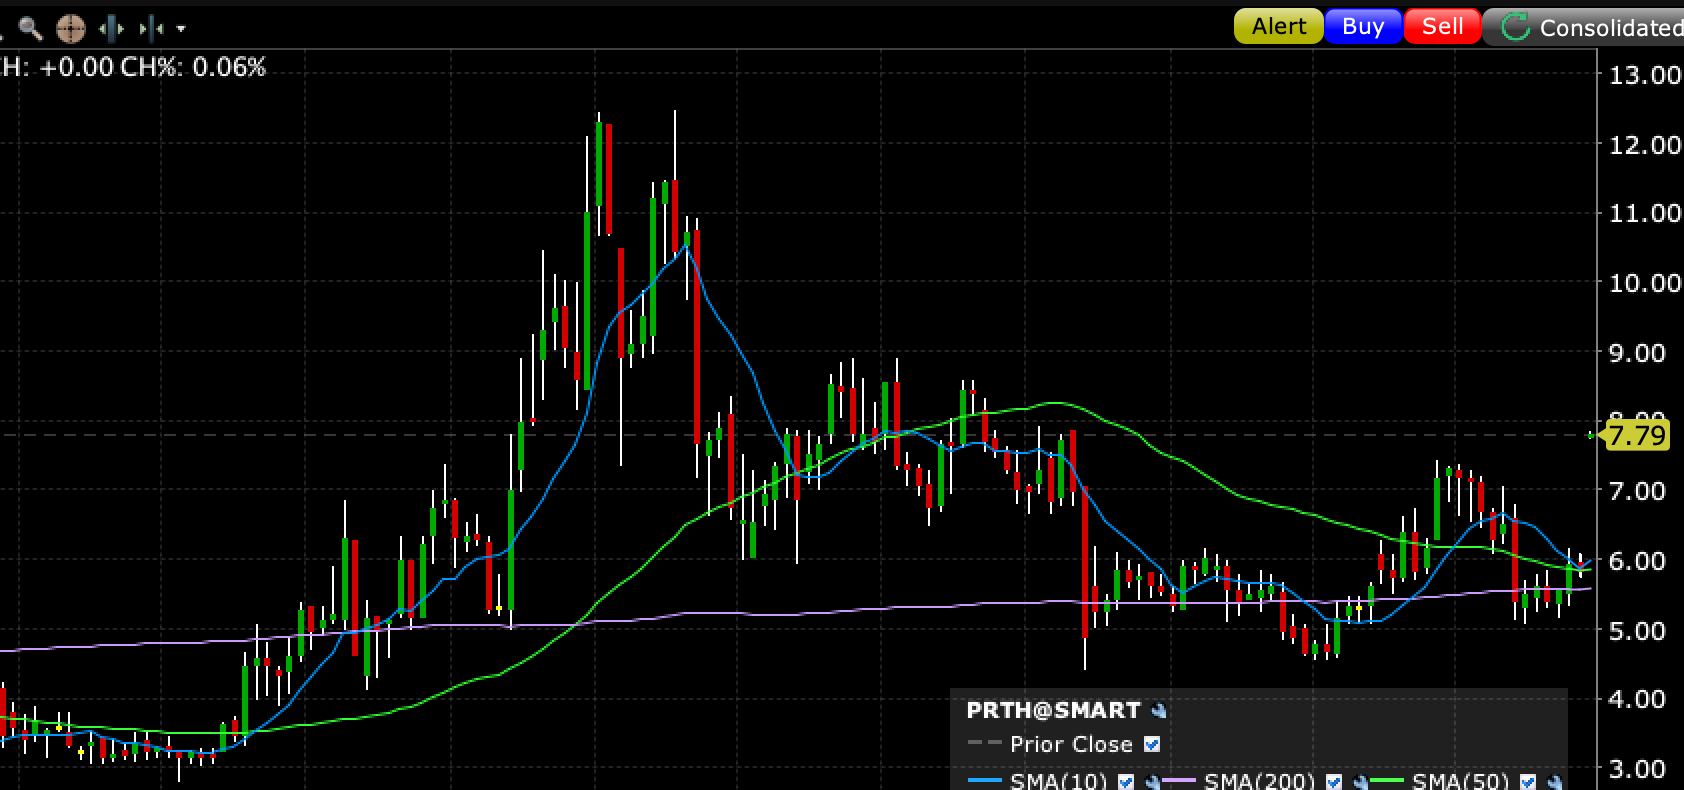
FGPR remains on track, PRTH's management buyout is set at $8.05, and microcap RAVE is described as cheap.
S Nat Stewart - Stock Picking Newsletter 9 clicks
U.S. Treasury yields are testing credit and equity markets, while the discussion also targets recent changes at Glass House (GLAS).
S WHAT ARE WE DOING? “Contrarians At The Gate” 1 click
Kronos Worldwide’s 27% inventory reduction added $120 million in cash inflows as chloride-based TiO₂ demand rises amid a sulfur shortage.
SA  Given Mahlangu
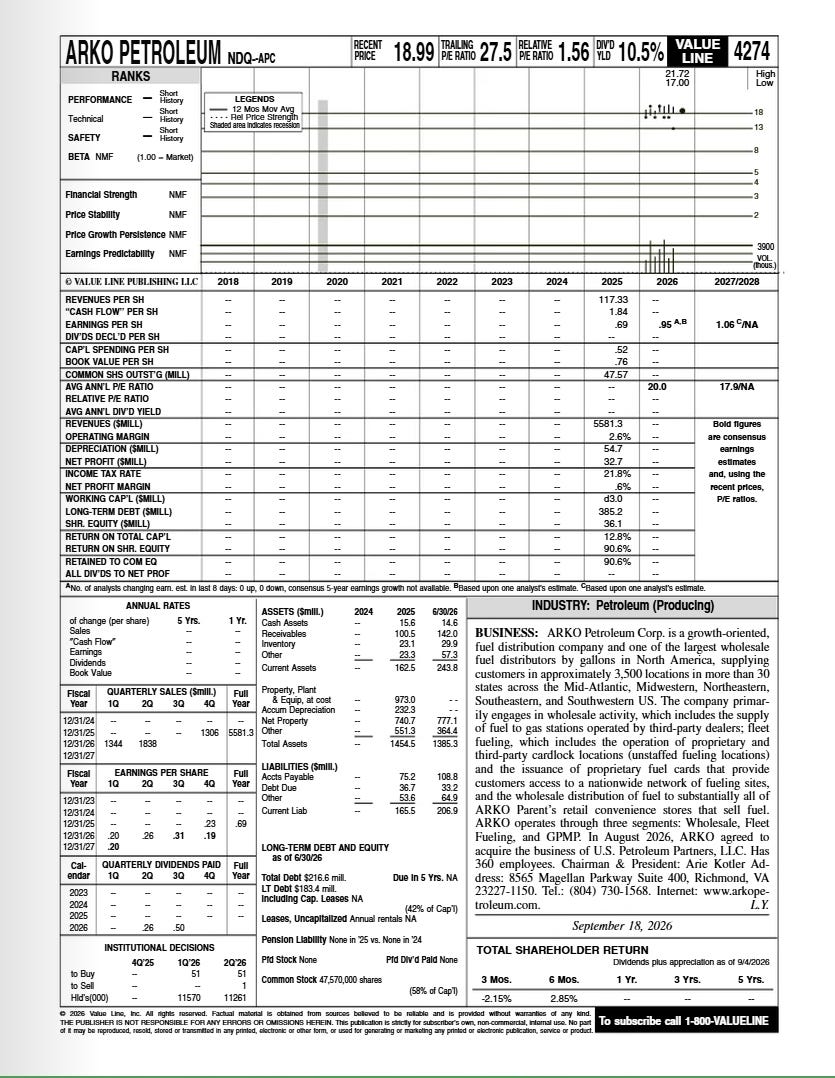
ARKO trades at 3 times estimated 2025 owner’s earnings, while its 73.6% APC stake exceeds its $473 million market cap.
S Calvin Blissett 3 clicks