Hippo Holdings ($HIPO): The Insurtech That Stopped Chasing Hype and Started Making Money
Hippo’s insurance platform posted 61% premium growth, a 95.8% combined ratio and a fifth profitable quarter as it shifted toward carrier and MGA fee income.
Hippo’s insurance platform posted 61% premium growth, a 95.8% combined ratio and a fifth profitable quarter as it shifted toward carrier and MGA fee income.
No clue how this plays out, but $ABG CEO during Q2 earnings what seems to have played out at $AN in Q3... So some of it seems like poor execution/mngmt?
Harley-Davidson $HOG flying into the open as the sell side capitulates into the third straight quarter of positive comps after insisting it was a dying brand for years. Cranking my hog here. https://t.co/OuqRUQIqmq
Prison stocks about to limit up $GEO. https://t.co/GZmGa3E8jh
Seems I quite underestimated mgmt's turnaround abilities at $QMCO back in late April, despite my deep dive. +370% since! 🤔 https://t.co/TaFgHG1Jke
Legence trades at 10.4x EV/aEBITDA with a $5.7 billion backlog, as AI data center installations drive growth and expand its maintenance…
OceanaGold trades below its mine value despite US$655 million of cash and no debt, with production set to dip before Wharekirauponga begins…
 The Bullionaire
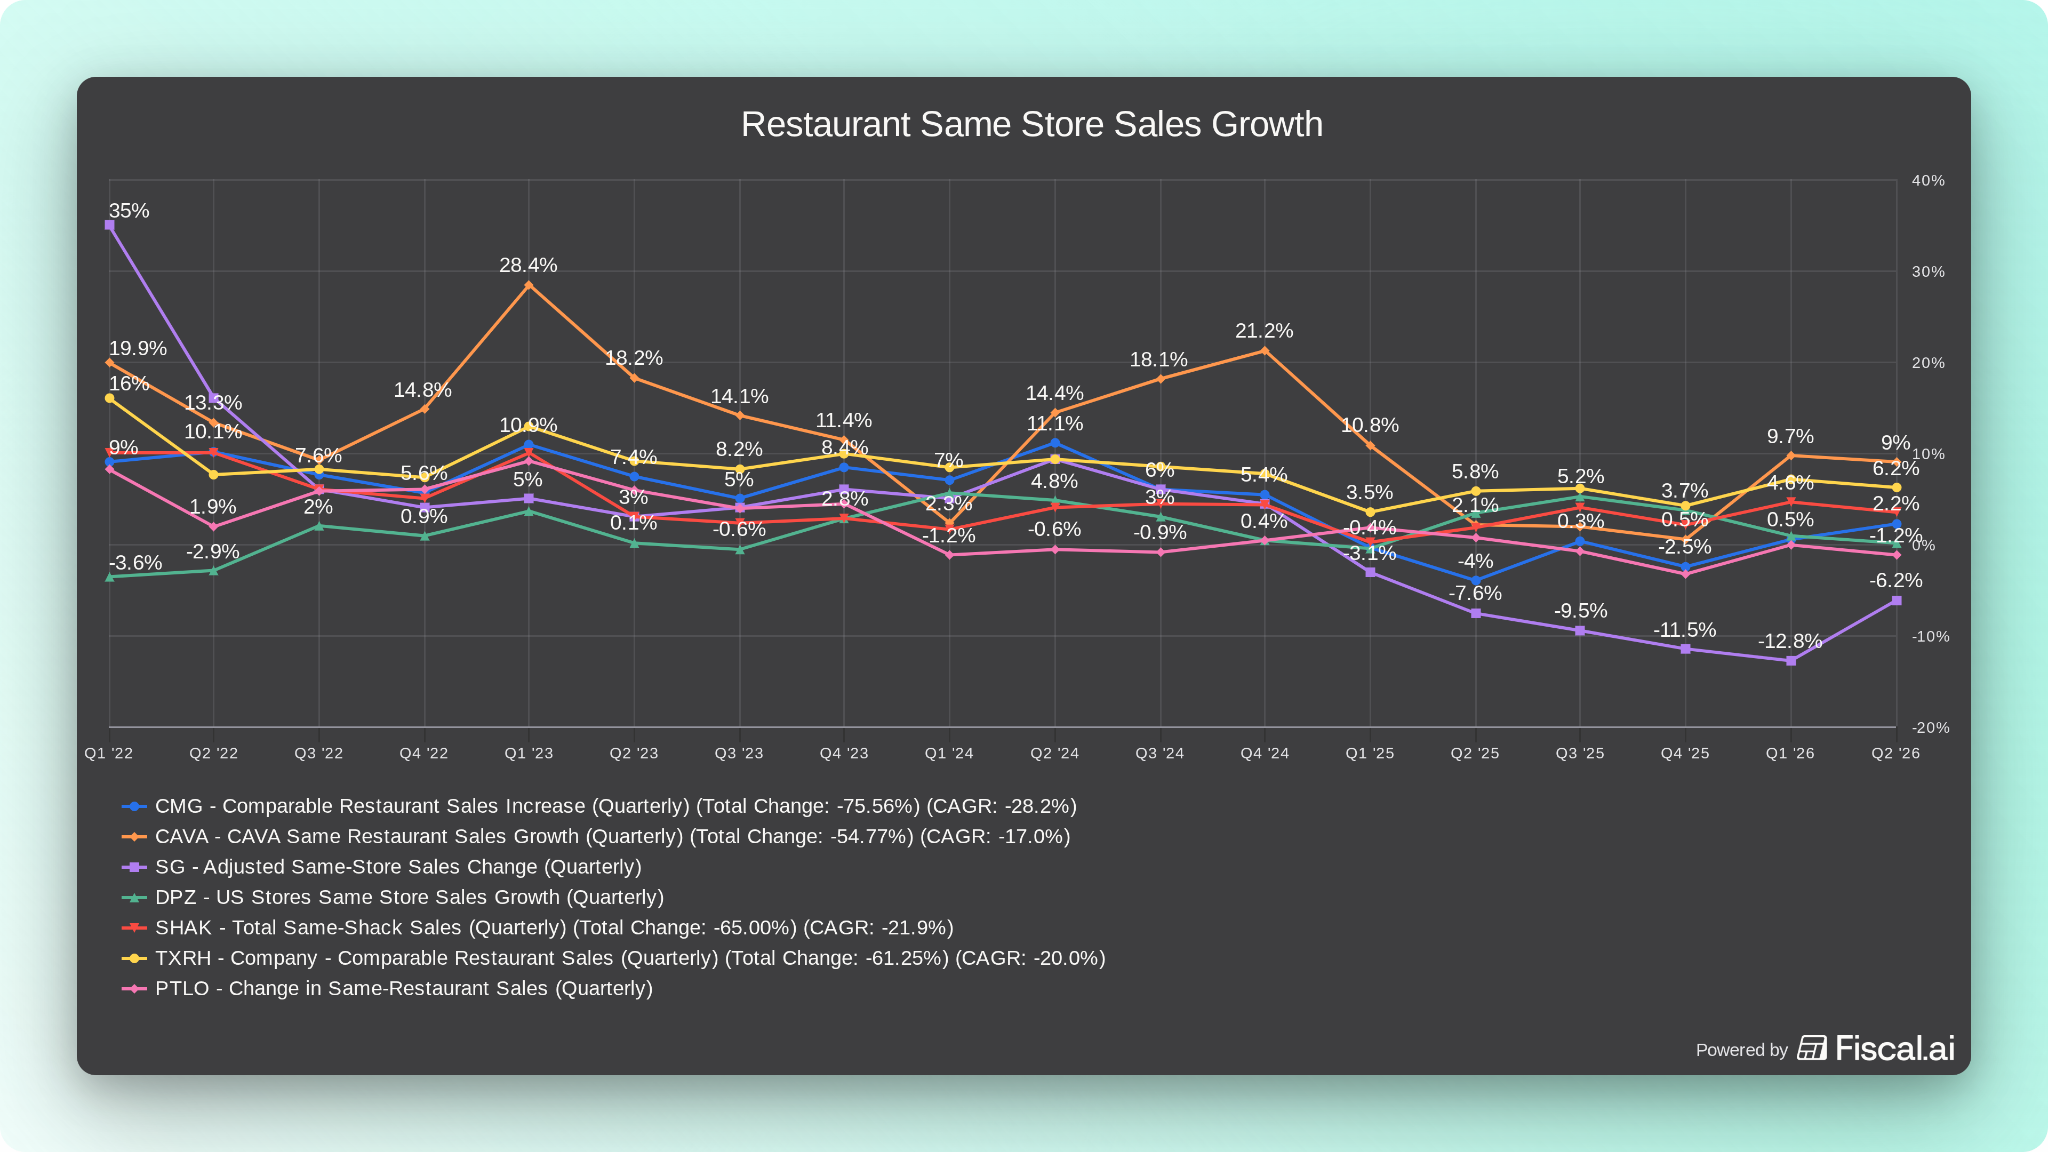
Cava’s $3 million AUVs, 25.1% restaurant margins and sector-leading same-store sales support its expansion case as awareness rose from 40%…
Namib Minerals posted H1 adjusted EBITDA of $19.0 million, up 76%, as higher gold prices offset lower production.
Special-situations survey profiles 26 activist, capital-return, M&A and strategic-alternative catalysts, led by buybacks at Under Armour,…
Millrose told Goldman its Lennar purchases had rent-to-own tenants lined up, but most analyzed homes were advertised for rent and showed…
Golar LNG ordered a $2.45 billion fourth FLNG vessel, targeting 3.5MTPA of capacity and $400 million in annual EBITDA under a 20-year…
Lesaka CEO Ali Mazanderani has bought more than $10 million of stock while pursuing a $20 to $30 valuation case through targeted…
Alamar Biosciences' consumables revenue rose 147% in 2Q26, lifting gross margin to 60% as the company expands into clinical diagnostics.
 Petri Dish Reports
Cogent Communications and AI data-center bottlenecks feature in a newsletter update on recruiting, financial media and conference takeaways.
 BNTC · long
Benitec Biopharma's BB-301 gene therapy is in a Phase 1b/2a trial for an ultra-rare muscular dystrophy.
Blackstone Secured Lending Fund faces a likely dividend cut after its first shortfall in 28 quarters, despite 1.8% non-accruals, $2.8…
 Rubicon Associates
Lesaka’s executive chairman has invested more than $10 million personally and targets EPS compounding above 40% through consumer, merchant…
Salad and Go filed Chapter 11 after its Texas and Oklahoma expansion failed, seeking to sell 65 leases to Dutch Bros for $105 million as 7…
Golar LNG’s fourth FLNG vessel targets 3.5MTPA capacity and a 2029 delivery, supporting projected adjusted EBITDA above $1 billion in…
Group 1 Automotive CEO Daryl Kenningham’s Toyota ties, capital-allocation decisions, compensation and stock sales face scrutiny after the…
Solid Power reported a $0.11 Q2 loss and $419.3 million of cash, with its electrolyte pilot line and BMW and SK On validation central to…
 Quad 7 Capital 2 clicks
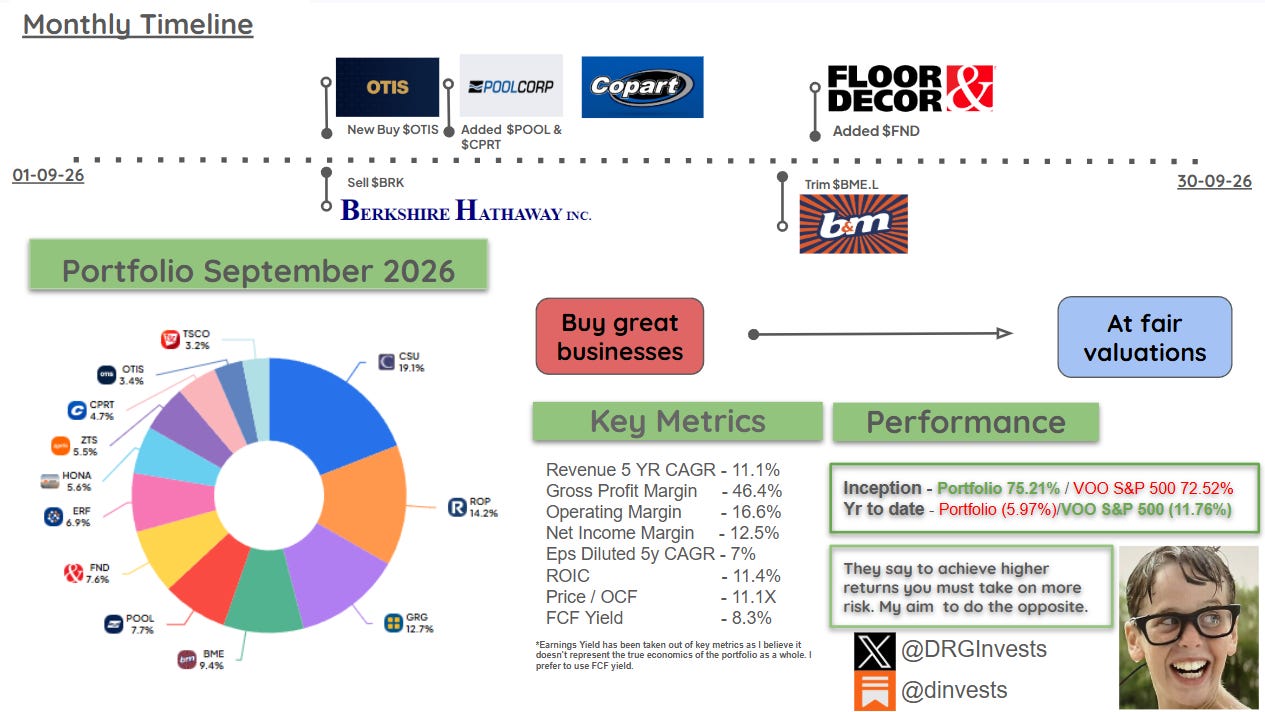
Portfolio added Otis Worldwide in the mid-$60s, increased Pool, Copart and Floor & Decor, and sold Berkshire Hathaway.
Brazilian fintechs NU, INTR and PICS stand to benefit from a Bolsonaro-led runoff surprise that lowers fiscal risk premiums, rates and the…
Nyxoah's Genio implant could reach CCC patients after an FDA label expansion, targeting 30% of the obstructive sleep apnea device market by…
 Stephen Tobin 3 clicks
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.