Lesaka CEO Ali Mazanderani has bought more than $10 million of stock while pursuing a $20 to $30 valuation case through targeted…
S Mispriced Assets Oct 8 5 clicks
Alamar Biosciences' consumables revenue rose 147% in 2Q26, lifting gross margin to 60% as the company expands into clinical diagnostics.
SA Petri Dish Reports Oct 8 Cogent Communications and AI data-center bottlenecks feature in a newsletter update on recruiting, financial media and conference takeaways.
S Stock Thoughts Oct 7 2 clicks
Undercovered Dozen spotlights 12 lesser-covered stocks, including Brookfield Renewable, Annaly Capital and Seagate.
SA The Undercovered Dozen Oct 7 Lesaka’s executive chairman has invested more than $10 million personally and targets EPS compounding above 40% through consumer, merchant…
S Mispriced Assets Oct 7 2 clicks
Salad and Go filed Chapter 11 after its Texas and Oklahoma expansion failed, seeking to sell 65 leases to Dutch Bros for $105 million as 7…
S PETITION Oct 7 3 clicks
Astronics targets $1.02 to $1.04 billion in 2026 revenue after adjusted operating margin reached 20.3%, with Boeing representing 12% of…
SA Jordan Aquilina Oct 6 Golar LNG’s fourth FLNG vessel targets 3.5MTPA capacity and a 2029 delivery, supporting projected adjusted EBITDA above $1 billion in…
S Monte Independent Investment Research Oct 6 1 click
Group 1 Automotive CEO Daryl Kenningham’s Toyota ties, capital-allocation decisions, compensation and stock sales face scrutiny after the…
S Cannibal Stocks Oct 6 3 clicks
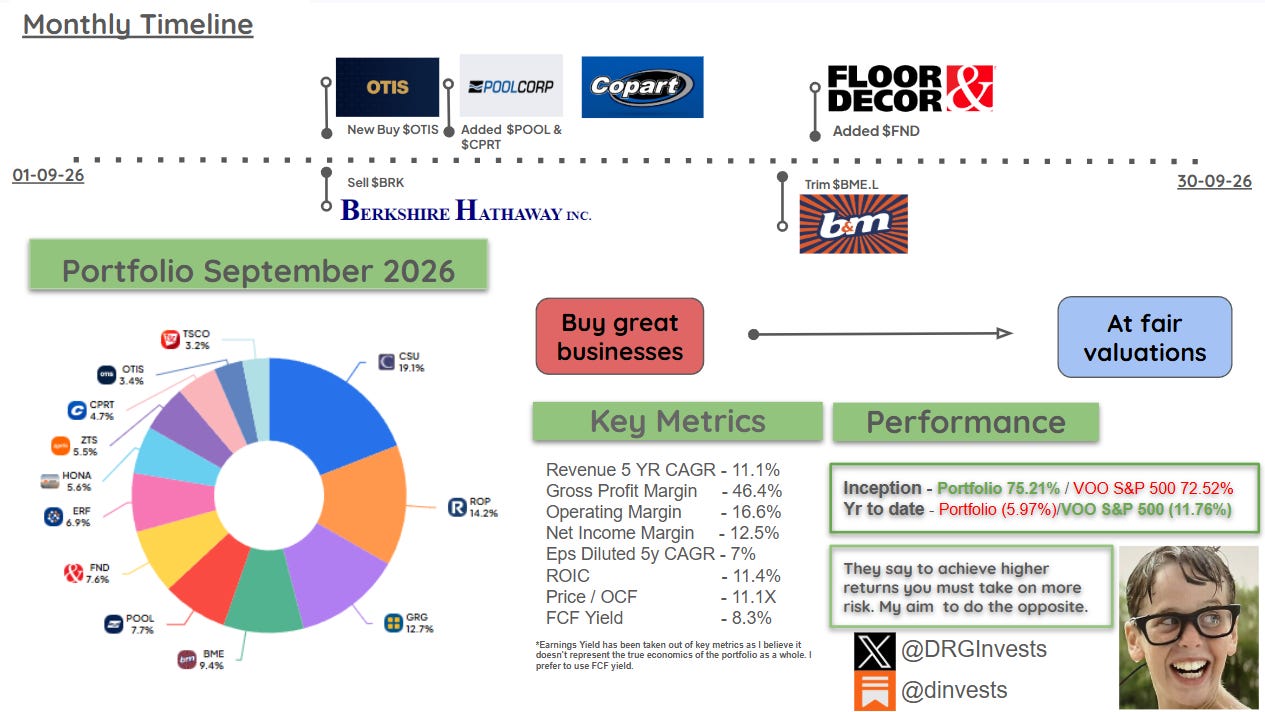
Portfolio added Otis Worldwide in the mid-$60s, increased Pool, Copart and Floor & Decor, and sold Berkshire Hathaway.
S D Invests Oct 5 1 click
POST · long Post Holdings remains a large position after the stock's recent decline.
BL Value Investors Club Jul 10
RLJ Lodging Trust trades below book value, with positive FY26 FFO guidance and property conversions offset by elevated leverage risk.
SA Albert Anthony Oct 6 2 clicks Brazilian fintechs NU, INTR and PICS stand to benefit from a Bolsonaro-led runoff surprise that lowers fiscal risk premiums, rates and the…
S Substack von Philipp Oct 5 3 clicks
Nyxoah's Genio implant could reach CCC patients after an FDA label expansion, targeting 30% of the obstructive sleep apnea device market by…
SA Stephen Tobin Oct 5 3 clicks OMSE 2026-10-05 Latticework’s briefing questions AI capex returns while featuring Close Brothers, Green Landscaping and OMS Energy Technologies.
S Latticework by MOI Global Oct 5 2 clicks
Group 1 paid $1 billion of goodwill for Hennessy’s 10 dealerships, a record $100 million per store, financed largely with $1.25 billion of…
S Cannibal Stocks Oct 4 4 clicks
Howard Hughes plans to raise nearly $4 billion by selling real estate assets and condos, accelerating Vantage’s insurance expansion while…
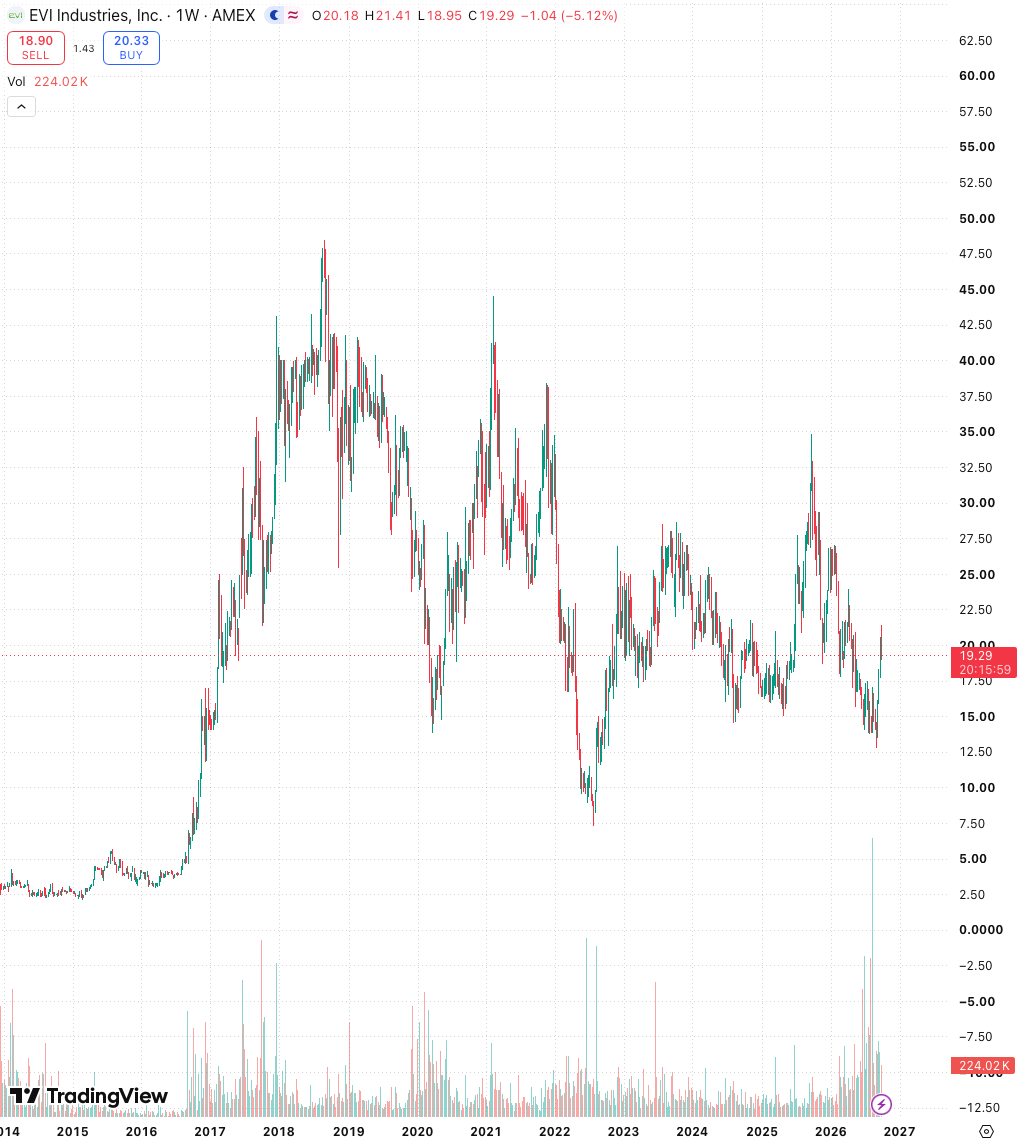
SA Gary Gambino Oct 3 3 clicks EVI Industries says its ERP and service-platform build is largely complete, testing whether 10.8% revenue growth can finally outpace…
S Kairos Research Oct 2 2 clicks
Lennar is selling homes to former spinoff Millrose, whose revenue largely comes from Lennar and whose largest voting shareholder is…
BL Hunterbrook Oct 2 2 clicks
Huckleberry.AI trades near $3.30 against $221 million of cash and $900 million-plus of NOLs after selling its operating business, creating…
S Hidden Rock Capital's Newsletter Oct 2 5 clicks