Selling Cenovus: Up 78% in 10 Months
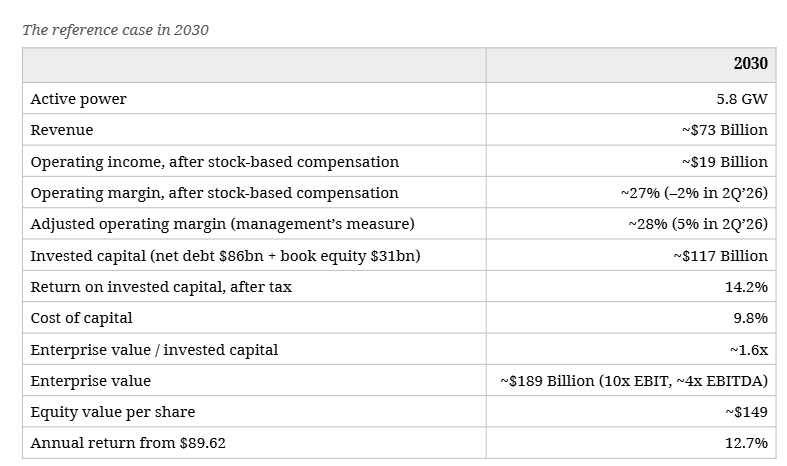
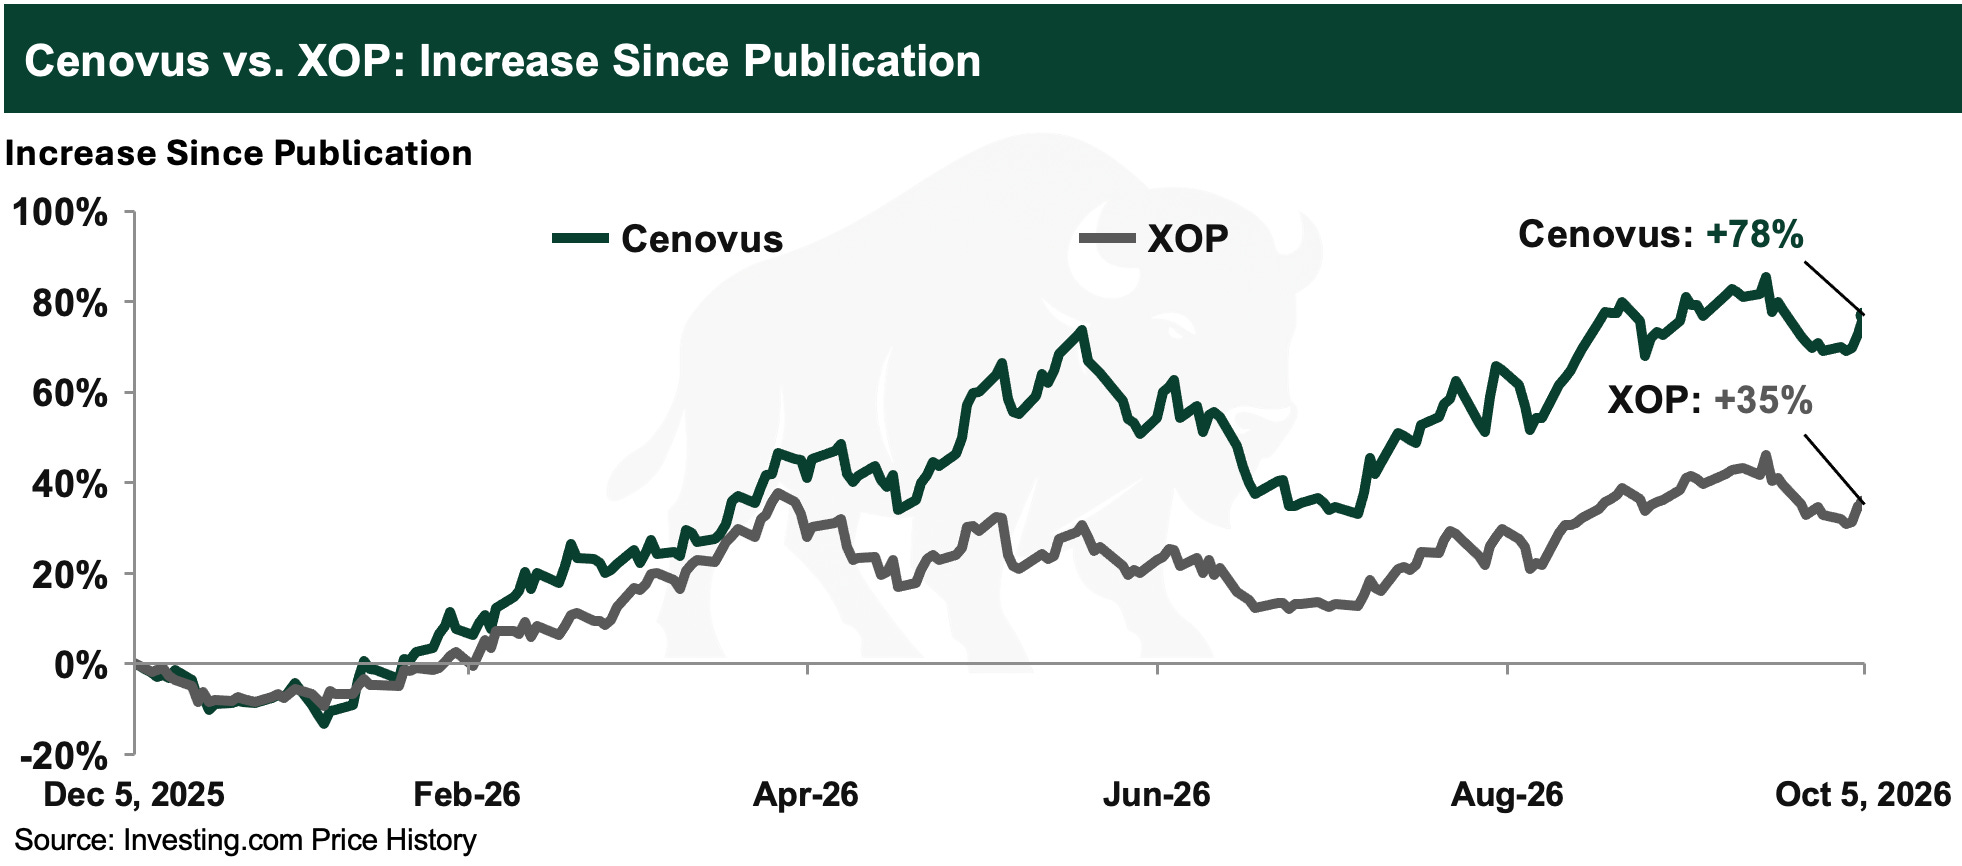
Cenovus Energy, up 78% in 10 months, is sold after agreeing to buy Athabasca Oil for $5.7 billion at a rich valuation.
Cenovus Energy, up 78% in 10 months, is sold after agreeing to buy Athabasca Oil for $5.7 billion at a rich valuation.
$MELI - Excellent Brazil outcome. Stock was at a technical bottom of its consolidation wedge. Business results will begin inflecting as the credit portfolio growth slows due to it’s now to size. Very bullish: Economic Backdrop, Business Results forward, and technicals
Seems like as good a week as any for $META to raise $50B or so in equity
@FedexSTi $NU back to the price it was three weeks ago.
@DavidWeinetayg @TidefallCapital Debt covenants matter. It won't however be the first or last company to buy itself back into ch11. I mean look at last quarter's buy backs in $FICO.
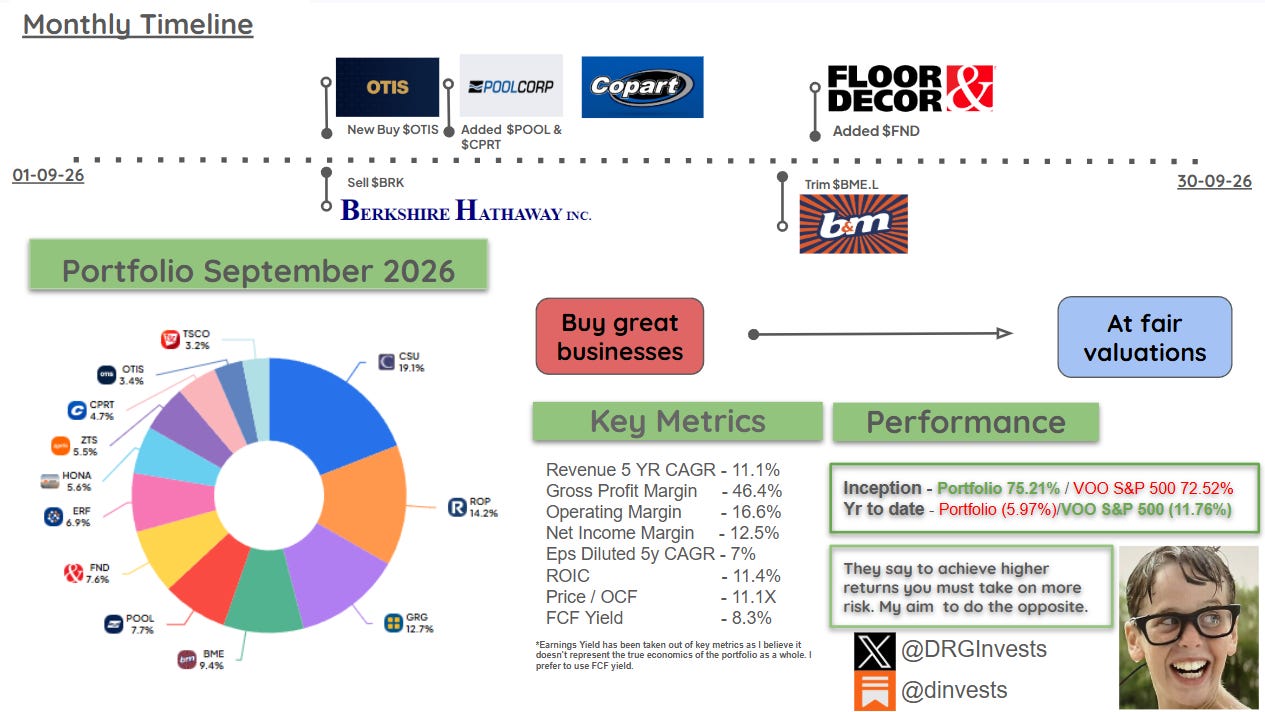
Portfolio added Otis Worldwide in the mid-$60s, increased Pool, Copart and Floor & Decor, and sold Berkshire Hathaway.
Ciena’s optical networking equipment sales to stronger telecom customers underpin a 2027 long thesis, unlike its 2000-era boom.
 Marc Gerstein 2 clicks
Brazilian fintechs NU, INTR and PICS stand to benefit from a Bolsonaro-led runoff surprise that lowers fiscal risk premiums, rates and the…
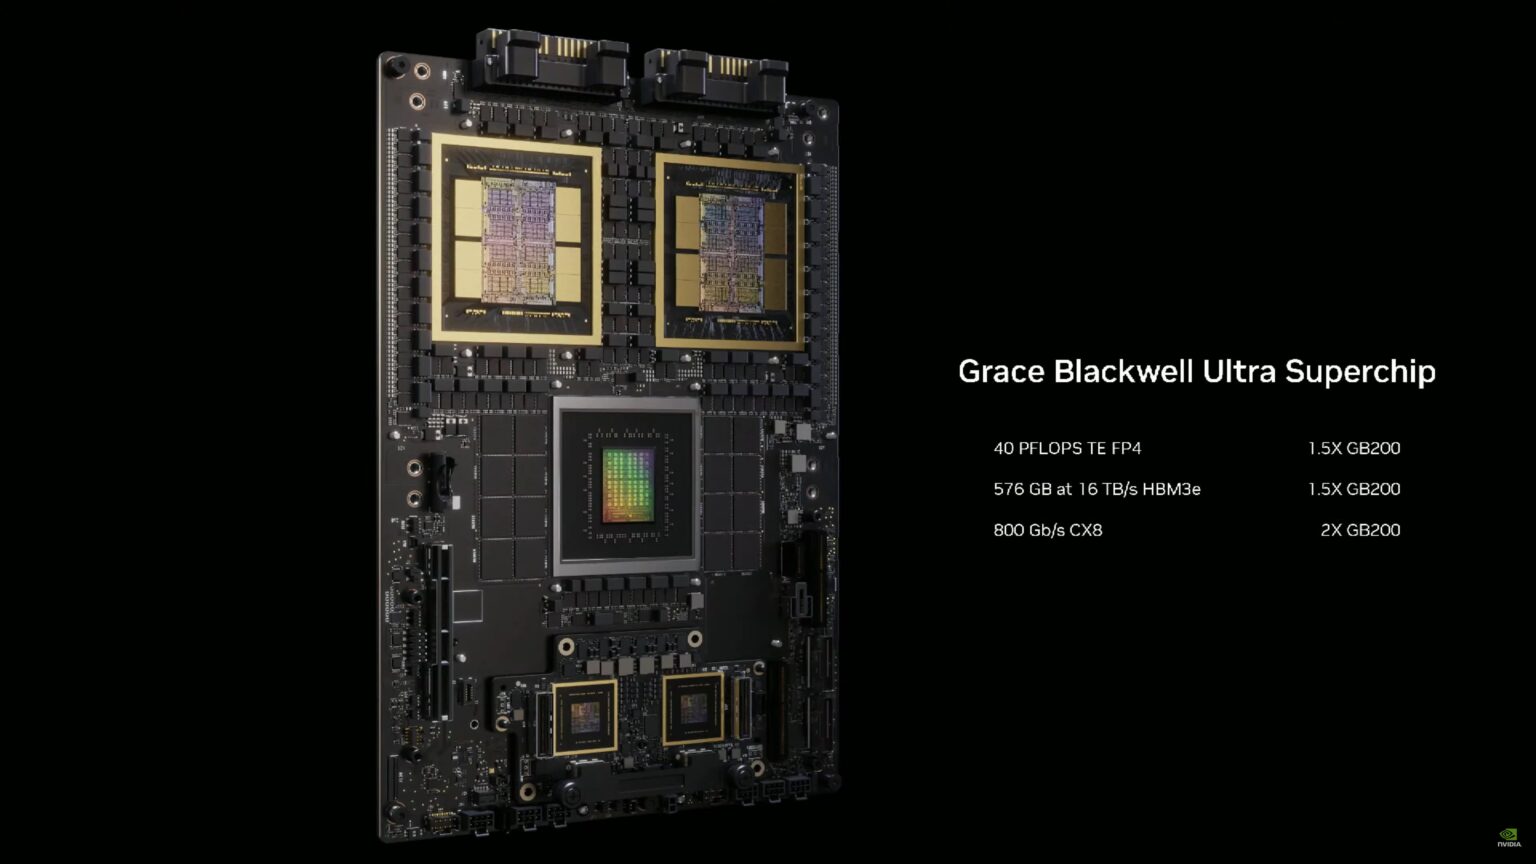
Nvidia’s Blackwell GPU rollout created an AI compute oversupply after customers preordered millions of chips amid expected shortages.
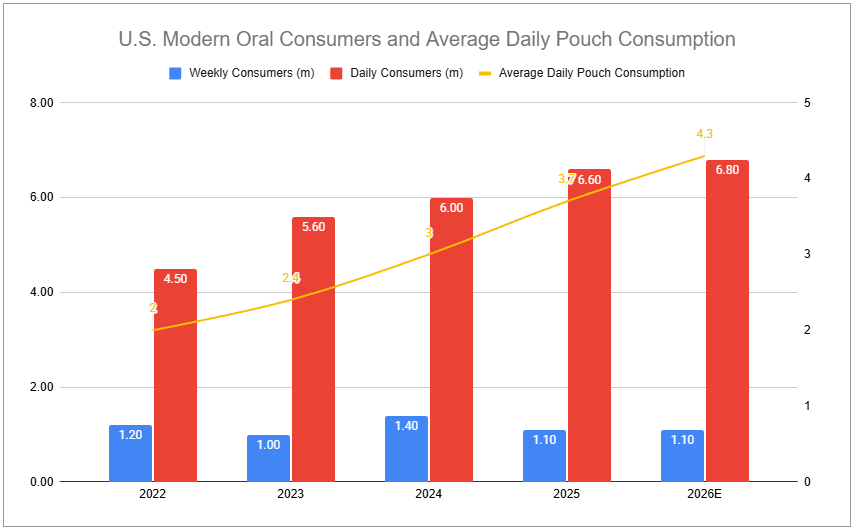
British American Tobacco’s U.S. reset revives combustibles and rebuilds its nicotine-pouch portfolio after legacy-brand writedowns and Velo…
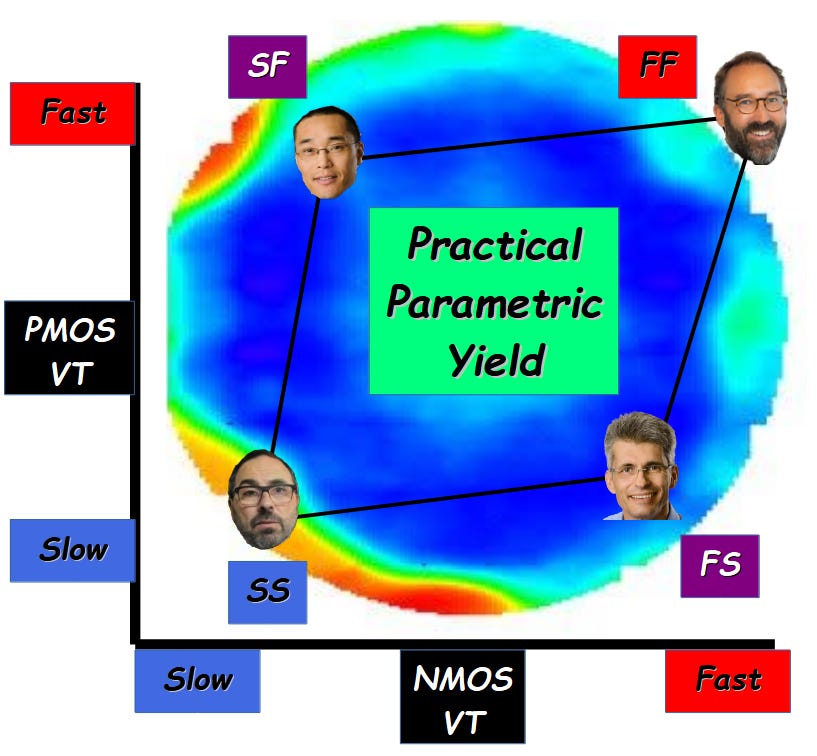
Cerebras’s WSE-3 faces parametric-yield constraints that could restrict supply, making power and clock-speed tradeoffs central to its next…
M&T Bank's 10.4% five-year revenue CAGR, improving net interest margin and commercial loan growth support its earnings resilience despite a…
 Albert Anthony 2 clicks
AI infrastructure’s $6.3 trillion financing gap is driving structured debt and asset-backed solutions, starting with Meta’s planned 5GW…
Walmart's FY28 consensus requires 15–18% operating-income growth above plan despite diesel costs, price investments and a non-recurring…
 Sameer Shahzad 2 clicks
Lennar is selling homes to former spinoff Millrose, whose revenue largely comes from Lennar and whose largest voting shareholder is…
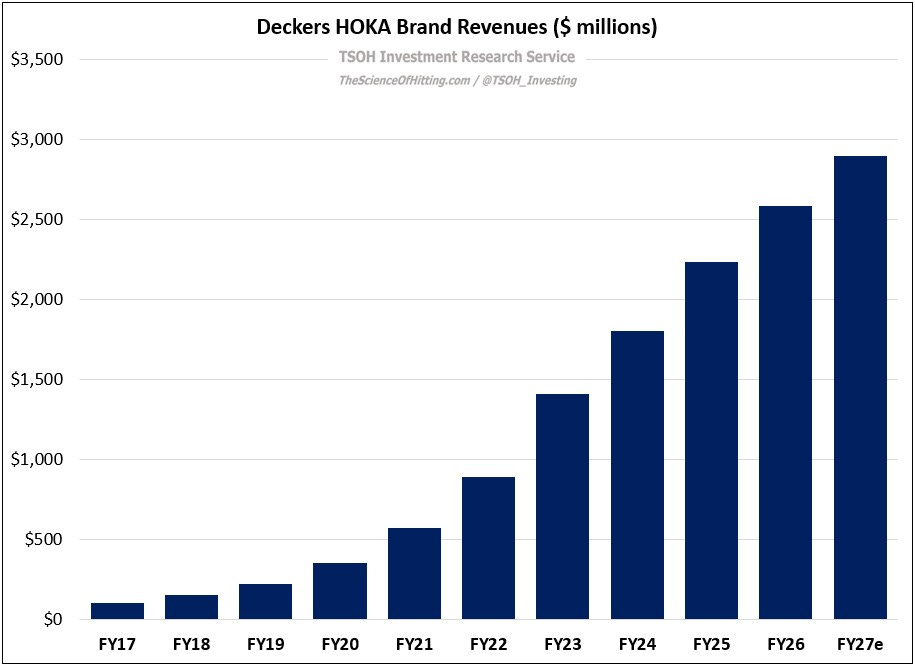
TSOH Weekly Roundup covers Meta’s AI agent ambitions, Netflix’s TV gaming strategy and Arc’teryx’s rise from $500 million to more than $2…
Nike targets EBIT margin recovery from 5.2% in FY2027 to 13% by FY2032 as revenue declines persist and wholesale, China and digital remain…
Cloudflare is building HTTP 402 payments for AI agents, using its web network to let publishers charge bots for content access.
Nike’s second Latticework program examines the company and the global athletic footwear and apparel industry for professional investors.
Nike grew from a $1,000 shoe-distribution venture in 1964 into the largest sports brand, using athlete endorsements, product innovation and…
ServiceNow expects AI annual contract value to reach $1.5 billion by year-end, with assist-pack consumption pricing supporting growth…
 Jetstream Research 1 click
Rocket Lab reported Q2 revenue up 62% to $234.1 million and backlog up 137% to $2.36 billion, while operating losses and cash burn…
American Healthcare REIT’s senior-housing and outpatient portfolio is driving FFO growth and dividend safety, while a rich valuation limits…
Albert Anthony 1 click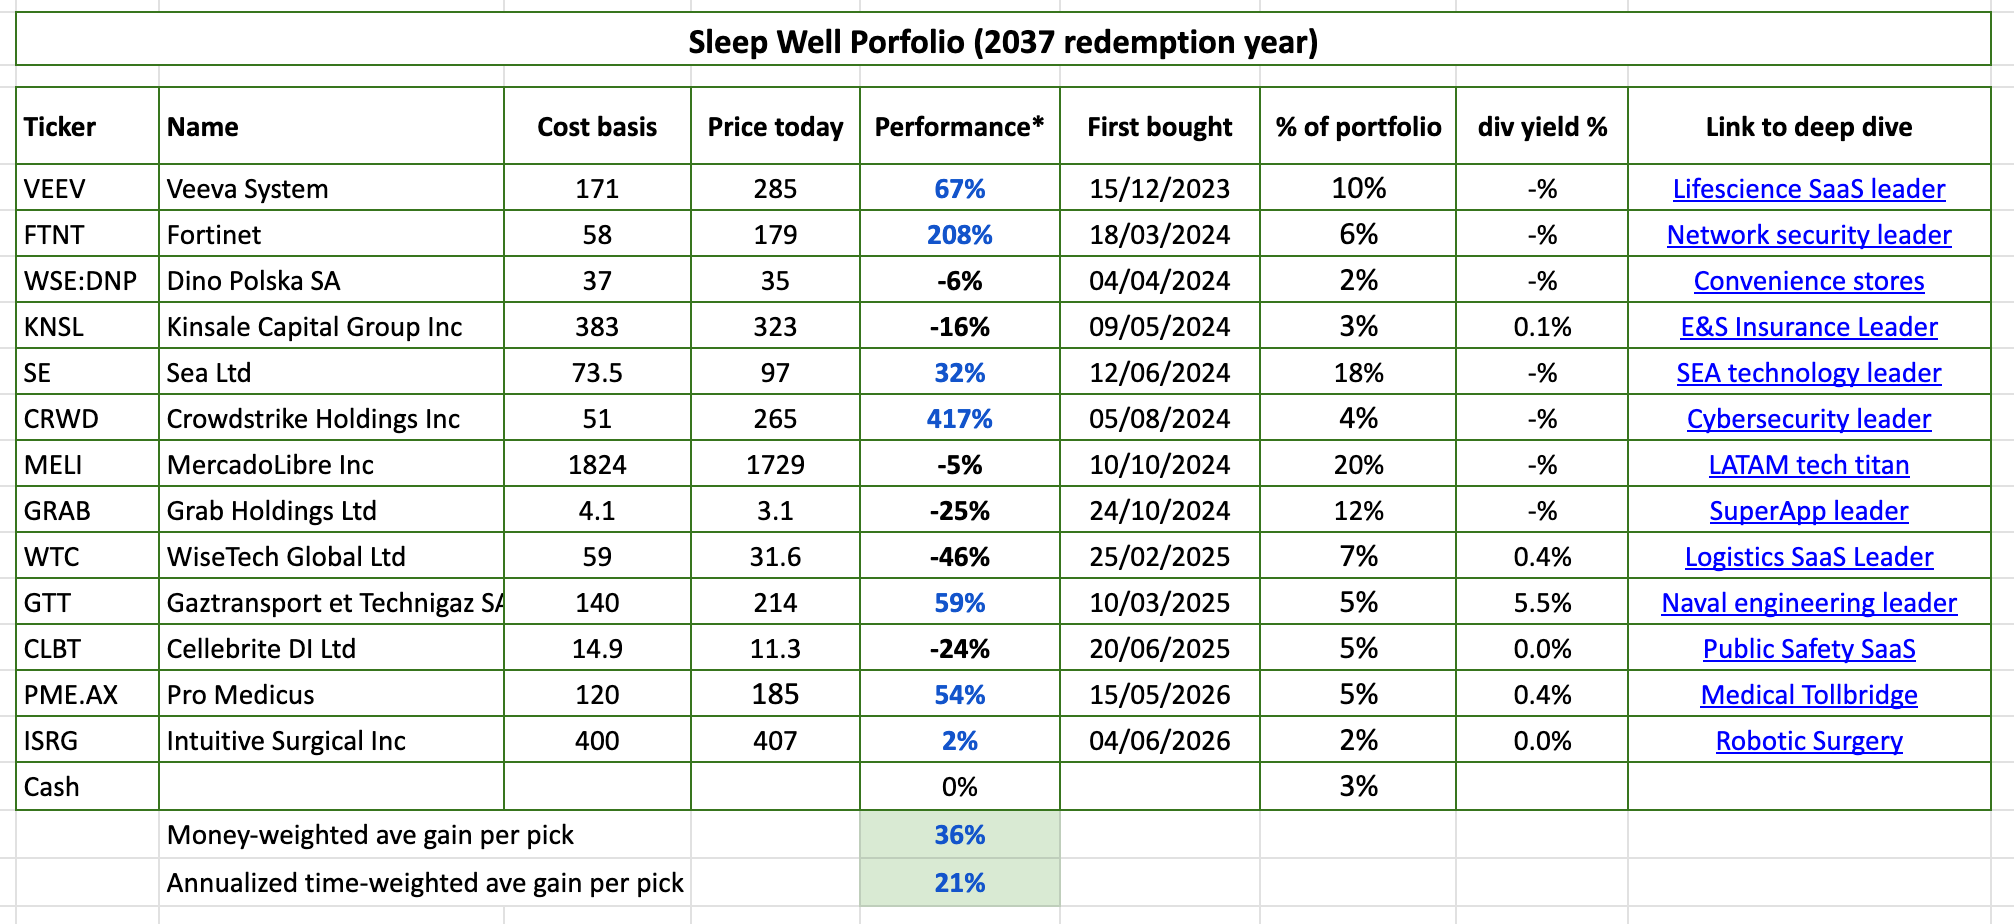
CrowdStrike faces a trim at a $270 billion valuation and 140x free cash flow, despite AI-driven cybersecurity demand and a $20 billion ARR…
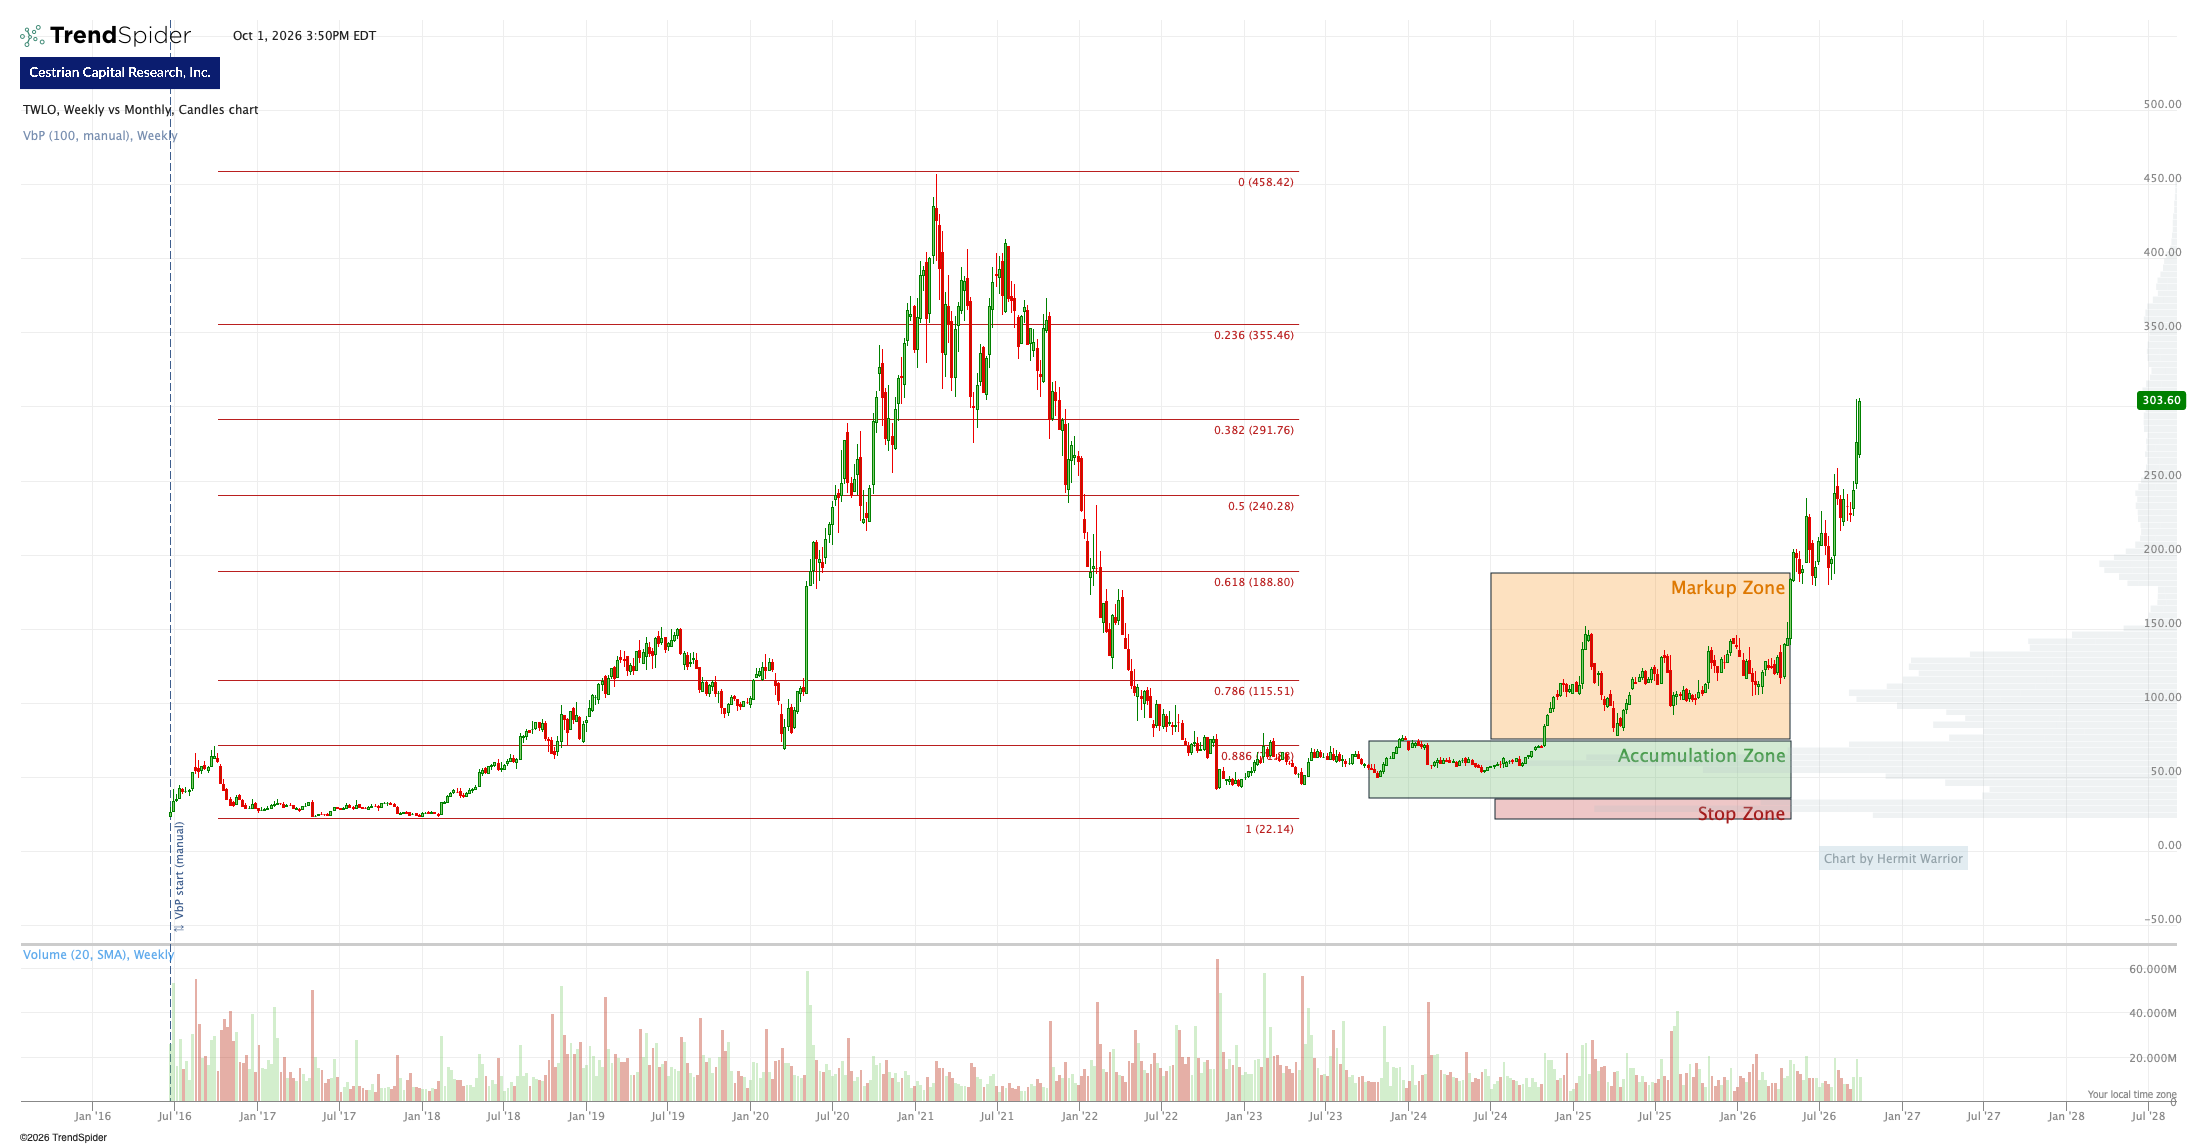
Twilio posted Q2 revenue of $1.50 billion, up 22%, and guided 16% Q3 growth; the note rates TWLO Hold at $305, with a $260 risk line.
Every publication on this site, hand-picked.
Albert Anthony Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.