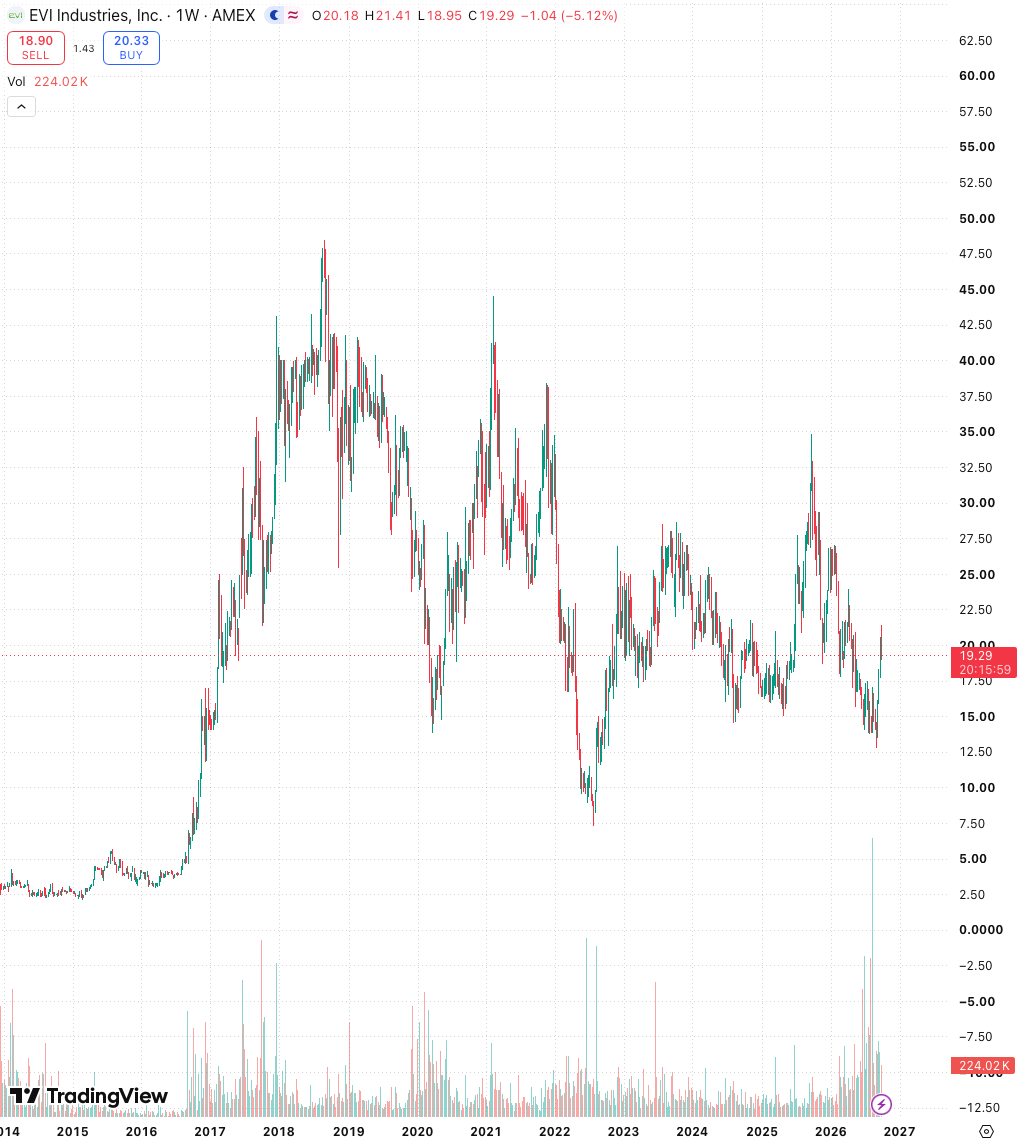
EVI Industries. Margin inflection or fake out?
EVI Industries says its ERP and service-platform build is largely complete, testing whether 10.8% revenue growth can finally outpace operating costs and lift margins.
EVI Industries says its ERP and service-platform build is largely complete, testing whether 10.8% revenue growth can finally outpace operating costs and lift margins.
GoPro $GPRO - A failed YouTuber pump, crushed by M&A https://t.co/gpscNAV2rQ https://t.co/H54oIAbZeZ
@grok who had a better earnings report this quarter, $fcel or $sive ? https://t.co/yQYserPn4b
FNBO to Acquire InBank, $INBC Expand Colorado Market - https://t.co/UyOn1G6w5F
$DRVN.. The Company is likely trading at 6x EBIT(DA) and ~14 pct FCF yield and ~20 pct on maintenance in 2027. 8 mm shares are short and the de facto float is 32 mm (backing out large long term owners).. Can basically buyback the entire float with one year of FCF. Not $VVV
I think my $ORR position is too large because I made the same mistake I see a lot of investors on here make. I didn't have enough good ideas, so I bet too big on my best idea.
Yes, those two. They are willing to sell the entire company, but the value of those two plants, specifically, are now much higher. I expect significant consolidation within the industry and that everyone is just waiting to see what happens with not only E15 in California, but year-round nationwide. If the Senate passes something in September/October then the odds that both $ALTO and $GPRE get sold skyrocket.
Nike targets EBIT margin recovery from 5.2% in FY2027 to 13% by FY2032 as revenue declines persist and wholesale, China and digital remain…
Nike’s second Latticework program examines the company and the global athletic footwear and apparel industry for professional investors.
Nike grew from a $1,000 shoe-distribution venture in 1964 into the largest sports brand, using athlete endorsements, product innovation and…
Boeing won the $20 billion Navy F/A-XX contract after securing the Air Force F-47, concentrating U.S.
 Dhierin Bechai 1 click
Rocket Lab reported Q2 revenue up 62% to $234.1 million and backlog up 137% to $2.36 billion, while operating losses and cash burn…
AAR’s $1.8 billion acquisition of a 65% stake in MRO Holdings adds widebody aircraft maintenance and targets a 19% to 20% EBITDA margin by…
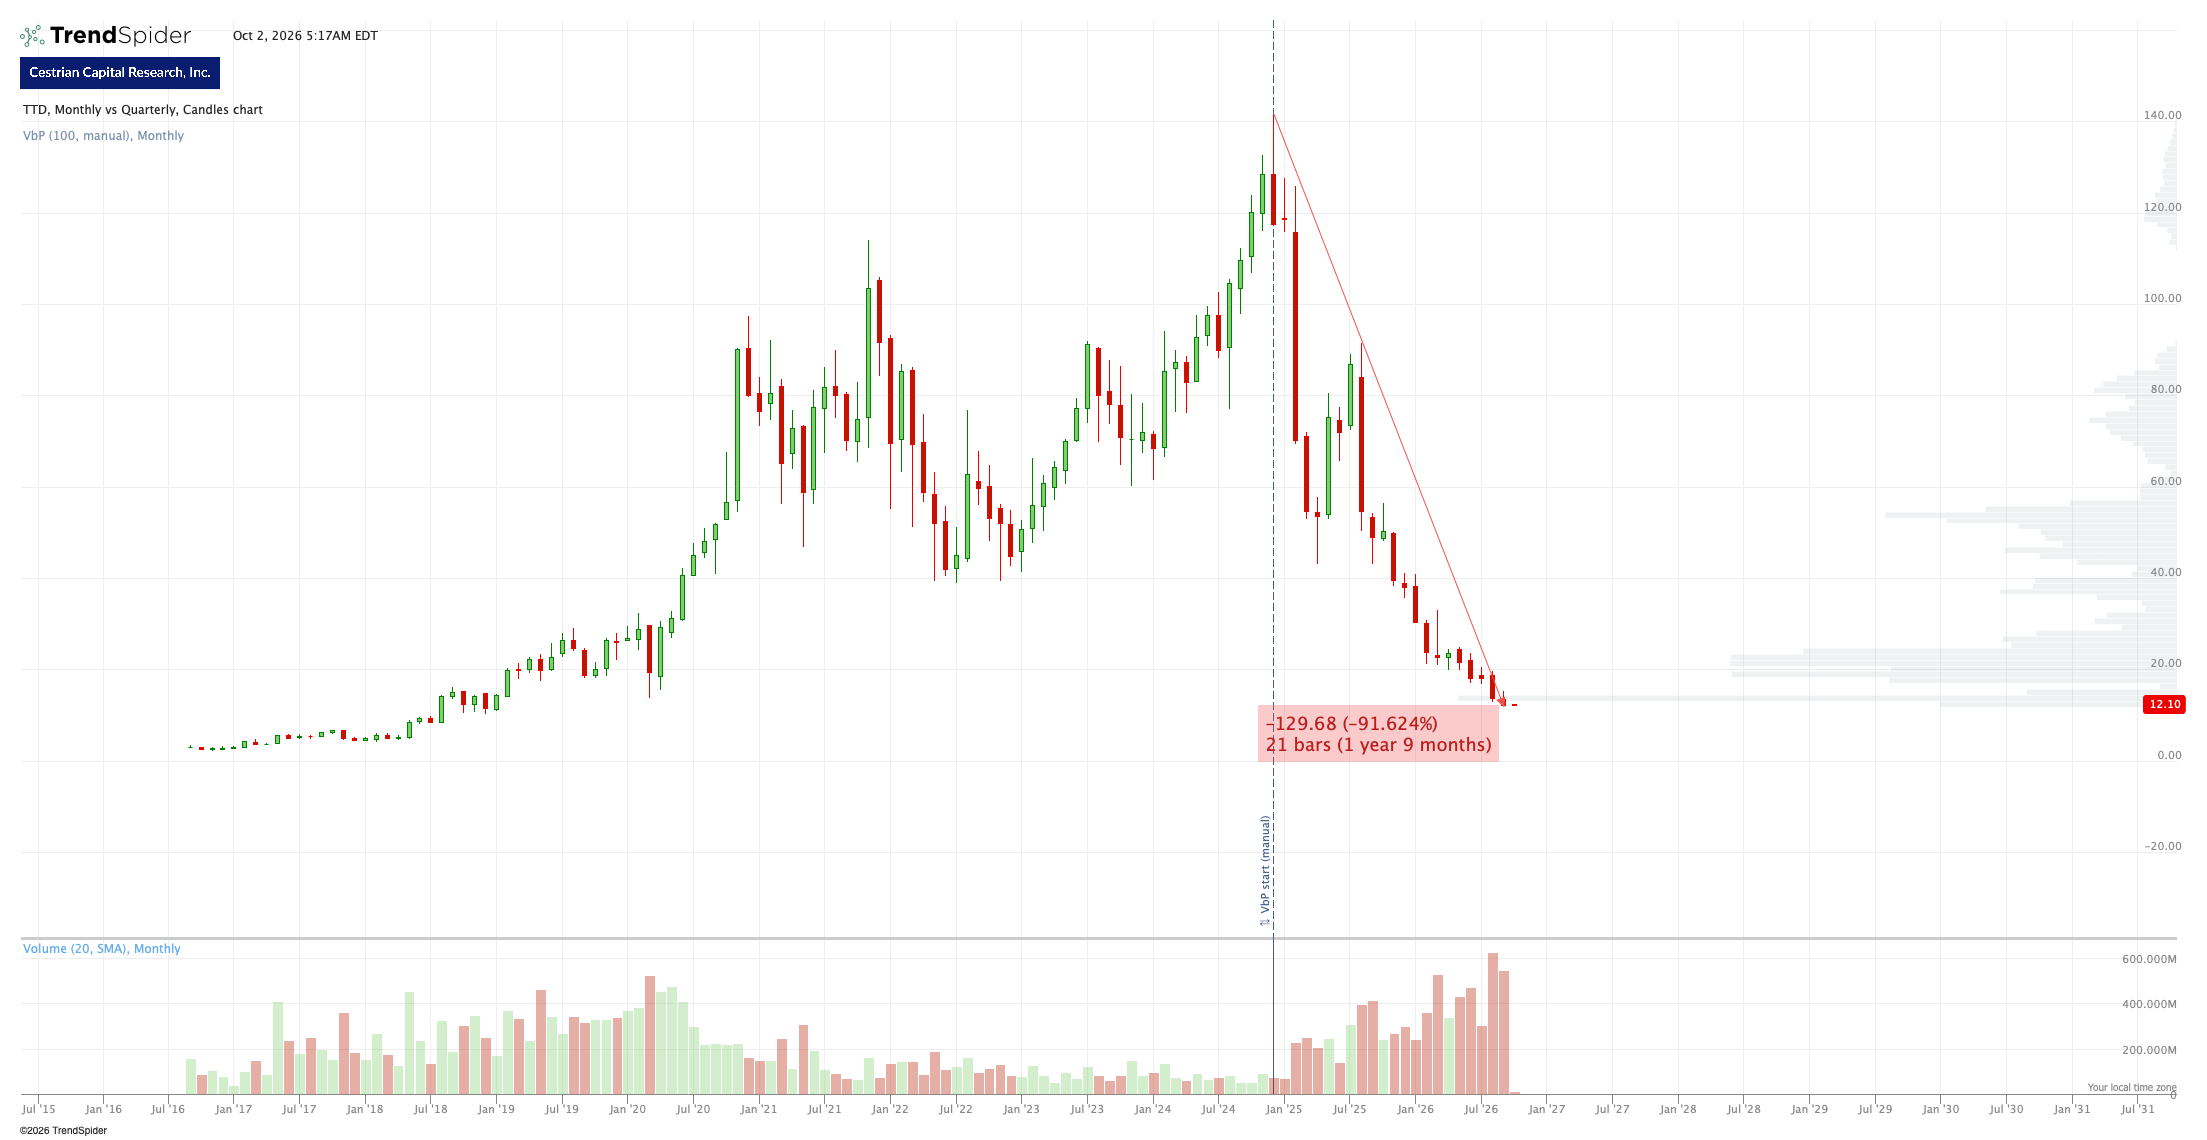
The Trade Desk's Q2 revenue grew 3% to $715 million as Q3 guidance called for a year-over-year decline; TTD has fallen over 90% from its…
Belden targets net leverage of 2.9x by 2027 from 3.9x, using RUCKUS's 65%+ gross margins and free cash flow to reduce debt.
 Lee Bailey 1 click

Turning Point Brands' FRE and Alp nicotine pouches aim to become a third C-store brand behind ZYN and Velo as PMTA rules limit new entrants.
Mattel rose 19% on takeover speculation, but a potential $20-per-share bid, margin pressure and CEO transition leave its standalone…
 Seeking Profits 1 click
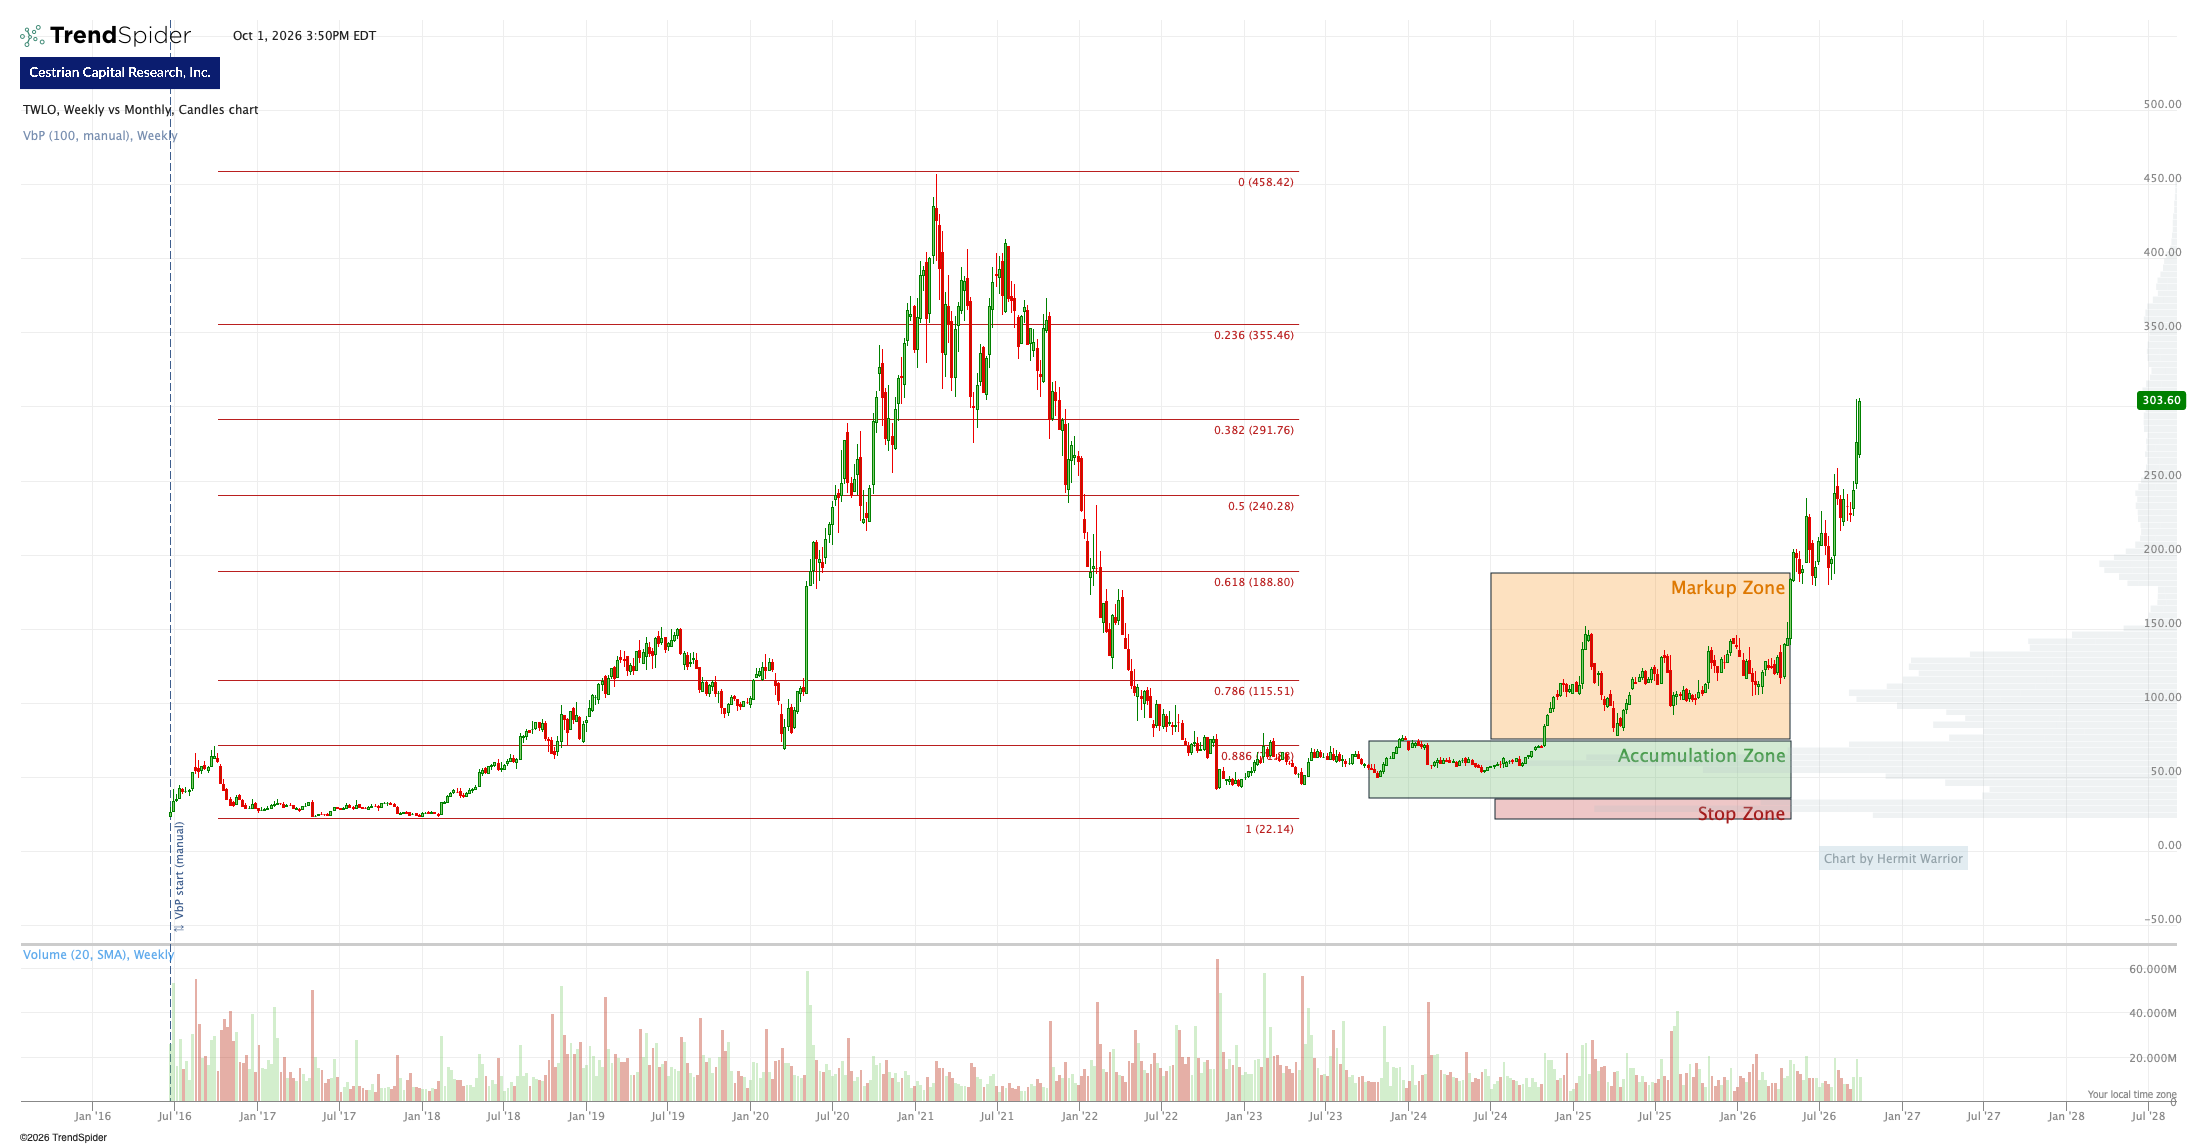
Twilio posted Q2 revenue of $1.50 billion, up 22%, and guided 16% Q3 growth; the note rates TWLO Hold at $305, with a $260 risk line.
Constellium’s widening feedstock-to-end-price spread supports 2026 EBITDA guidance of $980M-$1.02B and free cash flow above $300M.
 Andres Veurink 1 click
Muse could sidestep ads by becoming a neutral commerce agent, while DoorDash and Airbnb build proprietary agents that steer users toward…
Chipotle's Q2 revenue rose 9.3% as traffic and market share grew; the case rests on pricing catching inflation to restore margins.
 The Alpha Analyst 1 click
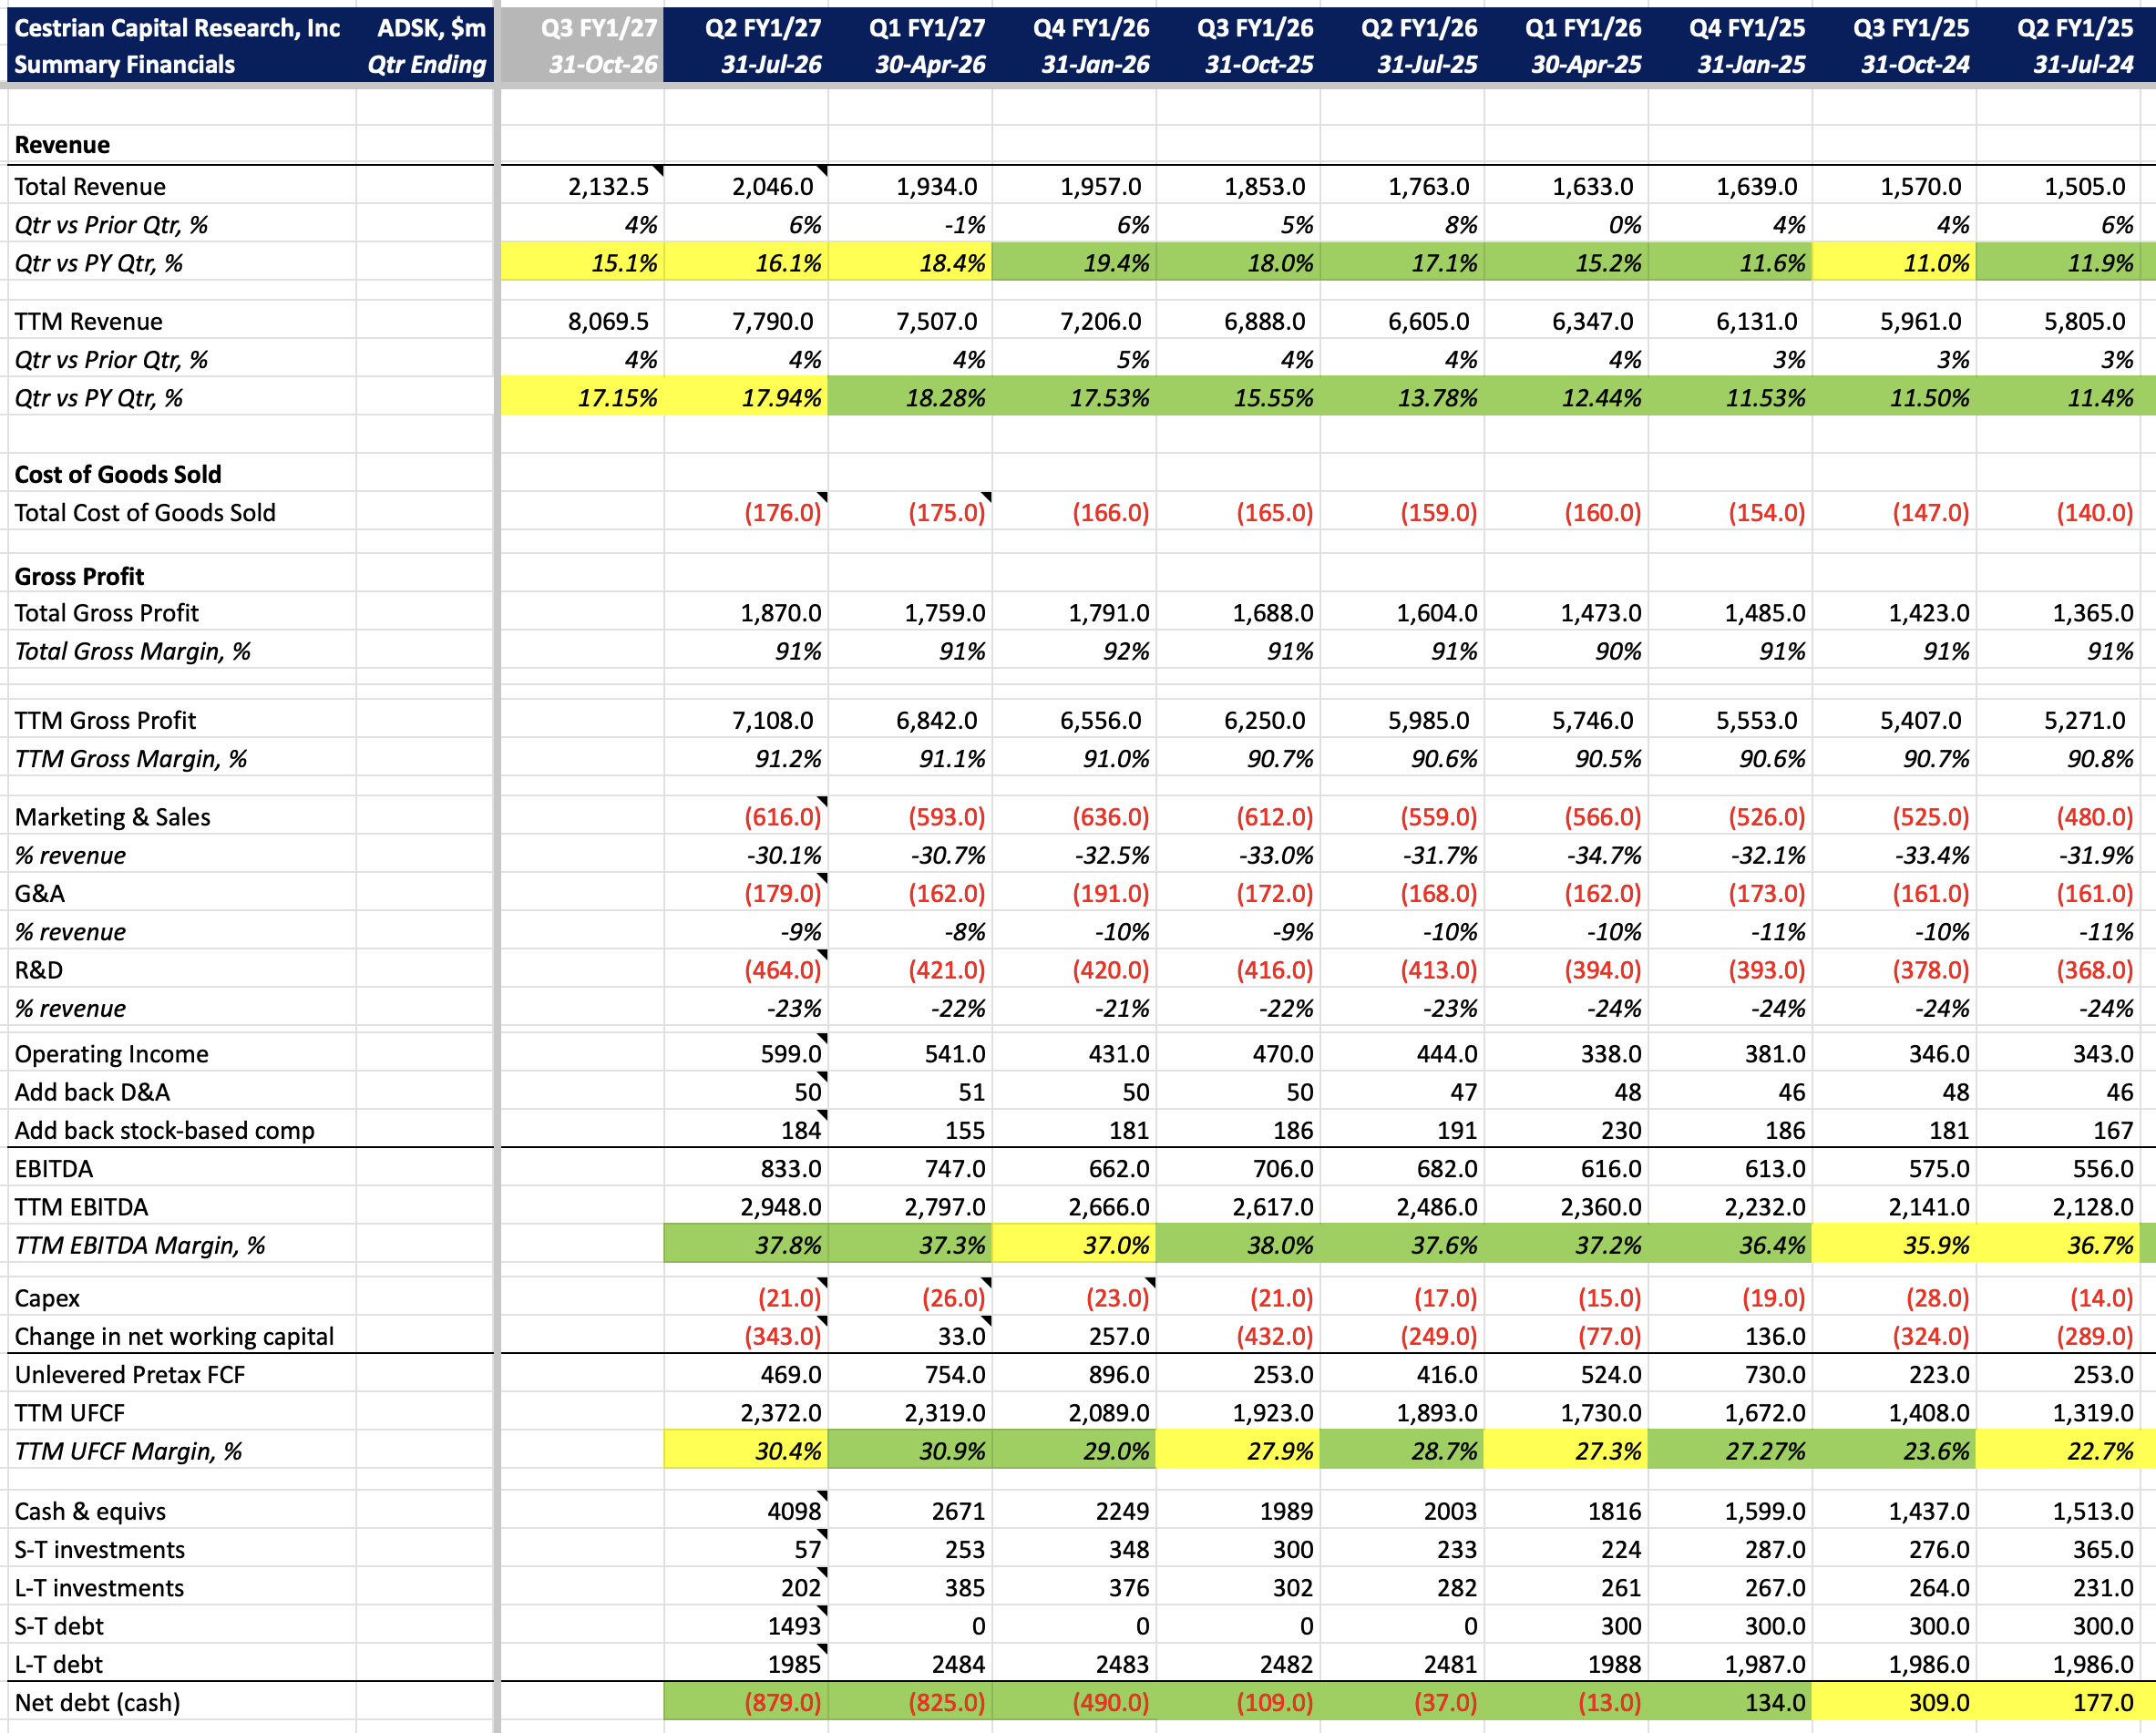
Autodesk reported Q2 revenue growth of 16% to $2.05 billion, while RPO growth slowed to 2%; FY2027 guidance calls for $8.30 billion to…
Ethos Technologies ($LIFE) sells AI-driven life insurance while relying heavily on multilevel marketing agencies using aggressive cold…
Karman Holdings reported 58% Q2 revenue growth, $1.3 billion backlog and margin expansion while replacing leadership and remediating…
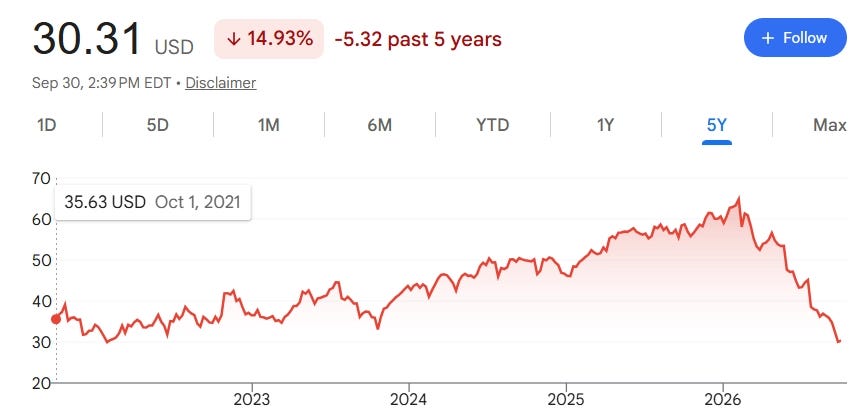
Rollins’ shares have fallen more than 50% from their peak, resetting valuation as route density, reliable service and pricing support…
Pearson, CarMax, Talen Energy, KBR and Apollo Commercial Real Estate lead a 33-company survey of activist campaigns, buybacks, M&A and…
HubSpot trades at 18.4x forward earnings and 3x sales after the SaaS selloff; a DCF using 22% FCF growth values shares at $302.66.
 Bishop Research and Analytics 5 clicks
Every publication on this site, hand-picked.
 Albert Anthony Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.