Twilio (NYSE: TWLO) Stock Rating: Hold After Q2 FY12/26 Earnings - Distribute Below $260
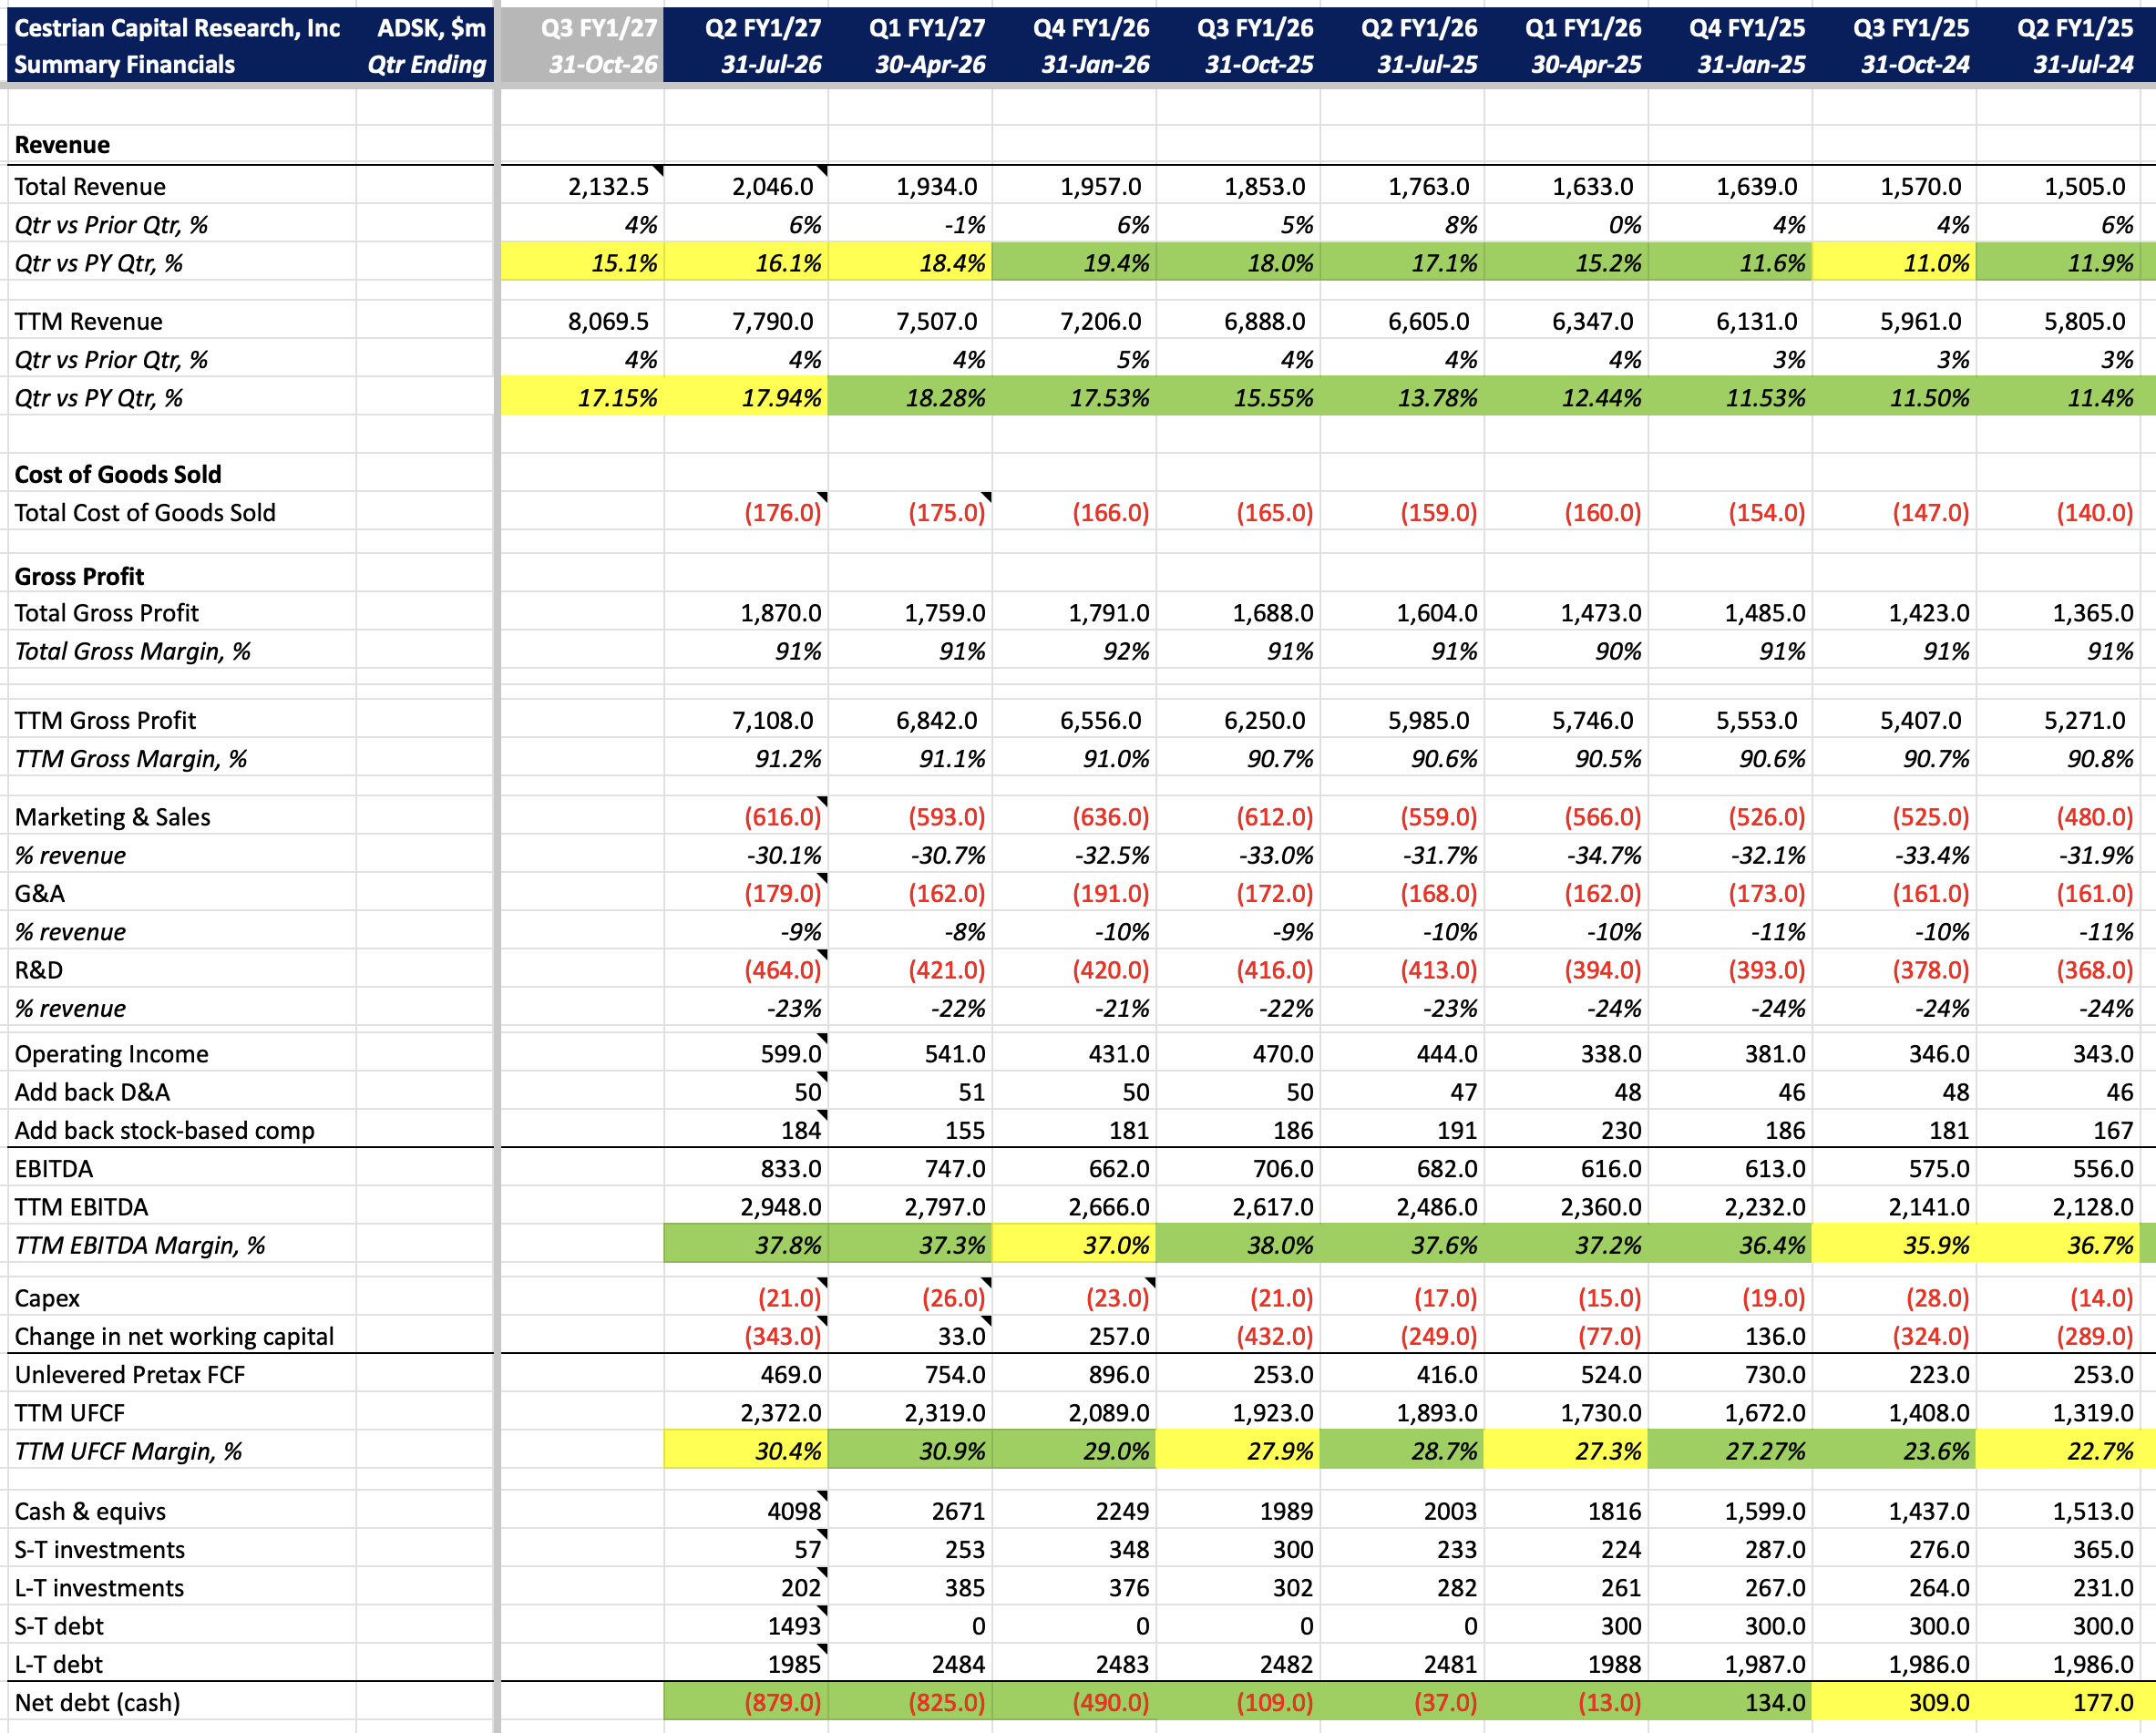
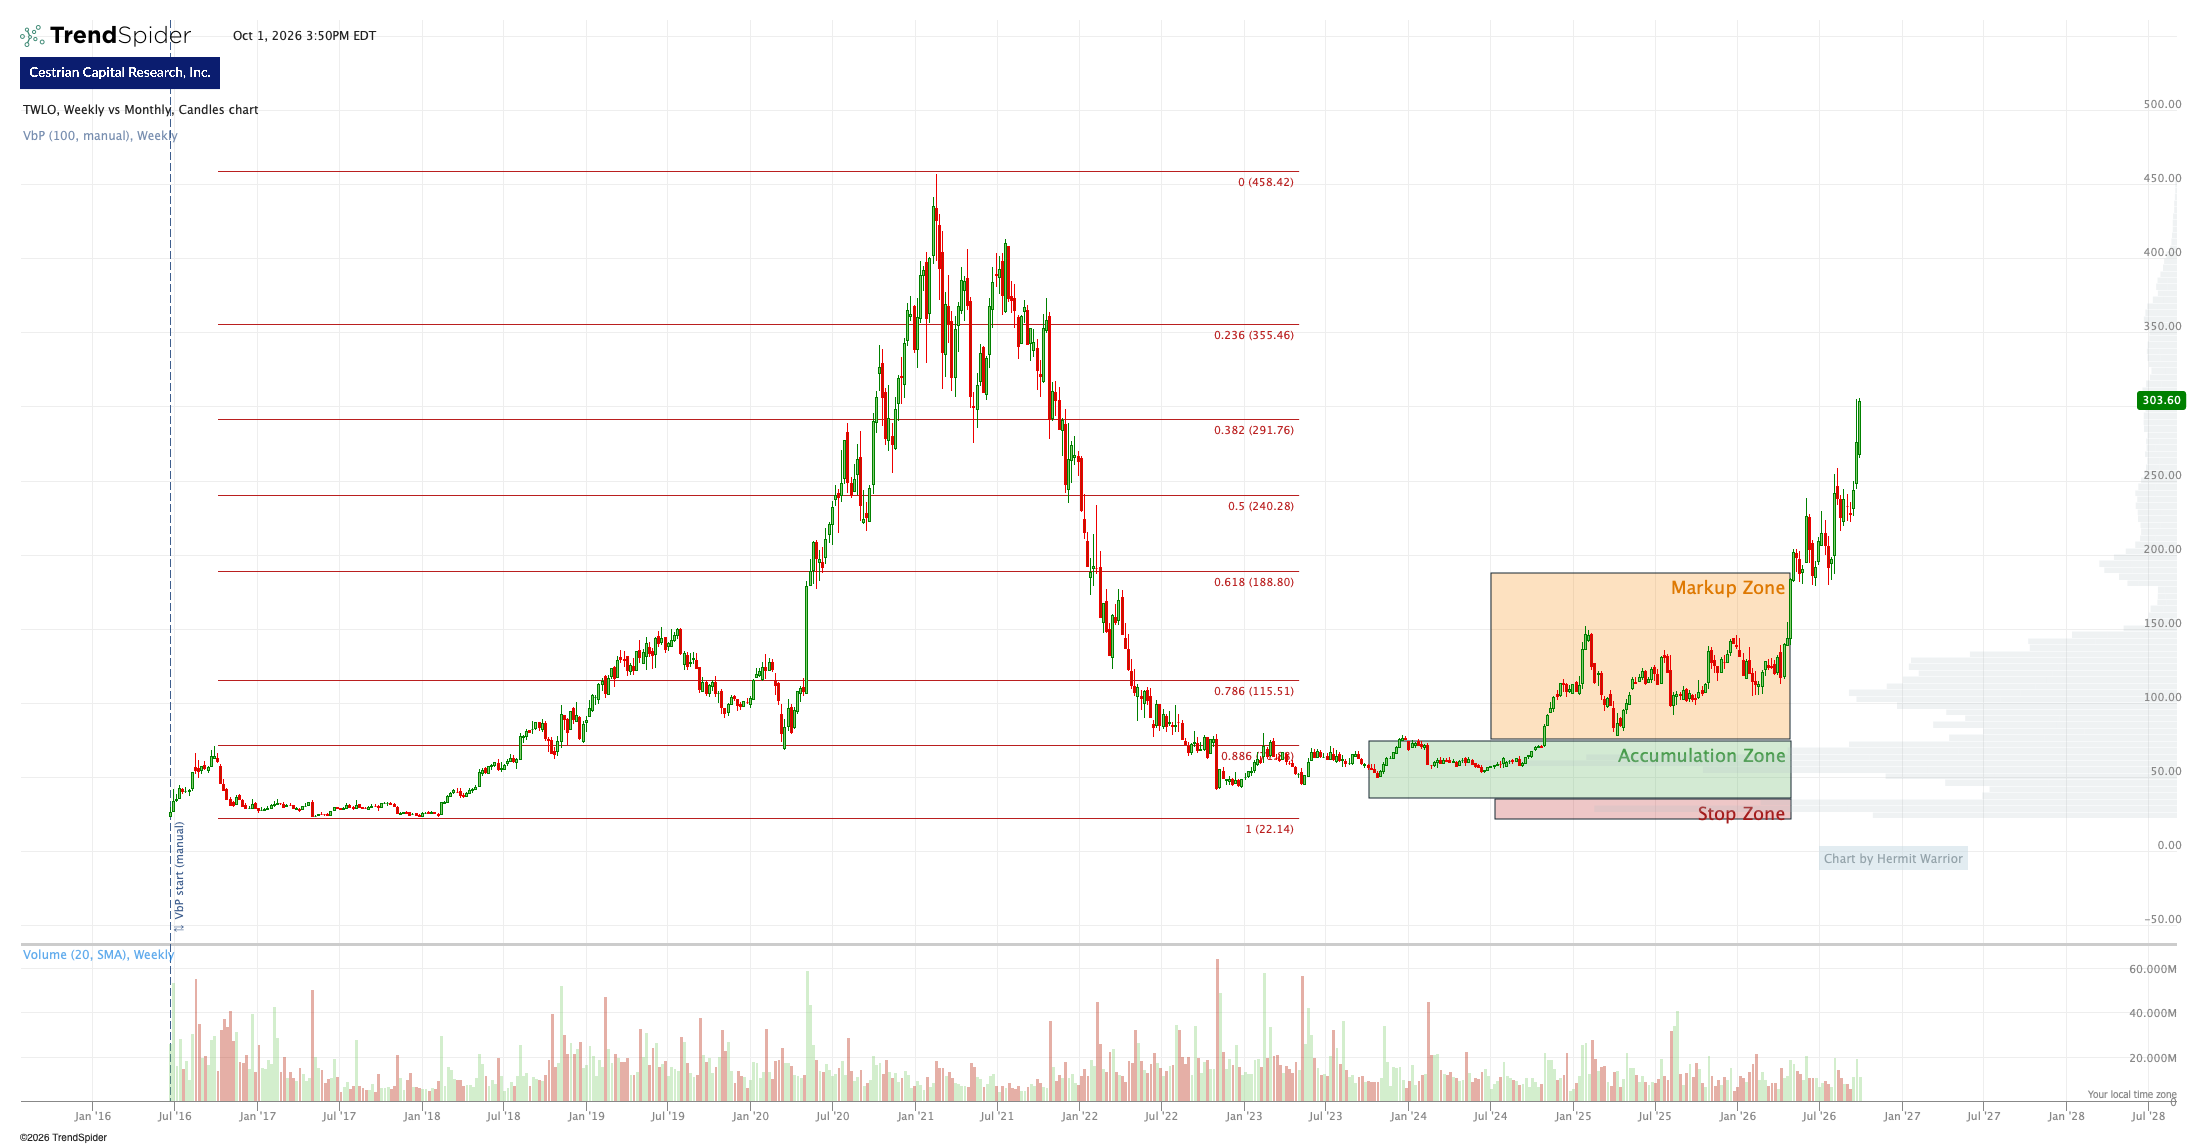
Twilio posted Q2 revenue of $1.50 billion, up 22%, and guided 16% Q3 growth; the note rates TWLO Hold at $305, with a $260 risk line.
Twilio posted Q2 revenue of $1.50 billion, up 22%, and guided 16% Q3 growth; the note rates TWLO Hold at $305, with a $260 risk line.
$FTDR Vol declining (existing home sales=driver). Pricing lagging inflation, massively over-earning. Problematic given 25% churn w aggressive new entrants. Dubious company overall. Investor day yesterday was comical, compared themselves to $NFLX. Earnings misses coming.
$AVO $CVGW 1) Retailers $CMG, etc sourcing elsewhere given MX tariff risk. 2) Avocado price spike during last year’s peak harvest season enabled distributors to realize outsized margins. 1-time benefit has reversed, significant earnings misses ahead for these commodity businesses
$NX Outlandishly guiding to flat 2025 sales, customers and channel -DD. Commodity window and door components facing pricing pressure from larger customers ($JELD, $OC). Now levered 4x, trading at a premium to higher value-add building products peers. Guide cut inevitable.
$J Beat earnings yesterday. Holding back detailed guidance for Investor Day (2/18)—likely raise ’25 #s, 4-year financial targets w significant upside on margins ($ACM and other peers +15% EBITDA margins). Record backlog and multi-year growth runway.
The industrial logic for the $UNF and $CTAS merger captured in one picture. Both have been going to the Chipotle (or same strip center) near our office in Houston on the same days at the same time (the store was closed at the time this pic was taken). https://t.co/zxTIFVgn1s
$NX Rapidly declining levered (4x) commodity biz. Q1’25 guide -12% sales, mgmt hoping for 2H’25 recovery. End-mkts deteriorating ($OC -20% Q4 guide, $JELD), customer losses, internal controls issues, integrating a large acq, 0 prior M&A experience. +30x P/E on best case 2025 #s
@StockJabber Thank you. As a read on $PLUS Q3 is tracking in October, $CSCO just reported -23% sales in networking (products account for ~50% of $PLUS revenue) for the Oct quarter-end. Further confirmation that PLUS Q3 is going to be ugly and no turnaround in sight.
$PLUS Accelerating, sales -14% y/y in Q2, noted Q3 not improving yet implied FY guide is for flat sales (downward revisions to come). Margins benefitted from 1-time financing segment gain-on-sale. Still trading at a premium to higher quality industry leader CDW, makes zero sense.
YieldMax HOOD Option Income Strategy ETF pays high weekly income from Robinhood volatility, but return-of-capital distributions and a 0.99%…
 Ivan Gaddari 1 click
Ethos Technologies ($LIFE) sells AI-driven life insurance while relying heavily on multilevel marketing agencies using aggressive cold…
Karman Holdings reported 58% Q2 revenue growth, $1.3 billion backlog and margin expansion while replacing leadership and remediating…
Innodata's 45% pullback resets its valuation after two quarters of 50% revenue growth, though two customers still supply 71% of revenue and…
 Kurt Christensen 2 clicks
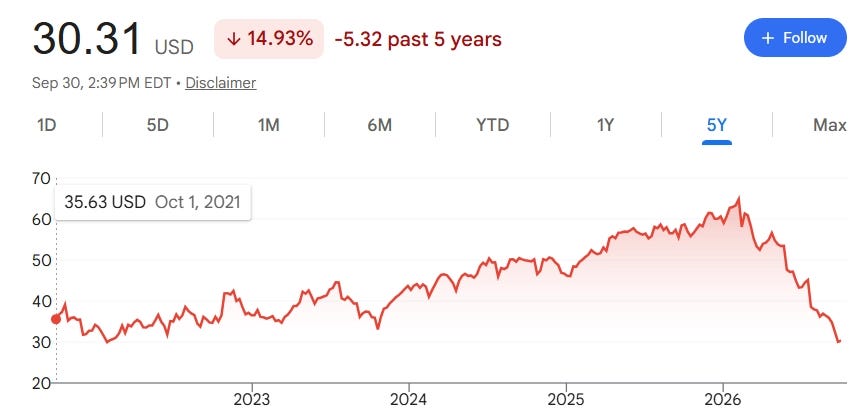
Rollins’ shares have fallen more than 50% from their peak, resetting valuation as route density, reliable service and pricing support…
Pearson, CarMax, Talen Energy, KBR and Apollo Commercial Real Estate lead a 33-company survey of activist campaigns, buybacks, M&A and…
Group 1’s 19% ownership cap, tied to automaker franchise agreements, frames Conifer’s 1.9 million-share stake and potential buyback-driven…
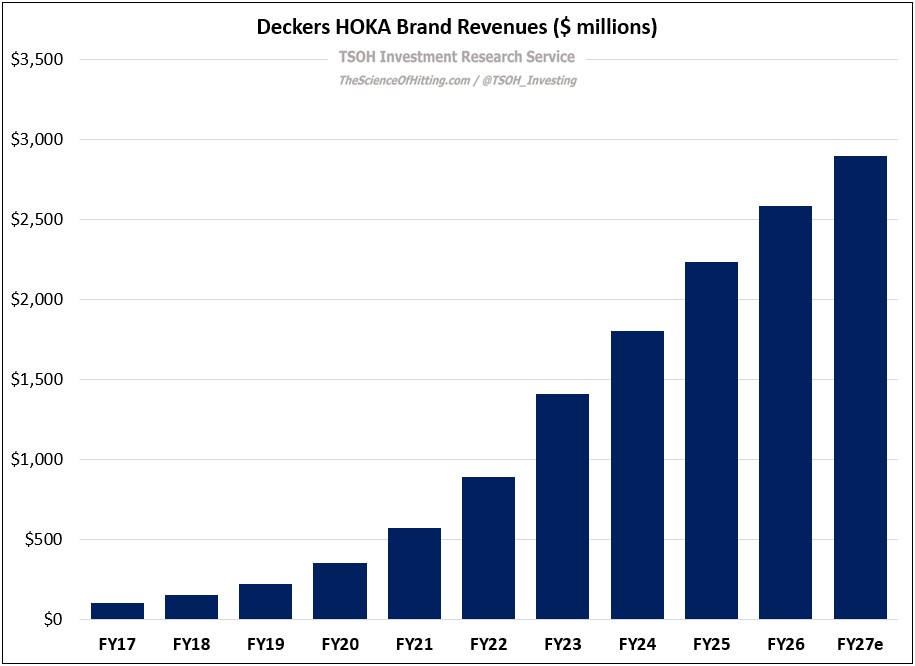
Deckers built HOKA into a brand nearing UGG’s scale, with HOKA revenue up about fivefold since FY21.
Irrational Analysis reports 51.55% outperformance versus a semiconductor ETF, adding Credo for SerDes and QMCO for AI-driven tape storage…
Occidental Petroleum could benefit as declining shale inventories and high rates curb industry capex, tightening oil supply against demand…
 Gen Z Investor 1 click
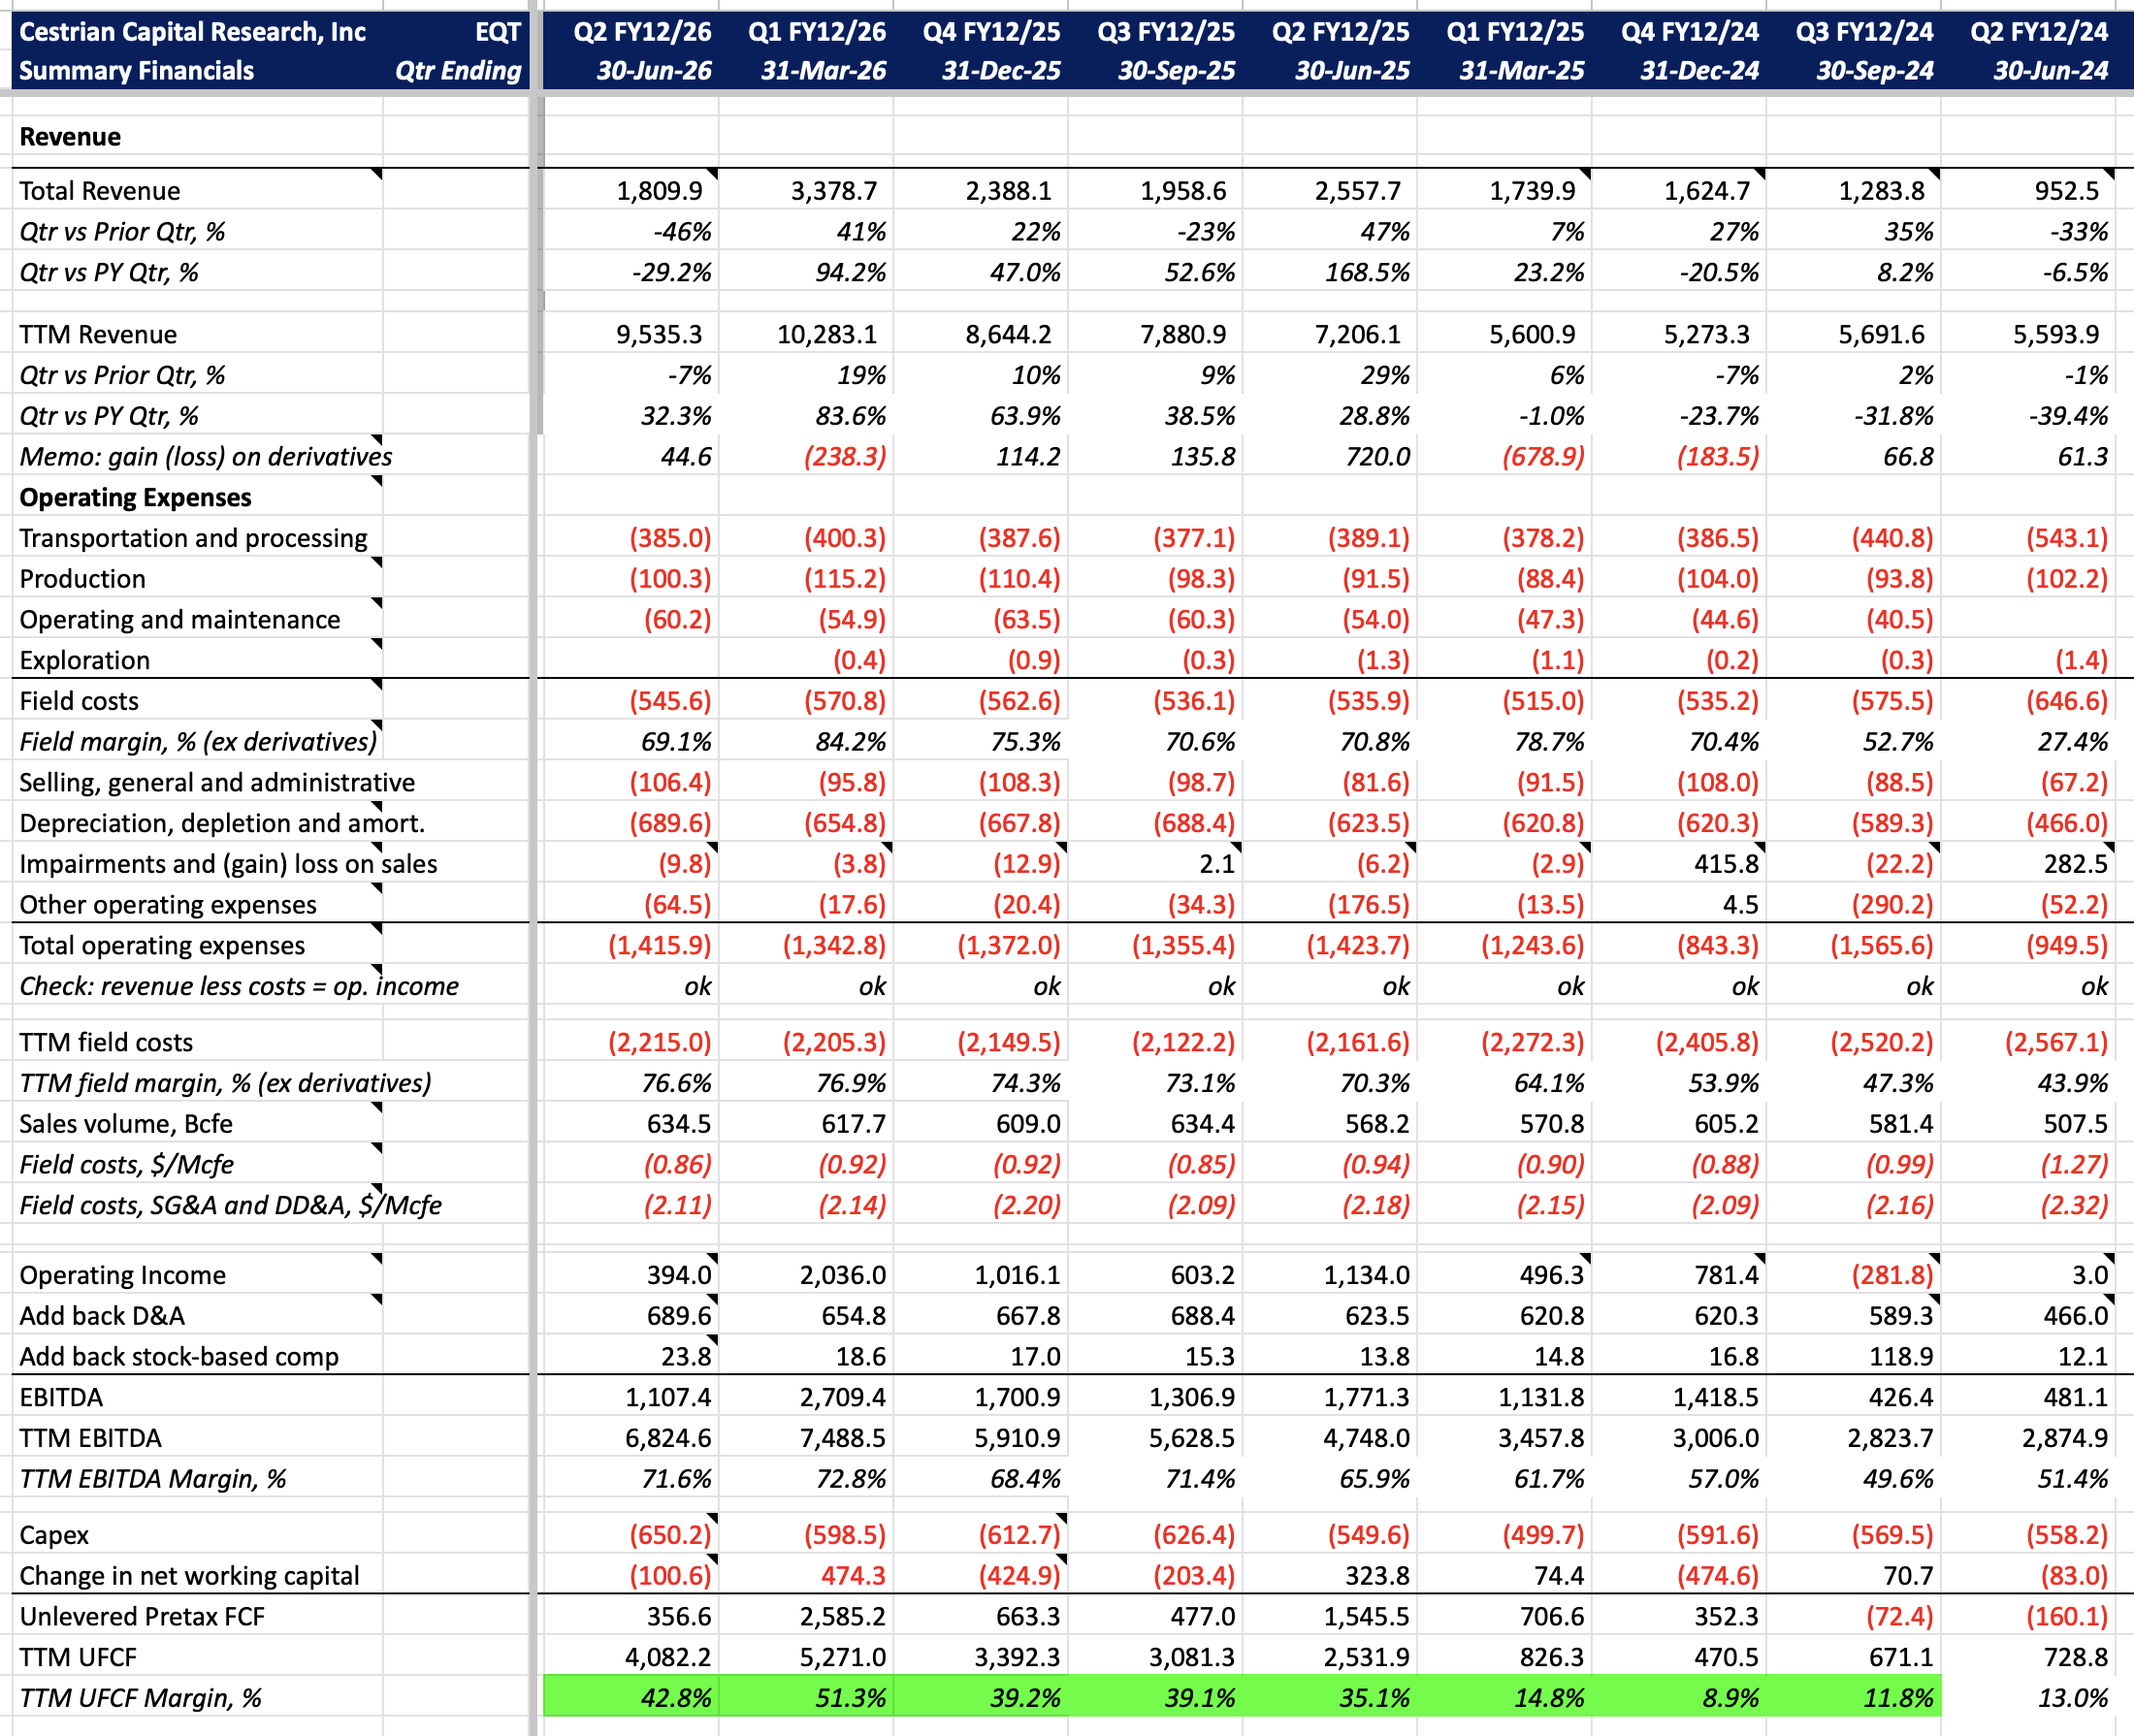
EQT remains tied to roughly $3 Henry Hub gas despite European prices near $23 per MMBtu, with US LNG export capacity limiting overseas…
POSCO Holdings trades at a 78.6% P/B discount as lithium, gas and trading profits reshape the steelmaker, while capex and lithium prices…
 Capital Connoisseur 1 click
Research Roundup covers AAON's data-center cooling ramp, Knife River's margin recovery, ChronoScale's Microsoft-backed neocloud buildout…
Annaly Capital Management’s rate swaps and MBS expansion lifted earnings available for distribution 28% year over year, supporting its…
 Andres Veurink 1 click
Asia's elevator boom favors maintenance and modernization providers, with Otis deriving nearly 90% of operating profit from after-sales…
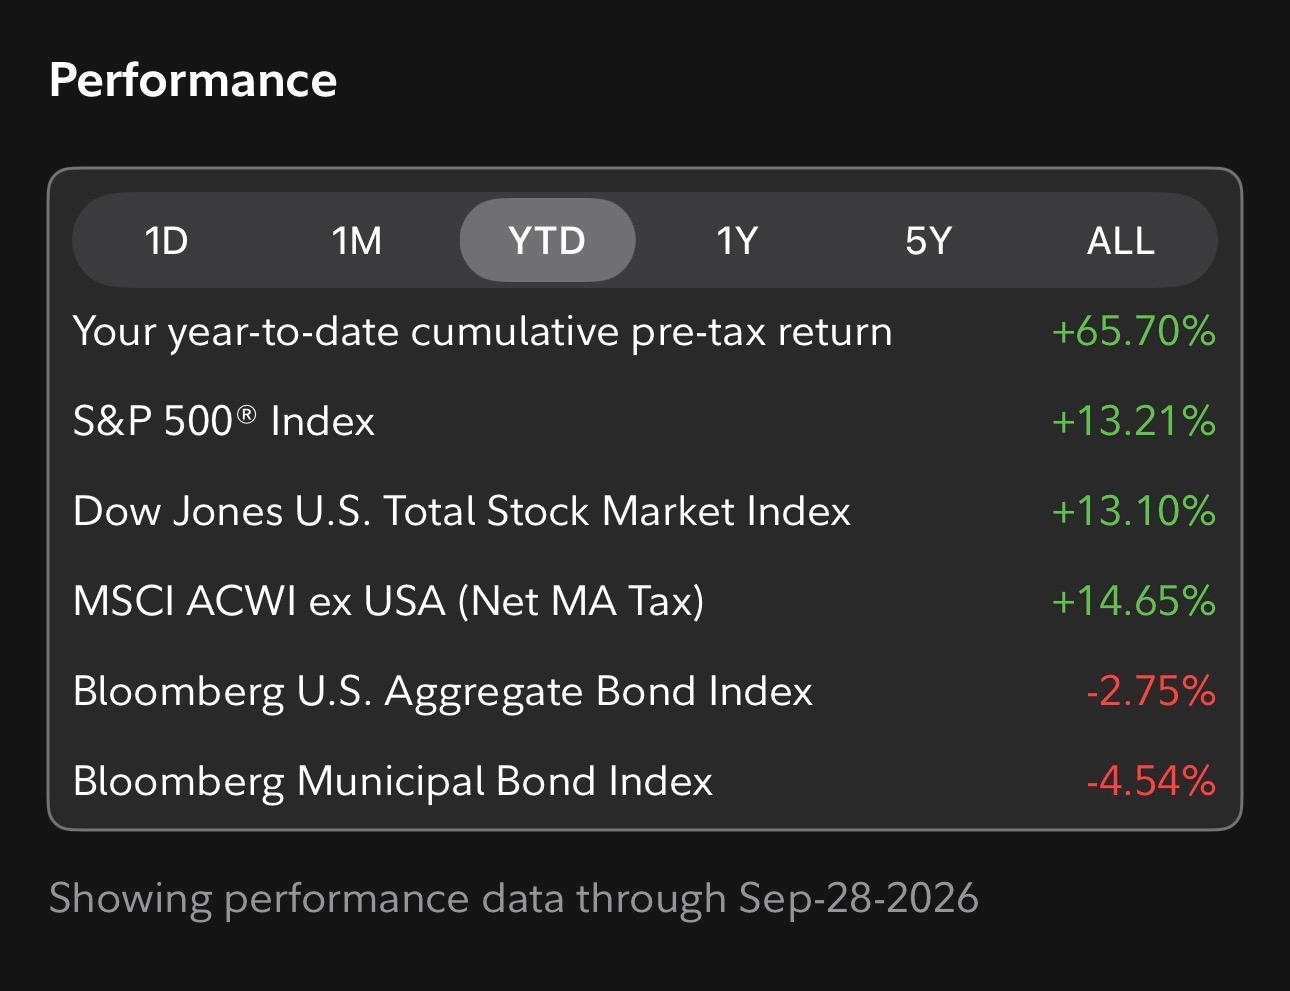
Portfolio returned 65.7% through September 28 versus the S&P 500’s 13.2%, while backing Tourmaline, EQT, Athabasca and SLB on gas demand…
FTAI Aviation’s engine-exchange model swaps CFM56 engines in days rather than 200-day overhauls, driving Aerospace Products adjusted EBITDA…
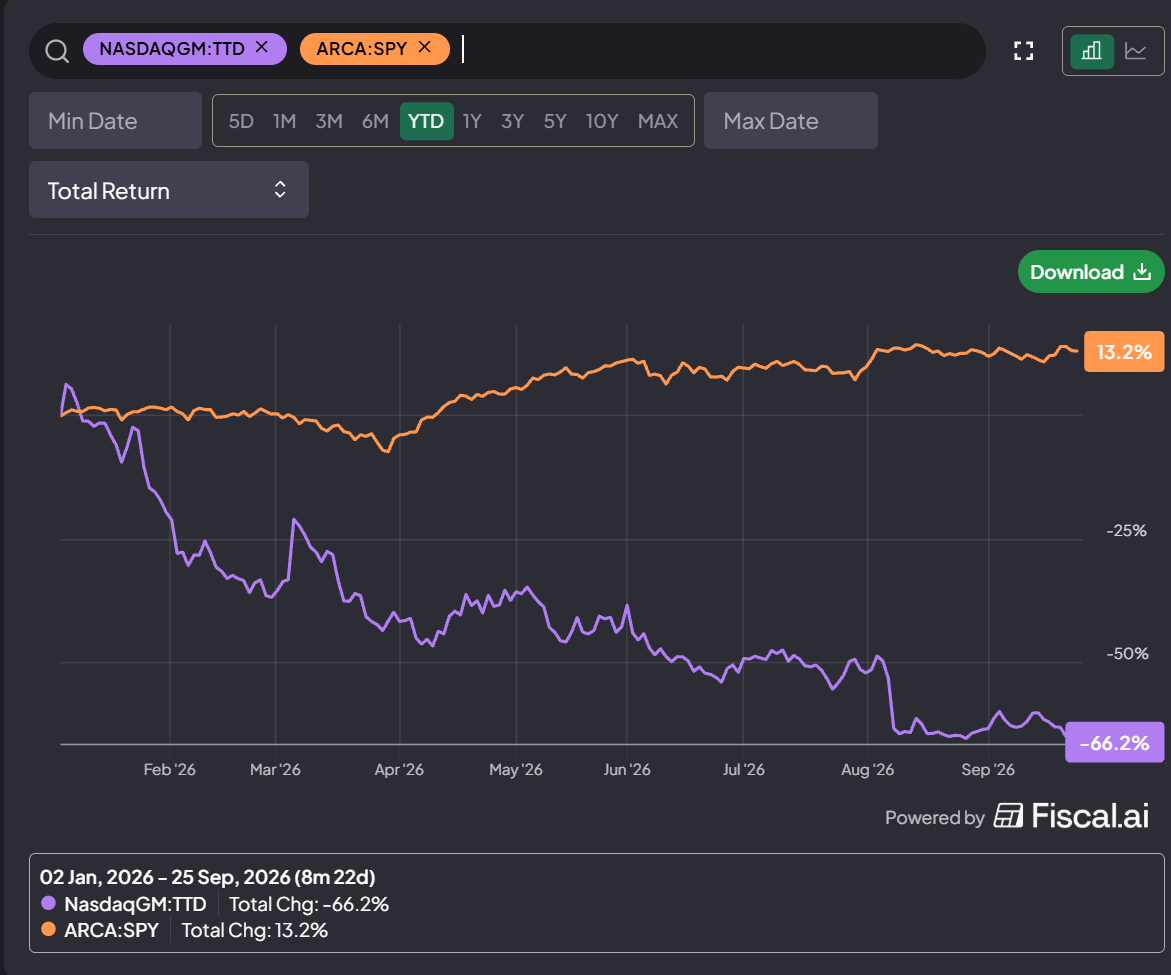
The Trade Desk’s CEO received a new 10-year option package targeting $105 per share as the company seeks shareholder approval to reprice…
Beam Therapeutics’ BEAM-302 AATD gene-editing program anchors its 2028–2029 upside, while a 2–3 year cash runway leaves dilution likely…
 Robert J. Lake 1 click
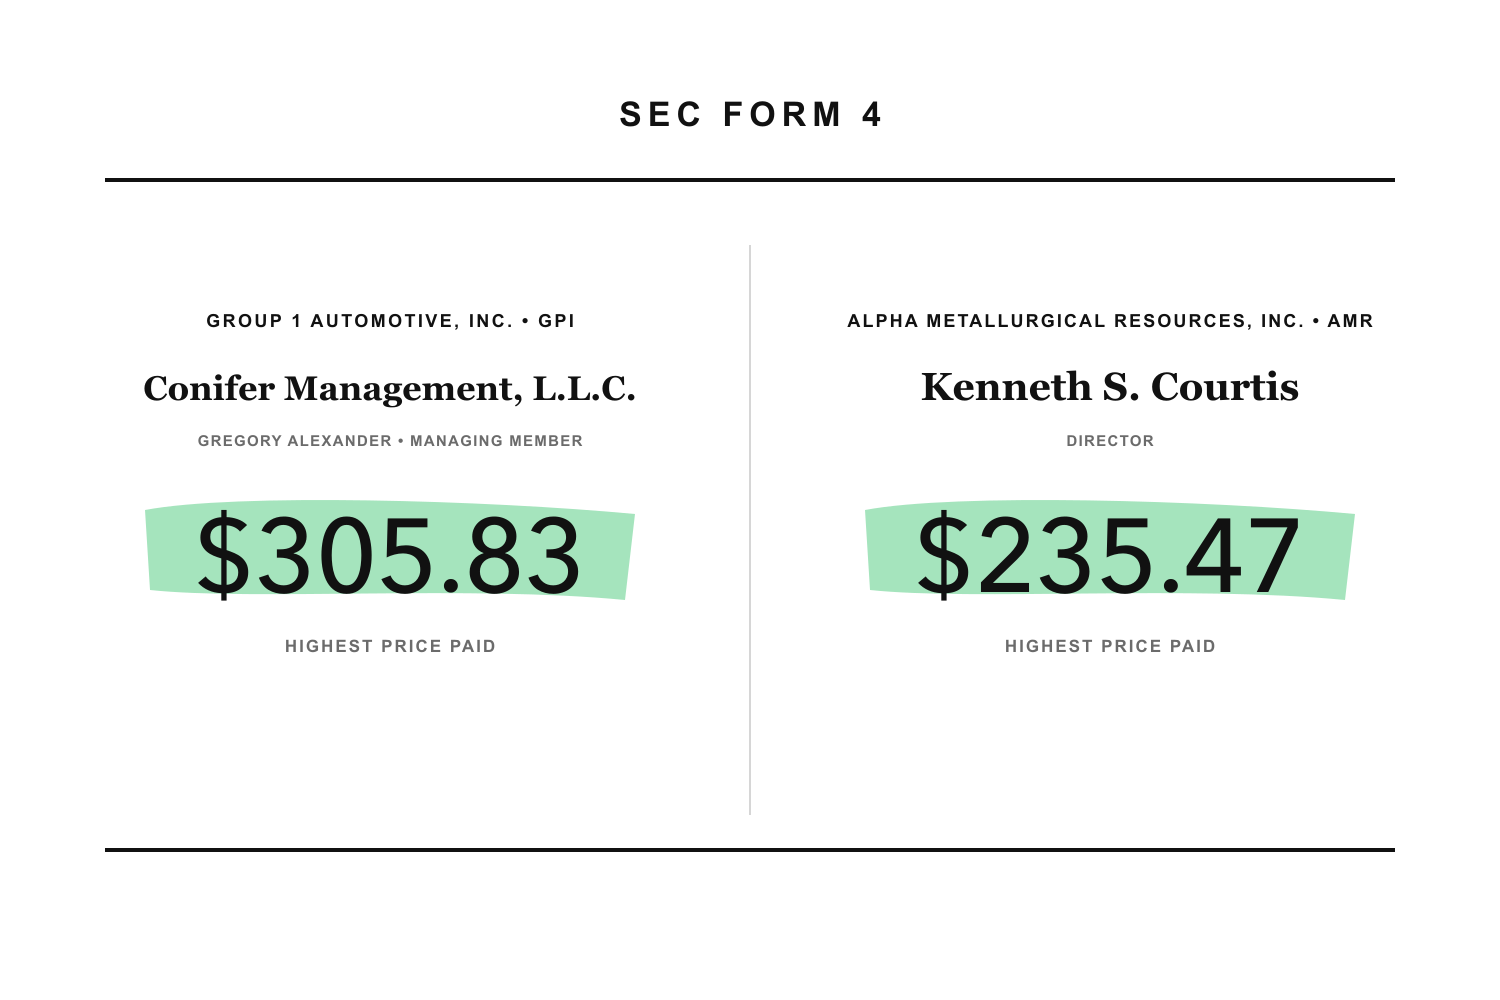
Alpha Metallurgical Resources director Ken Courtis bought $10.5 million above $190 after a blackout lifted, while Conifer’s 12.7% Group 1…
Every publication on this site, hand-picked.
 Albert Anthony Andres Veurink
 Bay Area Ideas Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.