Not So Fast
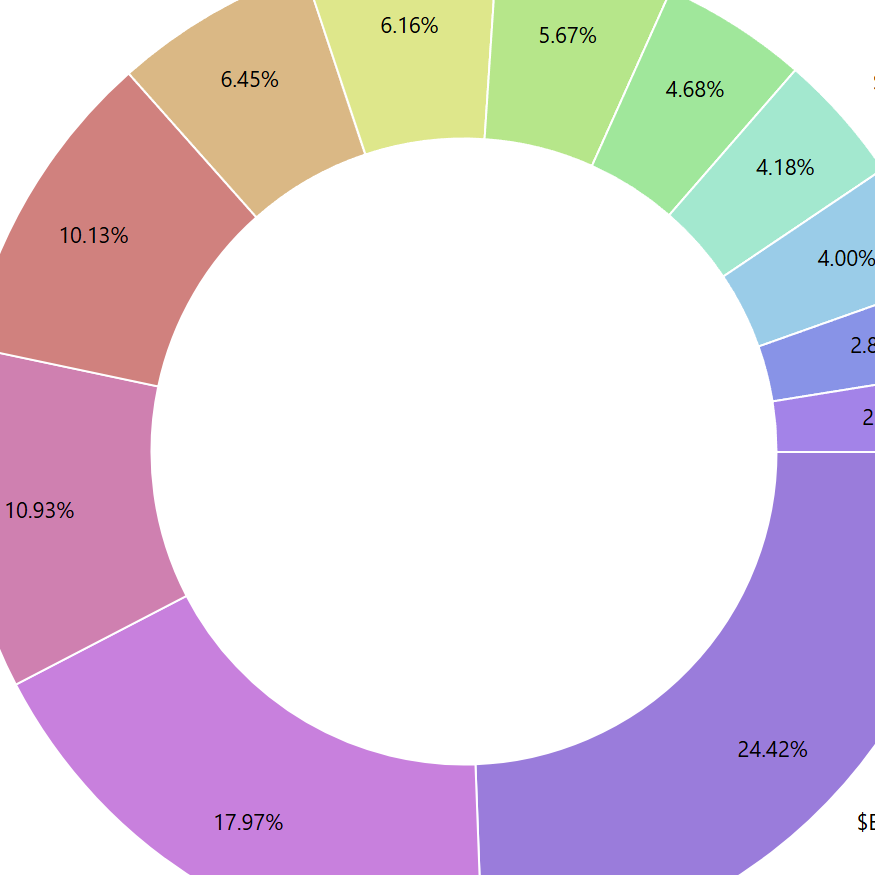
Entravision, the portfolio’s largest position, fell more than 40% from its highs as Q3 returns dropped to 37.8% YTD.
Entravision, the portfolio’s largest position, fell more than 40% from its highs as Q3 returns dropped to 37.8% YTD.
#1 report on $BMBL scuttlebutt in college Girl: “bumble is for old people and wierd” she used tinder for hu and hinge for “quality” Guy: “the gay one?” Went to go scroll on tinder
@JordanBoekel I have skimmed over $FINV, $LX made good money in $YUMC, looked at $PDD. I think management is even more important given regulatory risk and China and that is partly why I like $YB
$SEV shot-chaser 8k this morning boasts of slashing capital needs to $115m S-3 this afternoon says raising up to $250m anyways I'm naked short calls https://t.co/bnw9wOqULl
1/ Went thru Leslie's first day declaration so you don't have to. The biggest US pool supply retailer JUST filed Chapter 11 yesterday with 900+ stores and $787mm of debt. $LESL https://t.co/u4EkUn7zTb
Looks like $APP and $EVC are doing some things together. https://t.co/bzdFqKEJjL
$EVC is going to zero btw https://t.co/1xqmxEbpot
$FUBO 👀 https://t.co/ckSvkUmRyP
Stratus Properties liquidates Austin real estate below projected distributions, while Atlantic Lithium and Intermex await approvals for…
Beyond Meat’s Q2 2026 revenue fell 8.2% as U.S. retail and foodservice volumes declined, while a flatter, not inverted, Treasury curve…
Cullinan Therapeutics plans December 2026 autoimmune updates for CLN-978, while zipalertinib awaits an FDA decision in previously treated…
 Myriam Alvarez 2 clicks
VersaBank uses cash holdbacks and put-backs to buy point-of-sale loan cash flows, with C$7 billion in assets and AI-enabled real-time…
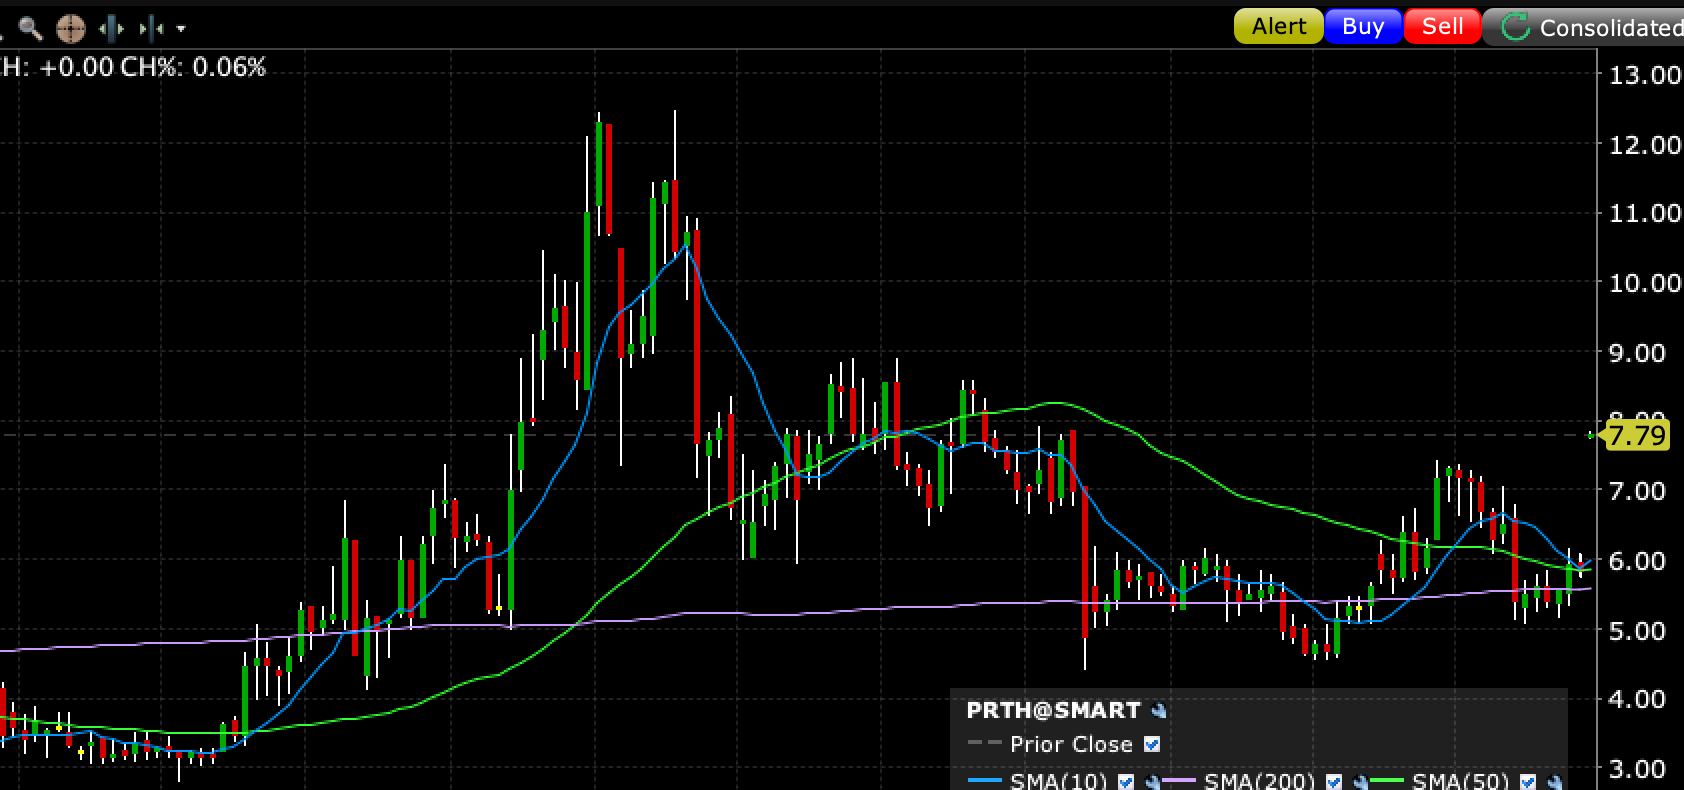
FGPR remains on track, PRTH's management buyout is set at $8.05, and microcap RAVE is described as cheap.
U.S. Treasury yields are testing credit and equity markets, while the discussion also targets recent changes at Glass House (GLAS).
IEH booked $3.6 million in mobile-defibrillator connector orders, lifting its medical revenue outlook and diversifying beyond aerospace and…
EuroDry shares rose more than 300% year to date as dry bulk markets strengthened, but an aging fleet, no dividend and a $20 million equity…
 Henrik Alex 4 clicks
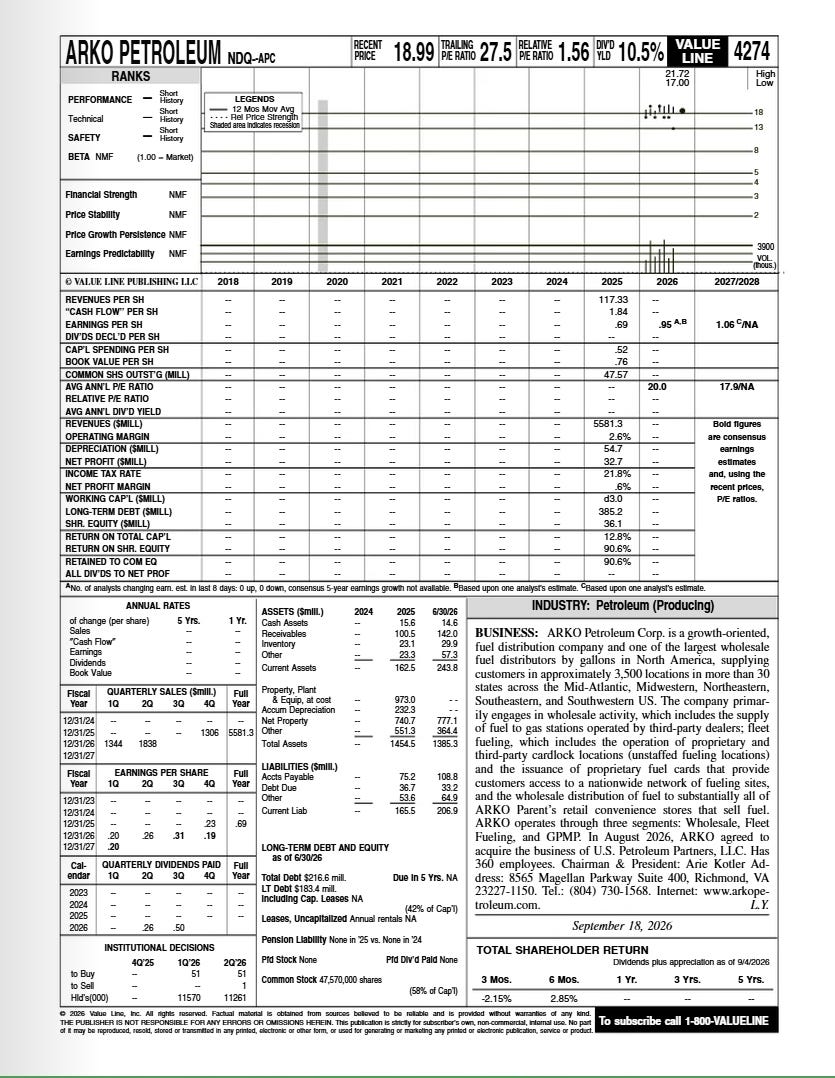
ARKO trades at 3 times estimated 2025 owner’s earnings, while its 73.6% APC stake exceeds its $473 million market cap.
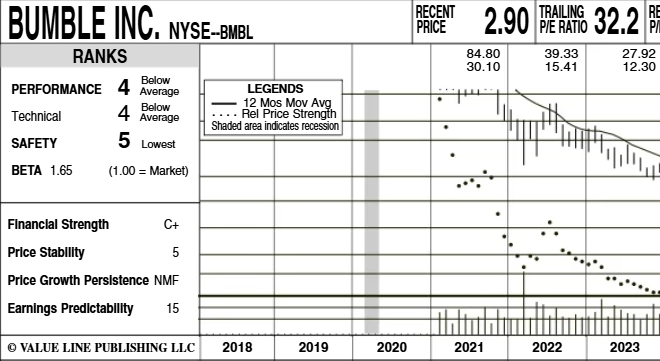
Bumble trades at roughly 2x owner’s earnings and 4.76x enterprise value, with Whitney Wolfe Herd’s return central to a rerating case.
 ELME · long
Elme Communities, a REIT, is nearing the end of a long liquidation process.
Riley Exploration Permian raised oil production guidance after a Q2 beat, targeting 30% growth while trading at 6.52 times forward earnings.
 The Supercycle Investor
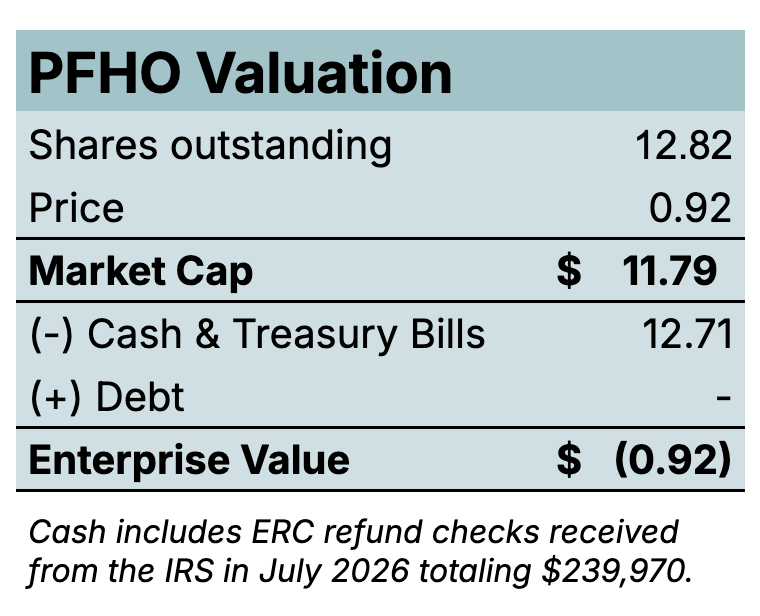
Pacific Health Care trades below its more than $1 per-share net cash despite profitable workers’ compensation claims services, California…
Special-situations survey flags Cooper’s $3 billion buyback, Grab’s $900 million repurchase, and Beretta’s $44.80 partial tender for Sturm…
Beasley Broadcast Group's equity hinges on repaying or arranging sales for roughly $115.5 million of debt by September 2027, before PIK…
LifeMD cut 2026 revenue and EBITDA guidance as subscribers fell and customer acquisition costs reached 59% of revenue, prompting a shift…
 Eli Gooch
Zentek initiation report.
CVD Equipment is winding down manufacturing, cutting half its staff and weighing liquidation, with $23.5 million of cash and a…
Groupon CEO Dušan Šenkypl and CFO Rana Kashyap discuss rebuilding the local-experiences marketplace with AI infrastructure, better…

Independence Realty Trust is buying Centerspace in stock to create an $8.1 billion apartment REIT, targeting 5% 2027 Core FFO per-share…
 Dane Bowler
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Bullionaire
 The Curious Analyst The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.