Power Semiconductors: The Follow-Up
STMicroelectronics, Navitas and Wolfspeed offer contrasting power-semiconductor cases tied to NVIDIA’s 800V AI data-center architecture, spanning an incumbent leader, a speculative…
STMicroelectronics, Navitas and Wolfspeed offer contrasting power-semiconductor cases tied to NVIDIA’s 800V AI data-center architecture, spanning an incumbent leader, a speculative…
@ryanTesling @elliotrades worry isn’t something i do often. a rate hike is a known risk investors won’t like short term, but it changes nothing about my larger $AMZN thesis.
@elliotrades $AMZN
Newest out. Scandinavian Tobacco Group: Shear "Q2'26 note." $STG $PM $BTI $IMBBY $MO $HAYPP https://t.co/frArnxjq8I
A2Gold's McIntosh drilling found 0.23 g/t gold over 65.5m, 370m southwest of the existing resource, and extended mineralization 86m…
Alphabet’s off-grid data centers, Verizon dark fiber and merchant TPU strategy aim to lower cloud costs and generate $84 billion to $108…
 Esxeleryn Analytics 1 click
QXO applies Brad Jacobs’s consolidation playbook to fragmented building materials, anchored by its TopBuild acquisition and a strategy of…
Tencent Music trades at about 8.8 times forward earnings, with membership revenue and Ximalaya integration supporting profitability despite…
 LL Insights 1 click
Steve Eisman, Vincent Daniel and Porter Collins discuss Treasury buybacks, OpenAI risk, gold, hedge fund shorting, and live short ideas…
Rubrik's Q2 results and AI-driven cybersecurity demand have lifted RBRK nearly twofold from its year-to-date low, alongside a larger 2029…
 Gary Alexander 2 clicks
GLP-1 drugs are gaining traction across Asia as Chinese developers advance candidates and Indian generics slash prices, reshaping prospects…
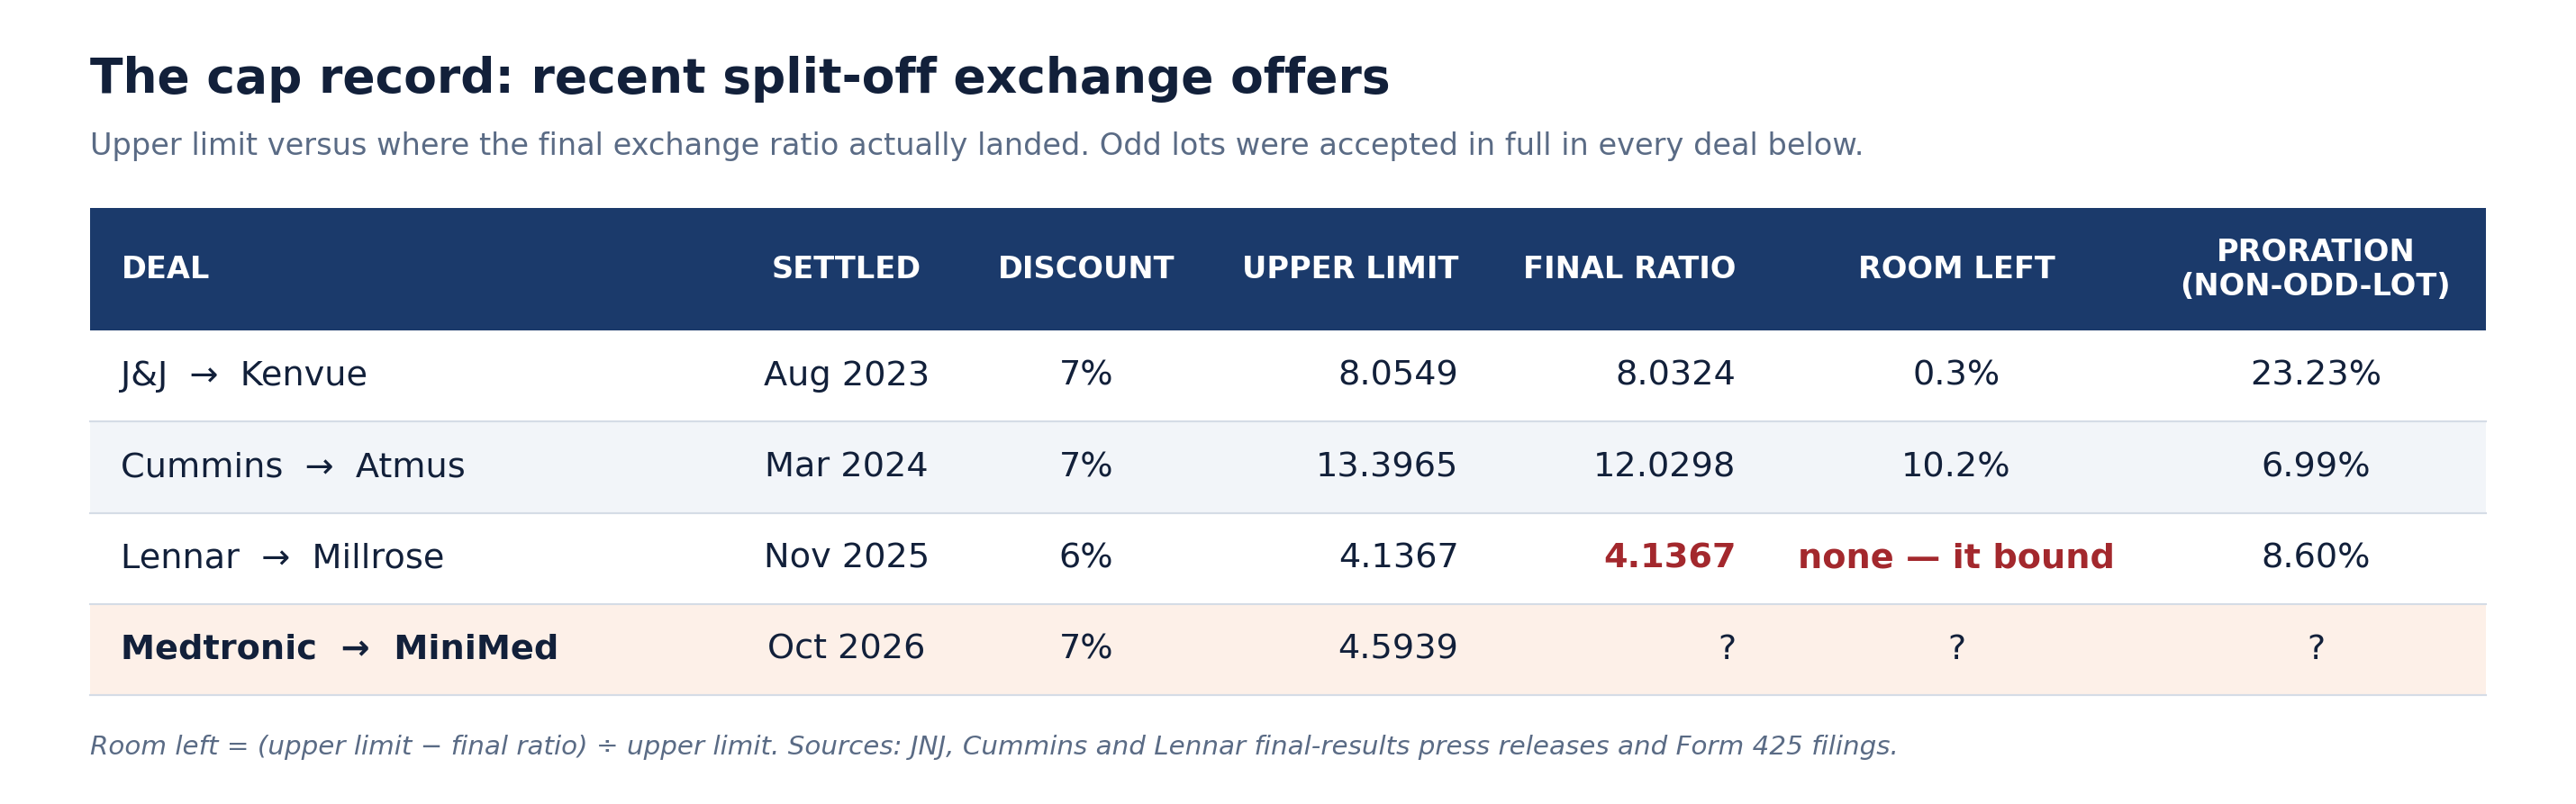
Medtronic’s MiniMed split-off gives odd-lot MDT holders priority on a 7% discounted exchange, but a 4.5939-share cap has begun reducing the…
Meta’s Muse strategy targets the consumer internet through a Trojan-horse product.
Adobe’s fiscal 3Q26 revenue grew 13%, while ARR growth slowed to 9.3% excluding Semrush.
 ZM · long
Zoom Communications (ZM) is presented as a long investment idea.
Lululemon’s Q2 revenue fell 3.2% and core product sales dropped 20%, while tariff refunds masked worsening Americas margins and comparable…
 Gytis Zizys
Amazon’s refrigerated same-day network has lifted monthly perishable customers roughly 50%, using grocery frequency to deepen loyalty and…
Cestrian initiated Joby Aviation at Accumulate and upgraded Applied Materials and Broadcom to Accumulate for the week ended 11 September…

Oracle’s $88.3 billion net debt and $90-95 billion capex plan pushed five-year CDS to 215 bps, despite 121% OCI growth and a $664 billion…
MKS Instruments posted $1.25 billion in Q2 revenue and is expanding Penang capacity for a $200 billion to $250 billion wafer-fab-equipment…
 The Straits Strategist

Adobe’s fiscal 3Q26 revenue grew 13%, while ARR growth was about 9.3% excluding Semrush.
Corning targets AI data-center optical interconnect demand, backed by customer-funded supply agreements and operating margins above 20%.
 Alpha Mantra
Latticework’s weekly briefing covers NVIDIA’s AI demand, Deckers’ de-rating, Shurgard’s asset discount, Flitto’s translation-data backlog…
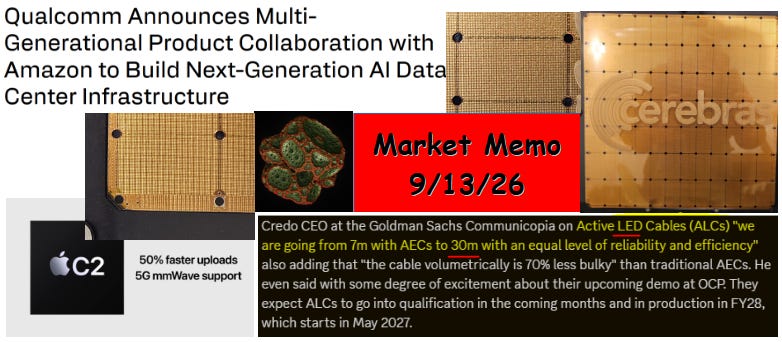
Qualcomm's Amazon coherent-lite DSP work may carry lower margins as Apple’s C2 modem cuts Qualcomm’s iPhone share; Credo’s 30-meter uLED…
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.