Jumia
Jumia’s January 2028 $7/$15 call spread risks $1.15 for up to $6.85 if cost cuts and marketplace growth deliver adjusted EBITDA and cash-flow breakeven in Q4 2026.
Jumia’s January 2028 $7/$15 call spread risks $1.15 for up to $6.85 if cost cuts and marketplace growth deliver adjusted EBITDA and cash-flow breakeven in Q4 2026.
$DAKT Just won the massive jumbotron project for the new Titans stadium. Estimated to be $180M. Will be the largest set of displays in the NFL. Bills, Browns stadiums to be announced soon. Wouldn’t be surprised if Mitsubishi acquires them given interest in the category.
$NX 5% of COGS/ direct input costs sourced from China. Tariffs + zero pricing power, high fixed cost structure + only 30% GMs = 25-30% hit to EBIT. Add 4x leverage, declining volumes, ambitious mgmt guidance while integrating a large acquisition is a setup for a trainwreck.
$DAKT CEO departing, new high-quality CFO (temp) w very attractive secular tailwinds in digital display demand + activist involvement = increased likelihood of takeout. Optimal business for PE. Multiple logical strategics. +75% upside.
$NX Outlandishly guiding to flat 2025 sales, customers and channel -DD. Commodity window and door components facing pricing pressure from larger customers ($JELD, $OC). Now levered 4x, trading at a premium to higher value-add building products peers. Guide cut inevitable.
$NX Rapidly declining levered (4x) commodity biz. Q1’25 guide -12% sales, mgmt hoping for 2H’25 recovery. End-mkts deteriorating ($OC -20% Q4 guide, $JELD), customer losses, internal controls issues, integrating a large acq, 0 prior M&A experience. +30x P/E on best case 2025 #s
$AS 50x P/E levered retail roll-up w only one decent asset (Arc’teryx). Stagnating in the US, nearly fully-penetrated in China. >$500 jackets didn’t work for $GOOS in Asia. Arc already bigger. Hyper promotional mgmt sent the stock skyward. This is going to be an epic crash.
$DAKT New $50M display upgrade award for the Miami Heat arena. Will be a nice boost to current quarter earnings (FQ2'25). https://t.co/sLAFBEerYi
$NX Just acquired peer Tyman. >3x leverage, never done a deal before, commodity business, customers all cutting numbers w deteriorating resi remodel activity ($AMWD yesterday, $MBC, $OC, $JELD). Stock is trading at close to 14x EPS. Seen this movie before. Earnings next week.
Entravision’s ATS revenue rose 230% to $182.8 million in Q2, but shares fell from above $14 to about $8 after management forecast…
Navient trades near 40% of tangible book as Gator Financial Partners argues private student-loan growth and restructuring can reverse its…

Pernas Research names Capstone Energy and Stabilis Solutions as AI data-center power beneficiaries, alongside Tenable, Upwork, Wise and…
Butler National Corporation is the subject of a stock pitch presented at the MS Microcaps Summer Virtual Conference.
Diversified Energy cut $233 million of debt in 1H26, repurchased $93 million of stock and sold $273 million of land and assets while…

Lionheart Holdings’ 41-cent CUBWW warrants hinge on a SPAC merger valuing KEO Energy’s Venezuelan PetroUrdaneta stake at $1 billion, versus…

Cematrix posted record Q2 revenue of $18.7 million, up 76%, and $3.5 million of net income, while backlog fell 9% from year-end.
OTC Markets gives smaller, distressed, and lightly disclosed companies a trading venue outside NYSE and Nasdaq, with lower listing barriers…

A debt-free American manufacturer now trades at roughly 7x annualized Q2 EBITDA, with $7.35 per share in net cash and a tender floor 18.5%…
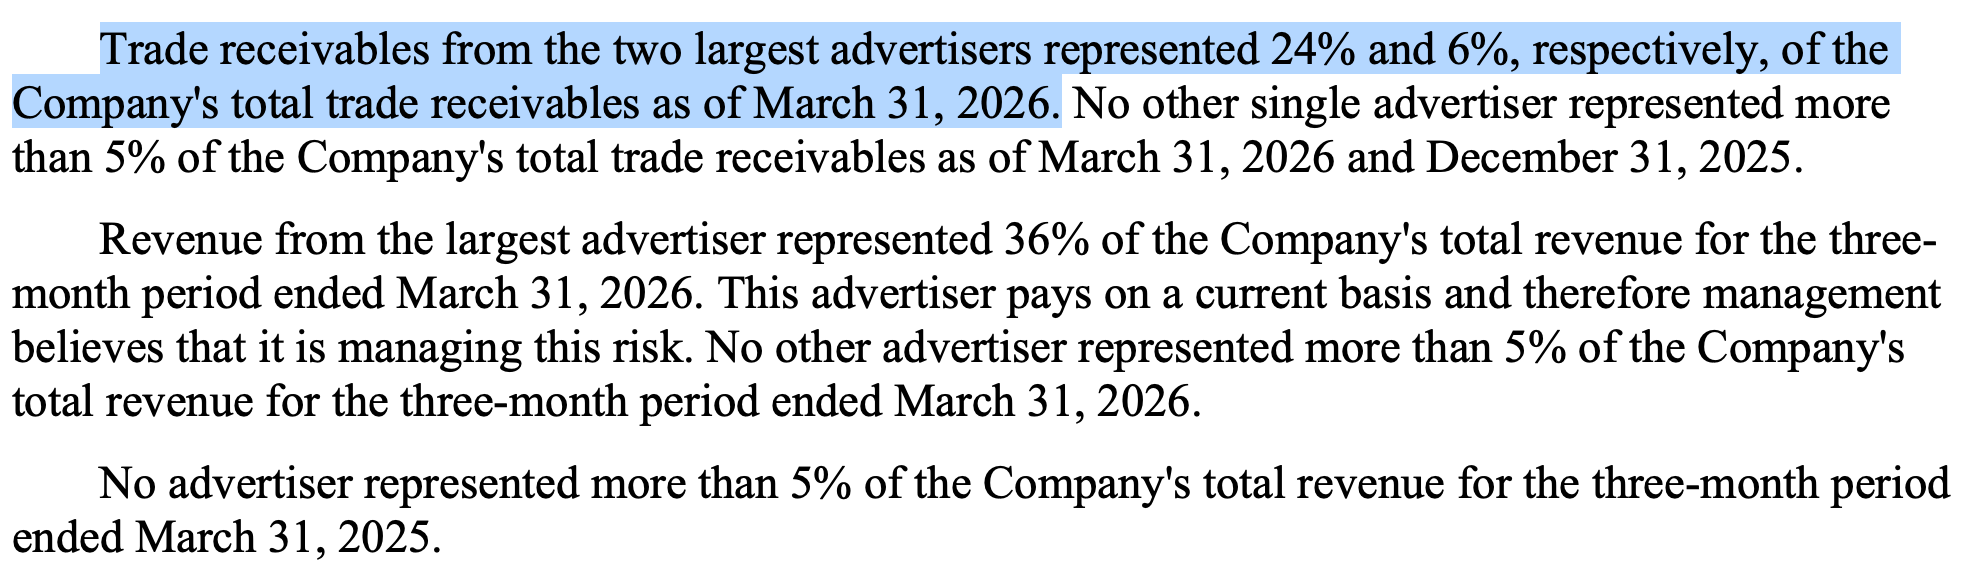
Entravision’s Q1 filings contain a new footnote disclosure pointing to a potential second large advertiser beyond its Hong Kong customer,…
 LEEEF · long
LEEF Brands, California’s largest cannabis extract manufacturer, supplies distillate, live resin and rosin to leading California brands.
Seer trades at $2.04 against $3.90 per share of net cash as activists press a board that rejected five buyout proposals and won reelection.
Biorem reported 66% revenue growth and over 260% profit growth after trading at 11.3 times earnings and 5.9 times EV/EBITDA.

An aerospace company’s profitable core is obscured by a long-running FAA development program; approval, abandonment, or shrinking losses…

AirIQ’s 2025 revenue rose 17% to $6.5 million, but tax reassessments cut net income 50% and lifted its P/E to 144x.

Gatekeeper Systems’ revenue rebound is overshadowed by $19.3 million in nine-month operating cash burn, swelling inventory and overdue…
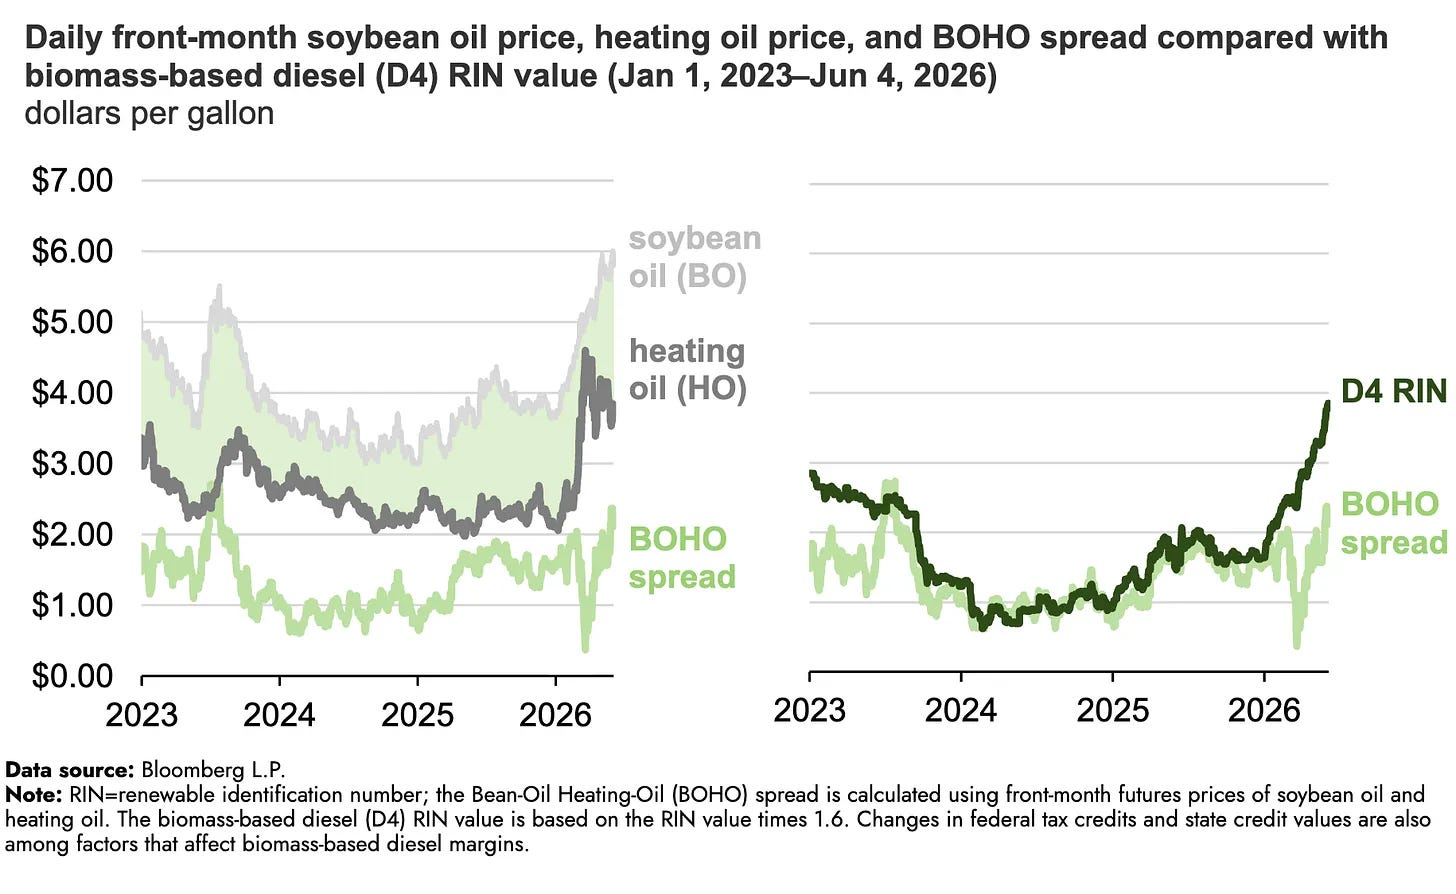
RIN prices near all-time highs reflect tighter renewable-fuel mandates, a shrinking credit bank, and biodiesel production shortfalls.

Braemar’s BHR-PB preferred trades near $13 against a $25 liquidation preference, yielding 10% amid hotel sales, a $480 million Ashford…

Diversified Energy (DEC) has paid $21.84 per share in dividends since June 2017 and trades at $13.35 amid a bullish U.S.

Stitch Fix’s rushed Freestyle pivot cannibalized its profitable Fix business, driving active clients below 3.4 million, quarterly revenue…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.