New Ask Claude or ChatGPT about any stock, using Bullpen. Bullpen in Claude or ChatGPT. 7 days free

Wednesday, November 11, 2026

Back to the front page

From X

@StableBread

Fajasy on X

Elmet $ELMT, the U.S. tungsten parts maker, reported a record $347.4M backlog for Q3, with two U.S. defense stockpile awards making up $197.5M (56.9%) of the total. The Defense Logistics Agency (DLA), which runs the National Defense Stockpile, has funded $161.9M so far under its contract to buy up to $2B of tungsten ore and concentrate from $ELMT, already more than the $150M minimum it guaranteed. Each order under the contract can take up to 48 months to deliver, and $ELMT said in its October 1 deck that it doesn't intend to start deliveries "until sufficient incremental new supply is available." I wouldn't expect much of the $161.9M to show up in revenue before 2027. The other $35.6M is a DLA award for mostly molybdenum products that $ELMT's plants already make, and the 10-Q's own chart counts it in the $149.5M of aerospace and defense backlog. Take out both and backlog is $149.9M, up 14.0% from $131.5M as of July 3 and 71.7% from $87.3M as of September 30, 2025. In my August 16 update, I said I wanted to see the first backlog print with the new defense appropriation cycle. Without the two stockpile awards, aerospace and defense backlog grew 15.8% in Q3 to $113.9M, a bit slower than its 16.5% growth in Q1 and 17.8% in Q2. I don't see a step-up from the new appropriation cycle yet, and part of the growth is price: The 10-Q credits "tungsten material price flowing through to our end product pricing" without splitting price from volume.
@StableBread

Fajasy on X

Elmet $ELMT, which makes tungsten and molybdenum parts for U.S. missiles and jets, saw its main division's gross margin rise to 31.8% in Q3 from 20.1% a year earlier, and management credits the jump mainly to how it bought and priced tungsten during Q1 2026's price spike. Revenue rose 55.6% to a record $79.6M, and tungsten products went from 14.8% of $ELMT's shipments in Q3 2025 to 33.6% in Q3 2026, which the 10-Q attributes to (1) price increases tied to higher input costs and (2) more volume from aerospace and defense customers. Meanwhile, $ELMT's microwave products division, which makes radio-frequency systems rather than tungsten parts, grew revenue just 4.4%, and its gross margin fell to 26.1% from 30.7%. $ELMT values its inventory on a first-in, first-out (FIFO) and average-cost basis, so Q3's cost of goods sold still reflected tungsten bought earlier in the run-up, while $ELMT's selling prices had already risen with the market. Its $152.8M of inventory as of October 2, up from $69.7M as of December 31, equals ~8 months of Q3's cost of goods sold, so most of what's on hand was bought after prices took off. Since then, tungsten prices have stalled: European ammonium paratungstate (APT), the traded form of tungsten, was quoted at $2,500-3,100 per metric ton unit (MTU, 10 kg of tungsten trioxide) in the week to November 5, per Shanghai Metals Market, vs. $2,900-3,100 on September 10. Q3's adjusted EBITDA margin was 21.3%, up from 12.0% in H1 2026. Unless tungsten climbs again, I'd treat part of the jump as a timing gain that fades as inventory bought at 2026 prices flows through. In my July 2 write-up, I picked $ELMT as the safest way to own China's tungsten squeeze, since it makes the parts instead of mining the ore. Q3 shows $ELMT's margins still move with the tungsten price, just with a lag. $ELMT's own 2031 plan assumes APT at $1,500/MTU, 40-52% below the November 5 quote.
@StableBread

Fajasy on X

Quantum $QMCO, the tape library maker, just reported a record backlog of nearly $100M as of September 30, more than double the record $45M as of March 31! $QMCO’s revenue rose 42.9% to $89.6M in the September quarter (fiscal Q2), $5.6M above the top of its $82.0M ±$2M guidance, and adjusted EBITDA of $11.1M beat the top of its $6M ±$1M guidance by $4.1M. Secondary storage, mainly tape systems, grew 126.2% from a year earlier to $44.7M, half of revenue, up from 32%, with hyperscale demand up more than 2.6x. CEO Hugues Meyrath said on the March-quarter call in June that $QMCO “should see a lot more tape drives” from $IBM, its drive supplier, in the September and December quarters, letting it convert its tape library backlog into revenue. Instead, backlog more than doubled, and Meyrath said on the September-quarter call that demand remained ahead of supply, “particularly media and tape.” He said $IBM’s “statement of direction” is to double its tape drive output year-over-year, but “we just don’t know how quickly IBM is going to ramp tape drives.” Chief accounting officer Hiral Patel added that revenue beat guidance “primarily due to price and volume mix,” and that she expects pricing volatility from component shortages “to remain a headwind going forward.” $QMCO guided December-quarter revenue to just $91.0M ±$2M, up 1.5% at the midpoint, and said any upside depends on how many components it can get. It also guided adjusted EBITDA down to $9.1M ±$1M from $11.1M, as operating expenses rise with commissions and R&D hiring. That revenue guidance still runs at $364M/year, above the $360M of FY2028 revenue (year ending March 2028) in the base case of my October 28 update. At $19.70/share after hours, close to the $20.25 in that update, $QMCO’s EV is 2.4x TTM revenue, down from 2.8x. It’s also 21.6x the December quarter’s adjusted EBITDA guidance, annualized, down from 34.4x the September quarter’s. So I read the quarter as $QMCO already running at my base case’s revenue, with the bull case’s $400M still depending on $IBM’s drive supply. What I’d want to see in the December-quarter results: 1) IBM: Meyrath saying $IBM’s tape drive output rose, since my bull case assumes it ramps early in 2027. 2) Backlog: Revenue above the $93M top of guidance and backlog below ~$100M, which would mean $QMCO is shipping orders faster than new ones come in. 3) Gross margin: Holding near the September quarter’s 41.0%, even though the guidance midpoints imply under 40% by my math.

Seed Corn

Chiron’s failed $49 million Beaumont sale and $178 million Pinnacle acquisition leave XRN with $70 million of liquidity and medical-office…

Post Q3 EVC Update

EVC's Q3 update cites $30 million for a single station, a broadcast-business sale and stronger positioning for 2027.

Entravision Q3 Update

Entravision’s Q3 ad-tech revenue reached $177.2 million, up 133% year over year, while total revenue rose 88% to $226.3 million and diluted…

GREAT DEC-TECTIVE WORK

Diversified Energy reported $255.6 million of “true” nine-month free cash flow, while its $1.8 billion Birch acquisition would shift…

Verra veerer

Verra Mobility’s Avis termination threatens 2027 earnings, while Government Solutions profit rose 25% and implied fourth-quarter guidance…

FINV · long

Finvolution Group

FinVolution, a China and ASEAN unsecured consumer lender, trades at 4x earnings and 0.5x book value.

The Verra Sneerer (NASDAQ:VRRM)

Verra Mobility renewed Hertz tolling management for five years. AutoKinex lets rental customers buy tolling, fuel and protection products…

Portillo’s: Strategic Reset

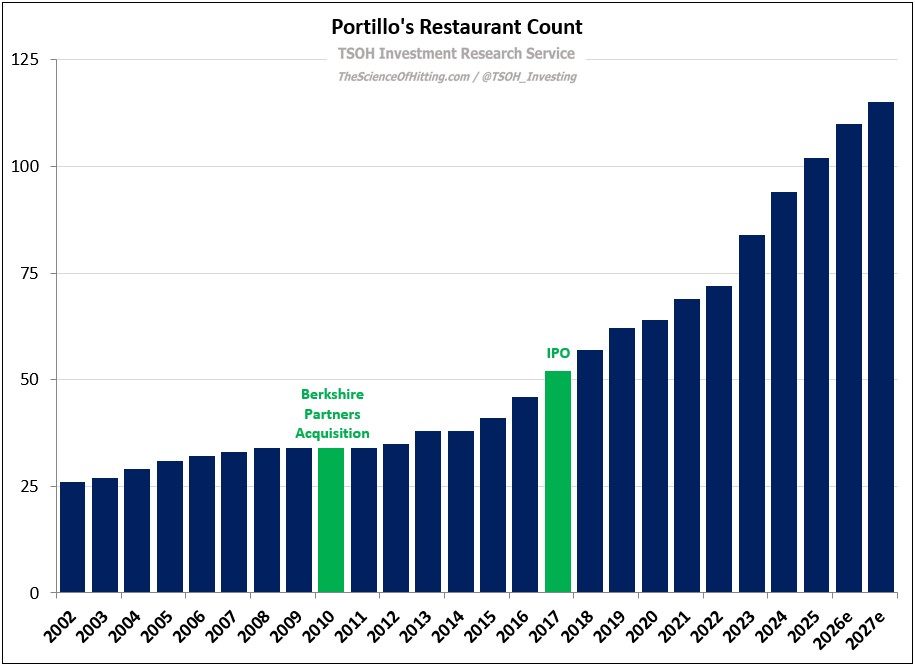
Portillo’s reset follows weak Texas unit economics, cutting next year’s openings to five from roughly 10 annually and shrinking store…

Publications we follow

Every publication on this site, hand-picked.

130 publications

Newsletters 110

X accounts we follow

Every account on this site, hand-picked.

91 accounts

Investor letters we follow

369 firms

Sectors

Ordered by how often our editor reaches for them.