Aura Biosciences expects pivotal Phase 3 bel-sar data in early choroidal melanoma in 2027, funded by $323.8 million of cash into the first…
SA Equity Eagle Oct 31 Markel spent $315 million repurchasing shares in Q3 as Thrive agreed to buy ADT for $7.6 billion and Hasbro cited rising adult toy demand.
S TSOH Investment Research Oct 30 1 click
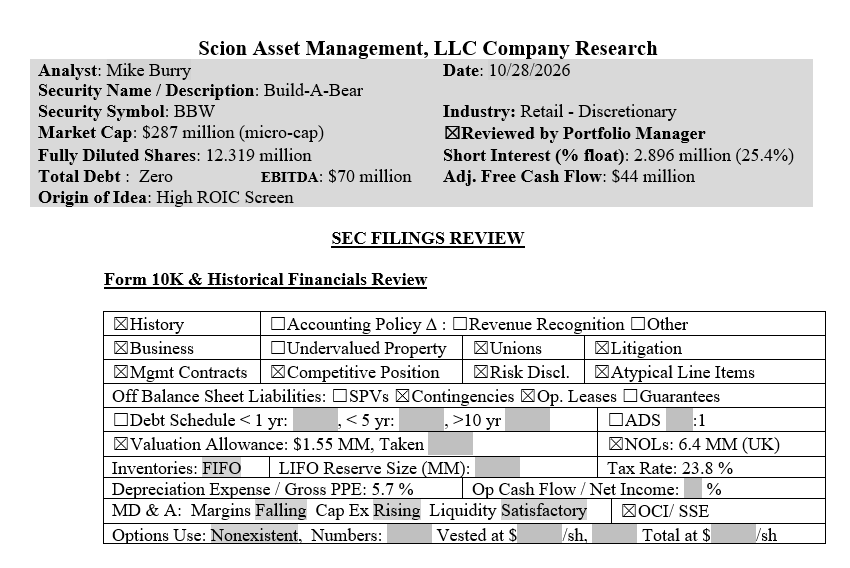
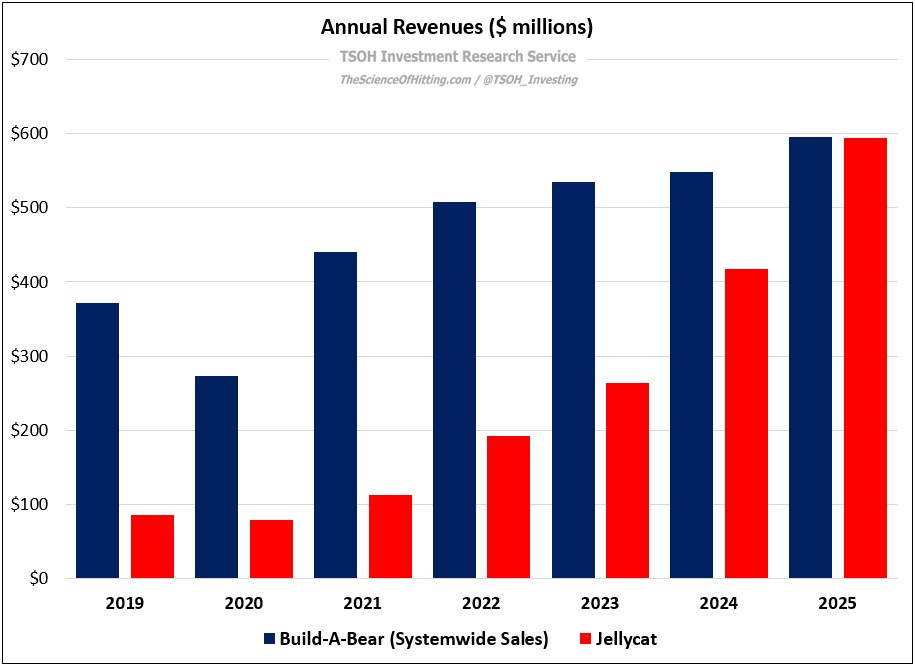
Build-A-Bear’s lease overhaul, off-mall expansion and partner-led wholesale growth reshaped a debt-free retailer with $80 million EBITDA,…
S Cassandra Unchained Oct 29 3 clicks
Mattel, Winnebago and PayPal lead 37 special situations spanning activist campaigns, buybacks, M&A and strategic alternatives.
S Latticework by MOI Global Oct 29 3 clicks
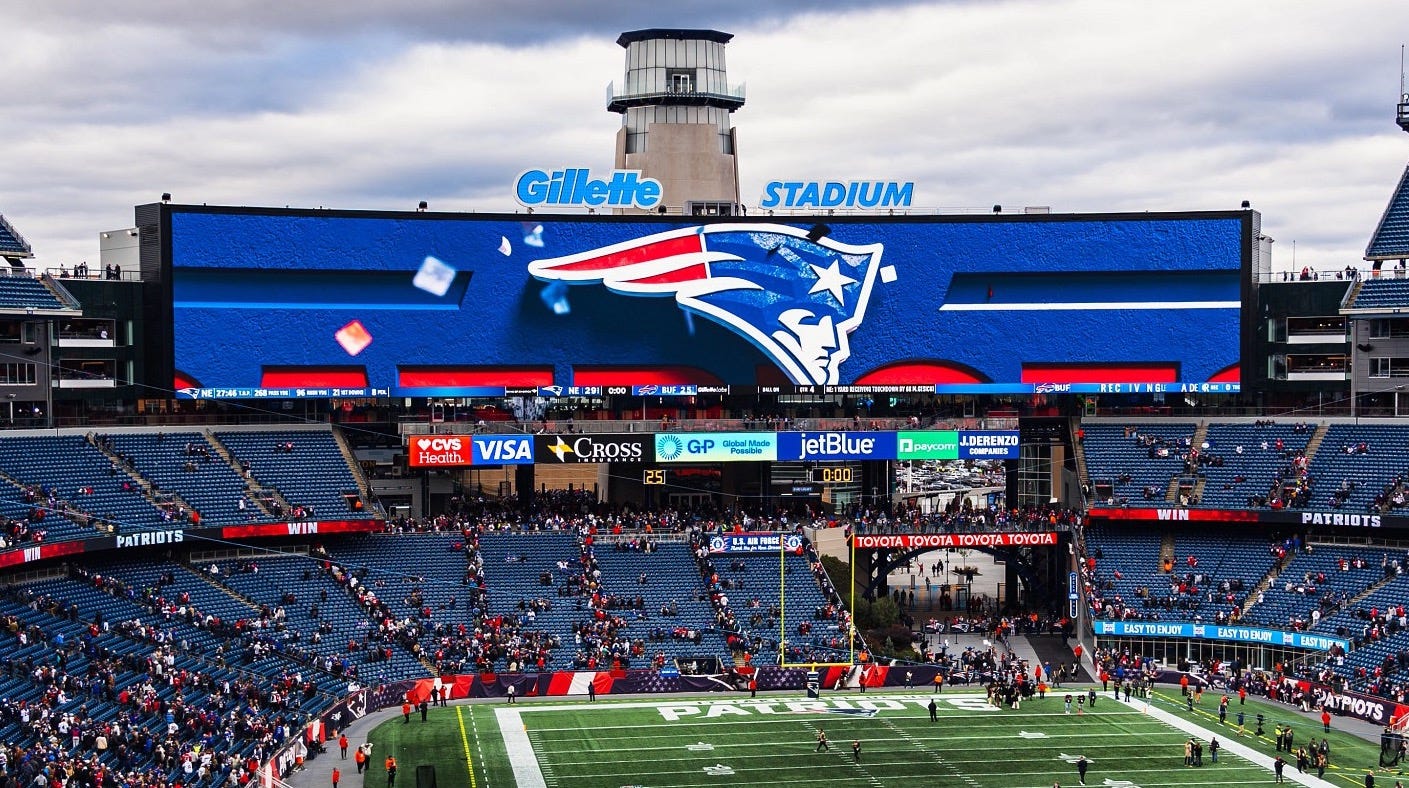
Daktronics, the leader in U.S. sports video boards, targets 10-12% EBIT margins after shifting production to China and Mexico and exiting…
S Hidden Gems Investing Oct 28 6 clicks
Build-A-Bear Workshop’s failed pre-made toy line compressed margins, but resilient children’s sales support a $39.39 fair value estimate…
SA Rafa F. Oliver, CFA Oct 26 4 clicks A four-layer 10-K framework tests revenue timing, receivables, reserves and depreciation against cash flow, using Hertz’s 2012-14…
S Jimmy's Journal Oct 26 69 clicks
Kingstone Company is replacing quota-share cessions with catastrophe reinsurance, lifting quarterly EBIT margin to 29% from a 24% sector…
SA Given Mahlangu Oct 25 3 clicks Six Value Line small caps including Blackbaud, Marqeta, Ranger Energy and Definitive Healthcare trade on net cash, buybacks, low multiples…
S Calvin Blissett Oct 24 81 clicks
ERock’s modular microgrids bridge data-center power gaps years before grid interconnects, with Meta and Anthropic projects filling capacity…
S Monte Independent Investment Research Oct 23 11 clicks
ONT · long Onterris, formerly Montrose Environmental Group, trades at 8.6x next-12-month EBITDA as an environmental consulting and response services…
BL Value Investors Club Aug 4 1 click
BMBL 2026-10-21 Bumble agreed to a $6.05-per-share cash sale to Ithaca Holdings, 136% above its October 2 share price.
S Modern Value Investing Oct 21 8 clicks
Sagimet Biosciences' denifanstat enters a fully funded U.S. acne registration trial after Phase 3 results, with SGMT trading below cash and…
SA Equity Eagle Oct 21 3 clicks Lanxess can force Advent to buy at least half its Envalior stake in April 2028, potentially raising about €745 million to reduce net debt.
S Trade Ideas Flow Oct 19 21 clicks
Eagle Point Credit's NAV is down 25% YTD and shares nearly 50%, while its expense ratio climbed to 9.21% despite a 25% yield.
SA Anthony Cataldo Oct 19 5 clicks Build-A-Bear's push into prestuffed toys and broader retail distribution tests brand stretchability, but recent results warrant caution.
S TSOH Investment Research Oct 19 18 clicks
LendingTree derives roughly two-thirds of revenue from insurance and trades near 4 times expected adjusted earnings despite record revenue,…
S Substack von Philipp Oct 19 11 clicks
First Financial’s merger with First Illinois Financial is expected to lift net interest income and ROE from 2027 after Q2 net income rose…
SA Sorrento Research Oct 18 2 clicks Bumble agreed to a $1.3 billion take-private deal, while Netflix cut about 1,000 jobs and Meta discussed its Muse superintelligence models.
S TSOH Investment Research Oct 16 12 clicks
Park Aerospace’s 11% Q2’27 sell-off overlooks sole-source PAC-3 rocket-motor materials and A320neo engine composites, with missile capacity…
S Monte Independent Investment Research Oct 15 14 clicks