How to Read a 10-K Like a Short Seller
A four-layer 10-K framework tests revenue timing, receivables, reserves and depreciation against cash flow, using Hertz’s 2012-14 accounting as a case study.
A four-layer 10-K framework tests revenue timing, receivables, reserves and depreciation against cash flow, using Hertz’s 2012-14 accounting as a case study.
JetBlue Shares in Tailspin as High Fuel Prices Threaten Turnaround $JBLU https://t.co/spn5aUcvVd
@CorpusCol Speaking of pretty smart- These were spot on. $MNSB $SOUB $NEWT et al https://t.co/v0MLJnLLH3
@FredCam53180687 @JustBankStocks @OurBank3 Yes, Bill is correct. I will stay too long on both though also. Mastly as a tax avoidance and salute to Joe Stilwell for his brilliant move in getting Ken to second step $NECB.
All gaps get closed. $MAMA https://t.co/vlGyf4E8MW
I'm long $BWMX so not complaining but anyone know why it is up so much today? Earnings were last Thurs, and just so-so. https://t.co/MJaqLpvZi0
ERock’s modular microgrids bridge data-center power gaps years before grid interconnects, with Meta and Anthropic projects filling capacity…

Bumble agreed to a $6.05-per-share cash sale to Ithaca Holdings, 136% above its October 2 share price.
Sagimet Biosciences' denifanstat enters a fully funded U.S. acne registration trial after Phase 3 results, with SGMT trading below cash and…
 Equity Eagle 3 clicks
Lanxess can force Advent to buy at least half its Envalior stake in April 2028, potentially raising about €745 million to reduce net debt.
Eagle Point Credit's NAV is down 25% YTD and shares nearly 50%, while its expense ratio climbed to 9.21% despite a 25% yield.
 Anthony Cataldo 5 clicks
LendingTree derives roughly two-thirds of revenue from insurance and trades near 4 times expected adjusted earnings despite record revenue,…
First Financial’s merger with First Illinois Financial is expected to lift net interest income and ROE from 2027 after Q2 net income rose…
 Sorrento Research 2 clicks
Bumble agreed to a $1.3 billion take-private deal, while Netflix cut about 1,000 jobs and Meta discussed its Muse superintelligence models.
Dream Finders Homes’ controlling owner borrowed against DFH stock before the homebuilder agreed to finance an acquisition with costly…
Park Aerospace’s 11% Q2’27 sell-off overlooks sole-source PAC-3 rocket-motor materials and A320neo engine composites, with missile capacity…
 BV · long
BrightView Holdings' 2.5-year turnaround has returned organic growth, with 30-50% stock upside tied to market confidence in the inflection.
Groupon is building an AI “Brain” to personalize its app for each user, turning its turnaround plan into a product initiative.
Fubo's Hulu Live merger leaves Disney with 70% ownership and resets its 2028 EBITDA target to $300 million; at $10, it trades at 4.2 times…
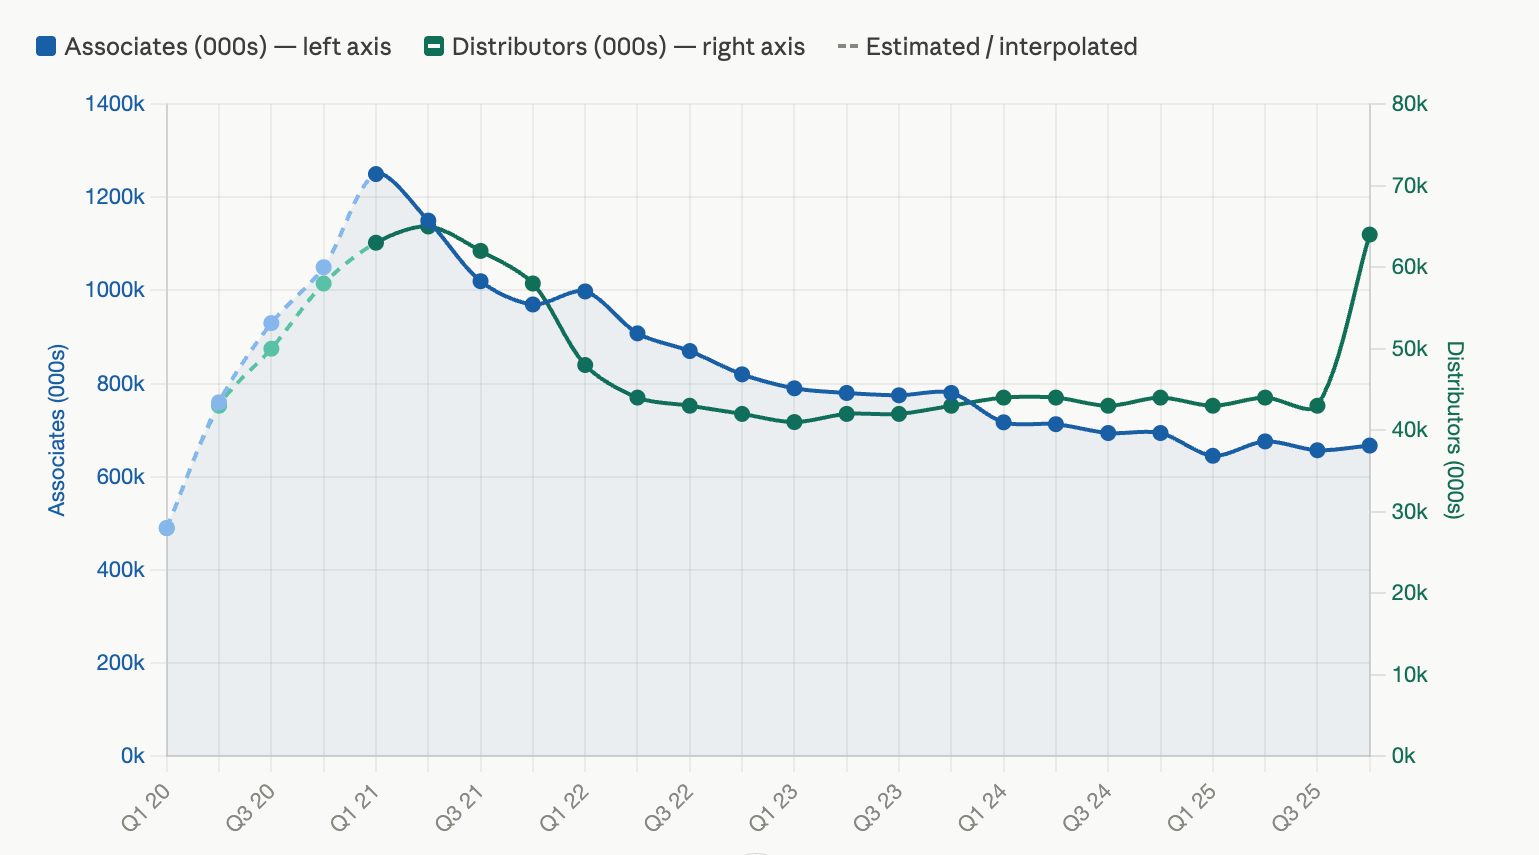
Betterware de Mexico sells locally designed home organizers through direct sellers in informal neighborhoods, generating 67% gross margins;…
Stitch Fix’s rushed Freestyle pivot cannibalized its profitable Fix business, driving active clients below 3.4 million, quarterly revenue…
DoubleU’s $11.25-per-share bid for DoubleDown Interactive values its operating business at 0.25-0.7x EBITDA; minority holders can block it…
Entravision’s lost Meta relationship reset its business model, setting up a bullish case for the company’s recovery.
Entravision’s path from a $9 Spanish-language broadcaster to a $100 adtech stock rests on an adtech-driven valuation model.
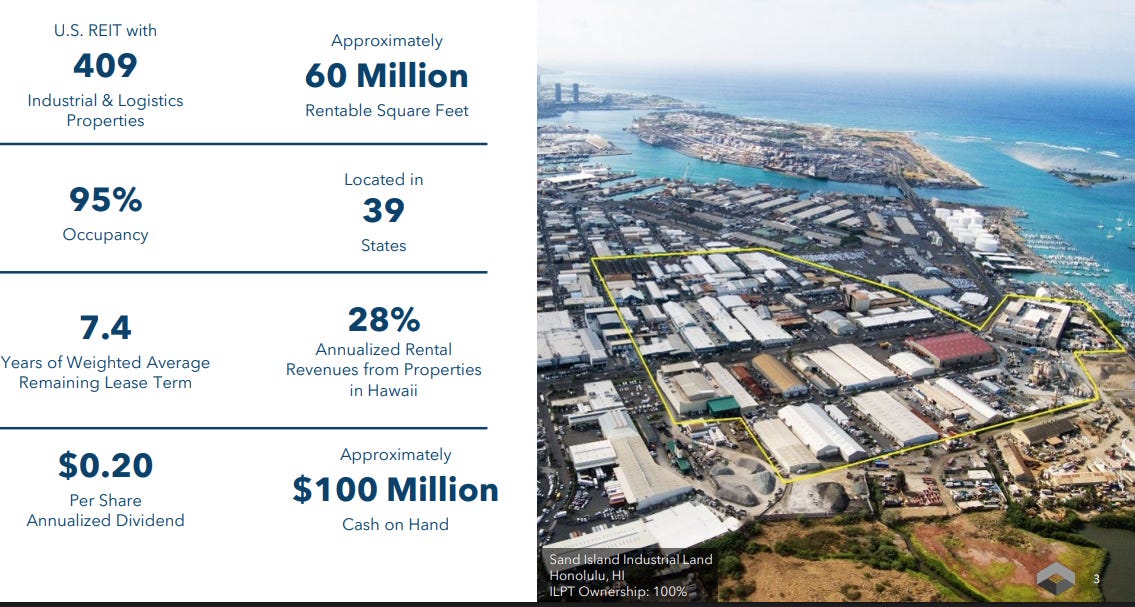
ILPT’s Hawaii ground leases and US warehouse portfolio are improving, while five-year fixed-rate refinancing eases the debt burden created…
ADF Group’s Q1 FY2026 revenue rose 78% to $99.3 million and net income 37%, aided by the LAR acquisition despite steel and aluminum tariff…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Ryan Canady
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.