Selling Cenovus: Up 78% in 10 Months
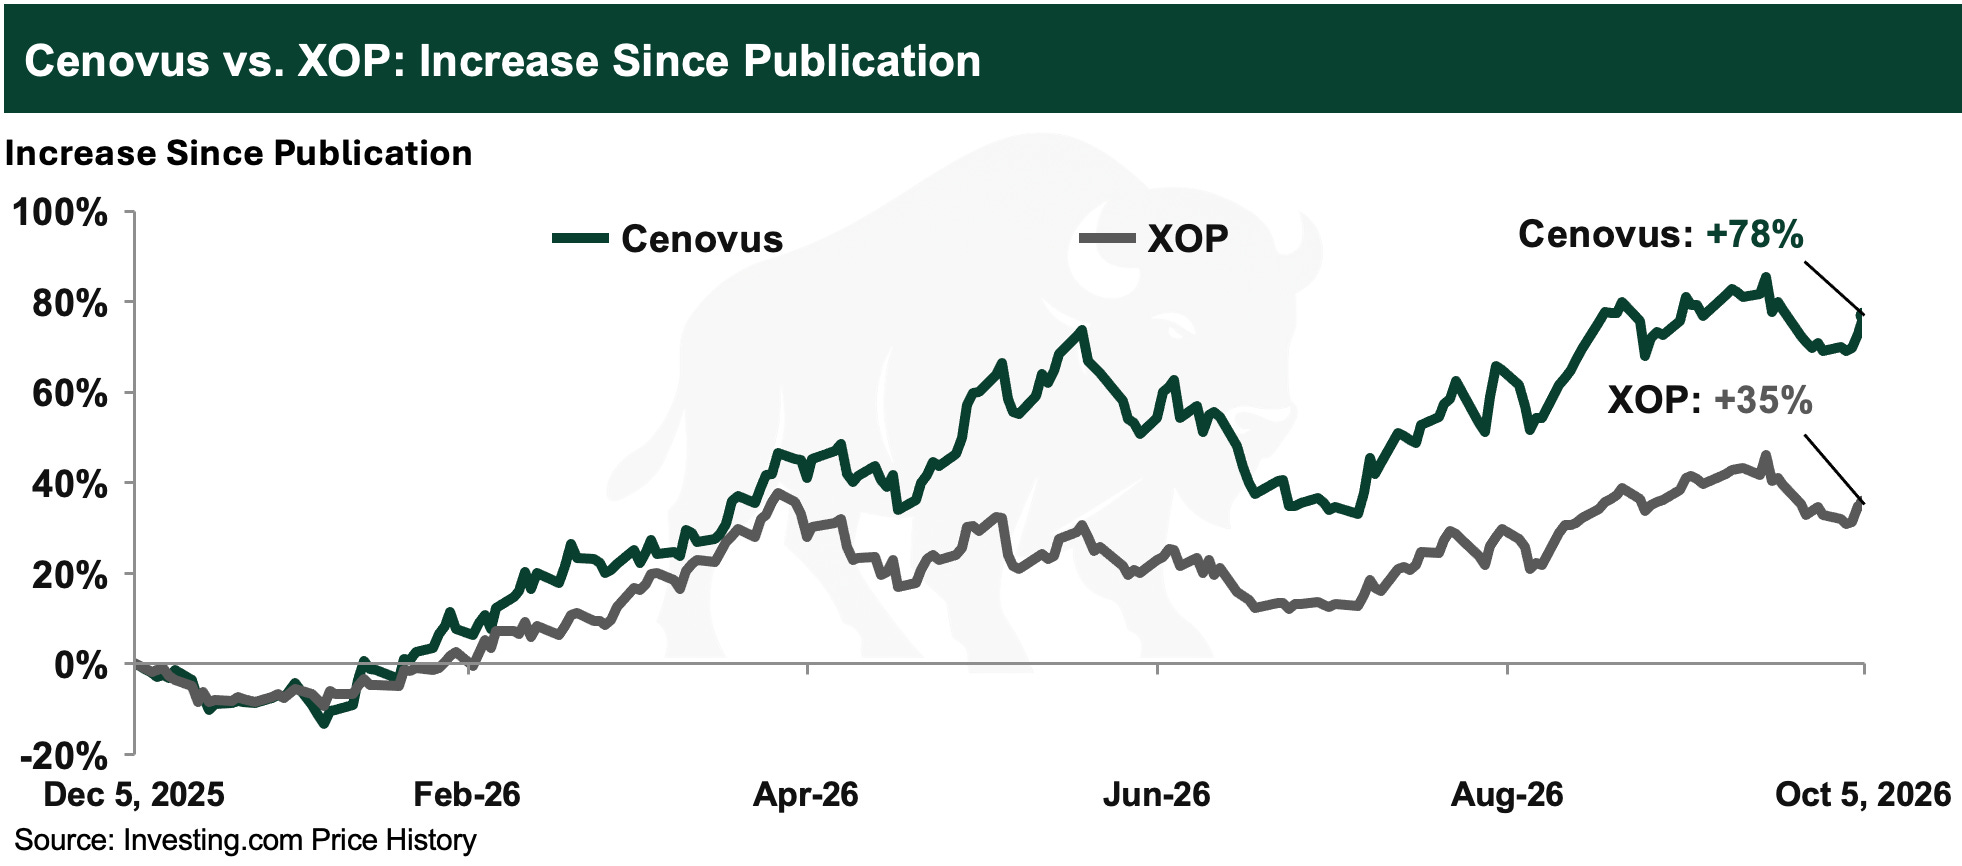
Cenovus Energy, up 78% in 10 months, is sold after agreeing to buy Athabasca Oil for $5.7 billion at a rich valuation.
Cenovus Energy, up 78% in 10 months, is sold after agreeing to buy Athabasca Oil for $5.7 billion at a rich valuation.
$MELI - Long term vision. https://t.co/EXtoxpWBg3
@TarekAntaki I bought $CHTR stock today as well, Godspeed!
@grok how has $LPLA performed since this tweet? Basically since the “Muse” scare?
I went around to $GME stores and everyone said the exact same thing. They can't keep Pokemon cards on the shelves and the One Piece stuff is selling so fast that sometimes they can't even get product in.
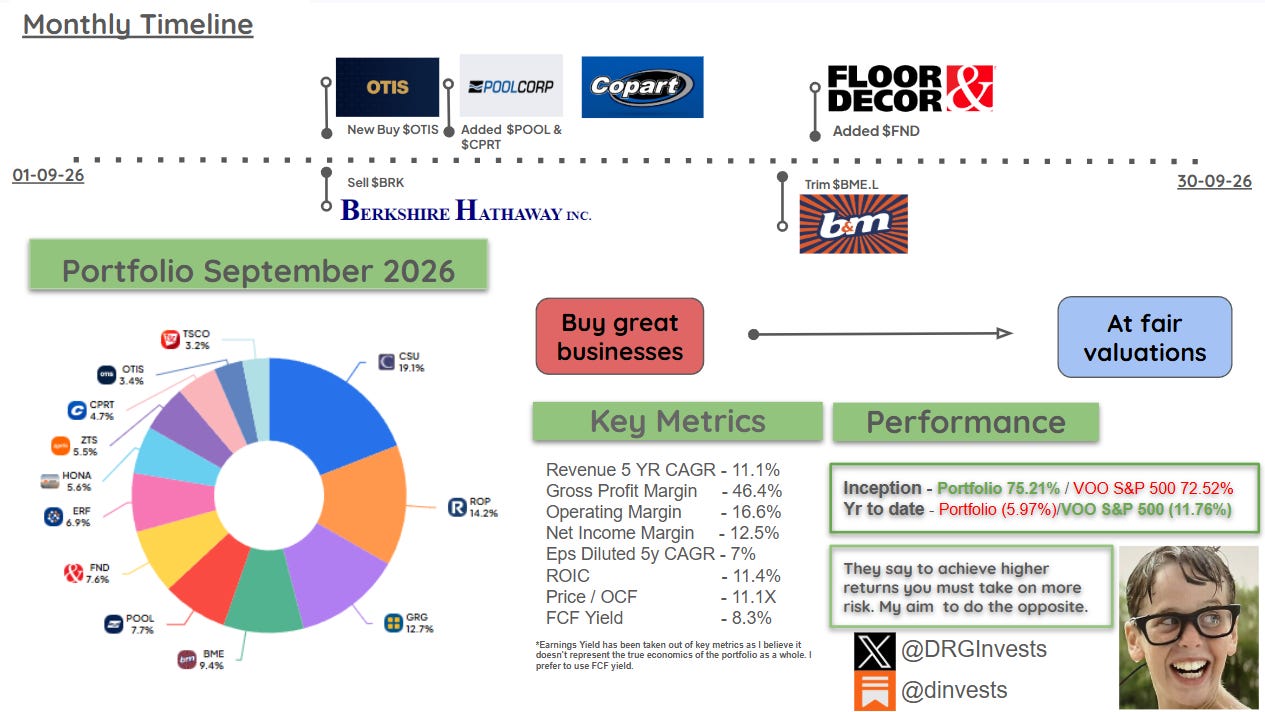
Portfolio added Otis Worldwide in the mid-$60s, increased Pool, Copart and Floor & Decor, and sold Berkshire Hathaway.
Ciena’s optical networking equipment sales to stronger telecom customers underpin a 2027 long thesis, unlike its 2000-era boom.
 Marc Gerstein 2 clicks
Brazilian fintechs NU, INTR and PICS stand to benefit from a Bolsonaro-led runoff surprise that lowers fiscal risk premiums, rates and the…
Geely’s ZEEKR nearly doubled first-half 2026 deliveries to 178,000, while Geely bought 30% of NIO’s battery-swapping unit to reduce…
 The Asian Investor 5 clicks
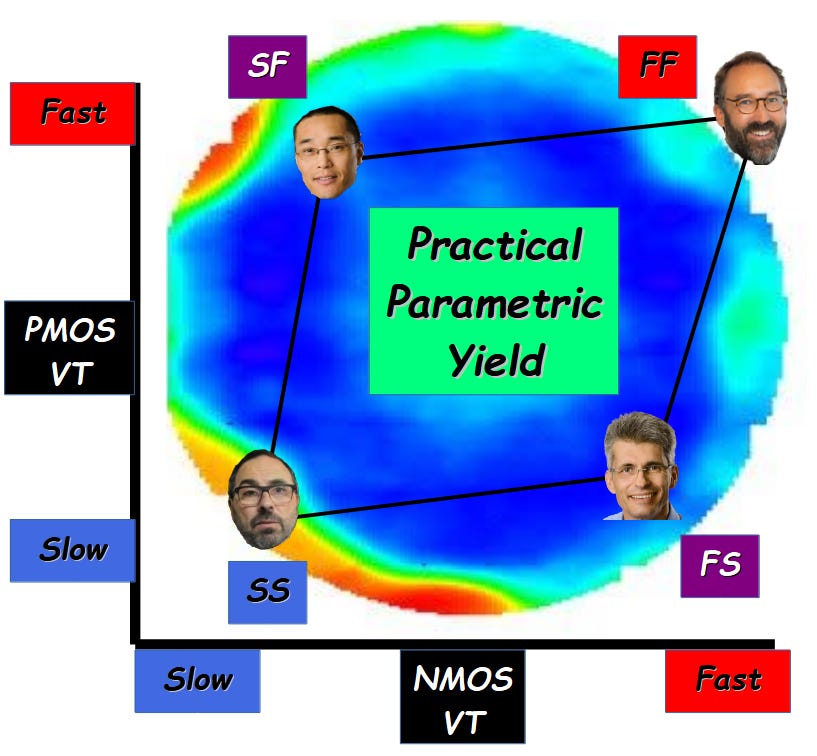
Cerebras’s WSE-3 faces parametric-yield constraints that could restrict supply, making power and clock-speed tradeoffs central to its next…
M&T Bank's 10.4% five-year revenue CAGR, improving net interest margin and commercial loan growth support its earnings resilience despite a…
 Albert Anthony 2 clicks
Lennar is selling homes to former spinoff Millrose, whose revenue largely comes from Lennar and whose largest voting shareholder is…
Nike targets EBIT margin recovery from 5.2% in FY2027 to 13% by FY2032 as revenue declines persist and wholesale, China and digital remain…
Nike’s second Latticework program examines the company and the global athletic footwear and apparel industry for professional investors.
Nike grew from a $1,000 shoe-distribution venture in 1964 into the largest sports brand, using athlete endorsements, product innovation and…
 THC · long
Tenet Healthcare generates roughly two-thirds of profits from hospitals and one-third from ambulatory surgery centers.
Credo Technology was added at $170.54 after a 40% selloff, backed by its high-speed AECs and optical connectivity for AI data centers.
Copart’s $1.9 billion ACV Auctions acquisition targets renewed growth, with EPS accretion expected by fiscal 2028 as insurance…
 Robert J. Lake 2 clicks
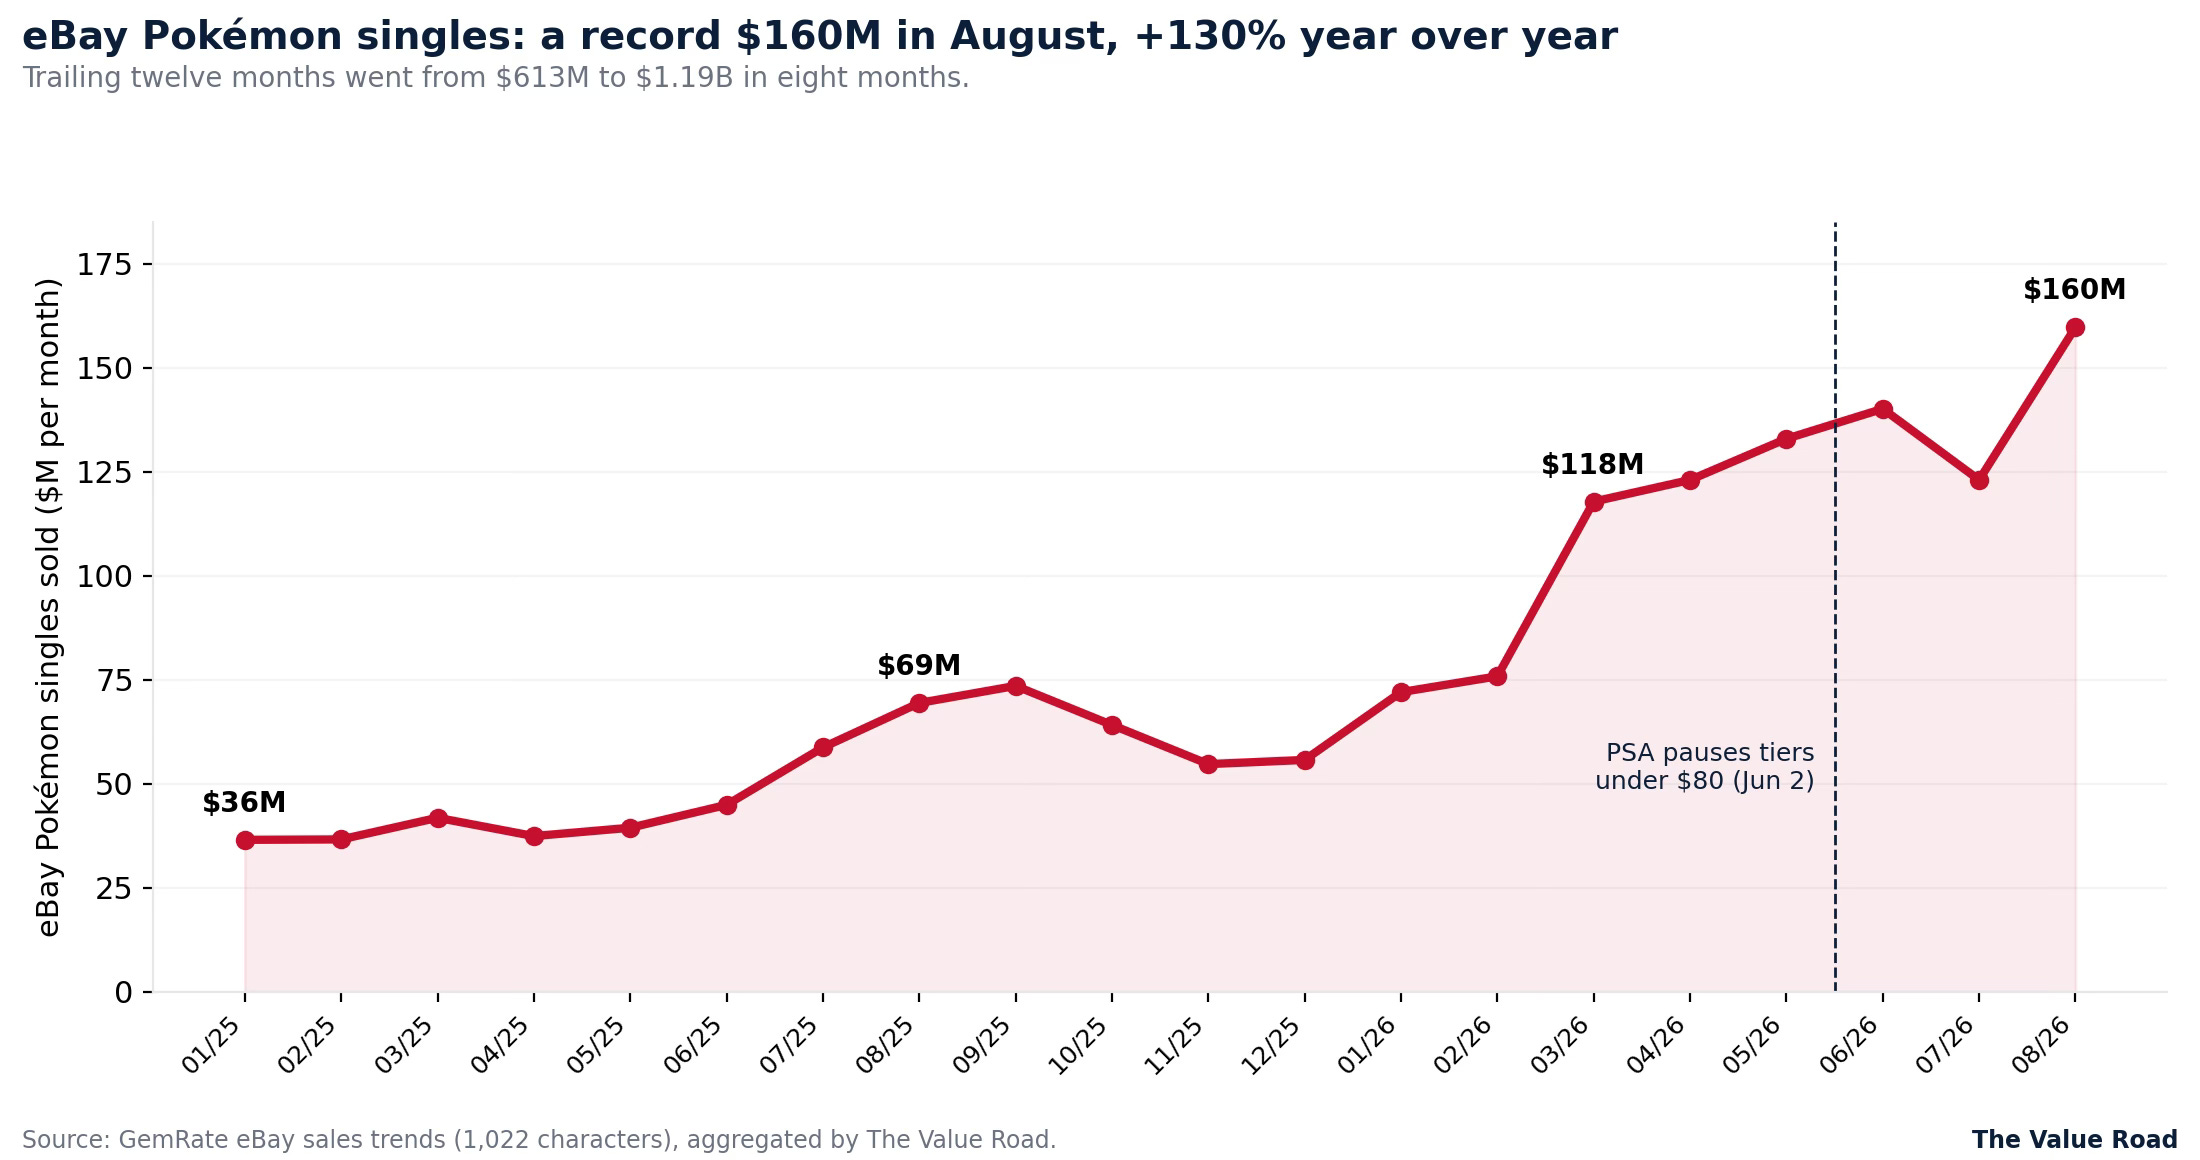
GameStop's collectibles mix rose to 45% of sales as gross margin reached 44%, supporting a deep-value case built on cash and store…
A2Gold’s first Taylor drill holes returned 20.96 g/t AuEq over 1.5m and 209.4 g/t silver over 10.7m, alongside 141.10 g/t gold at…
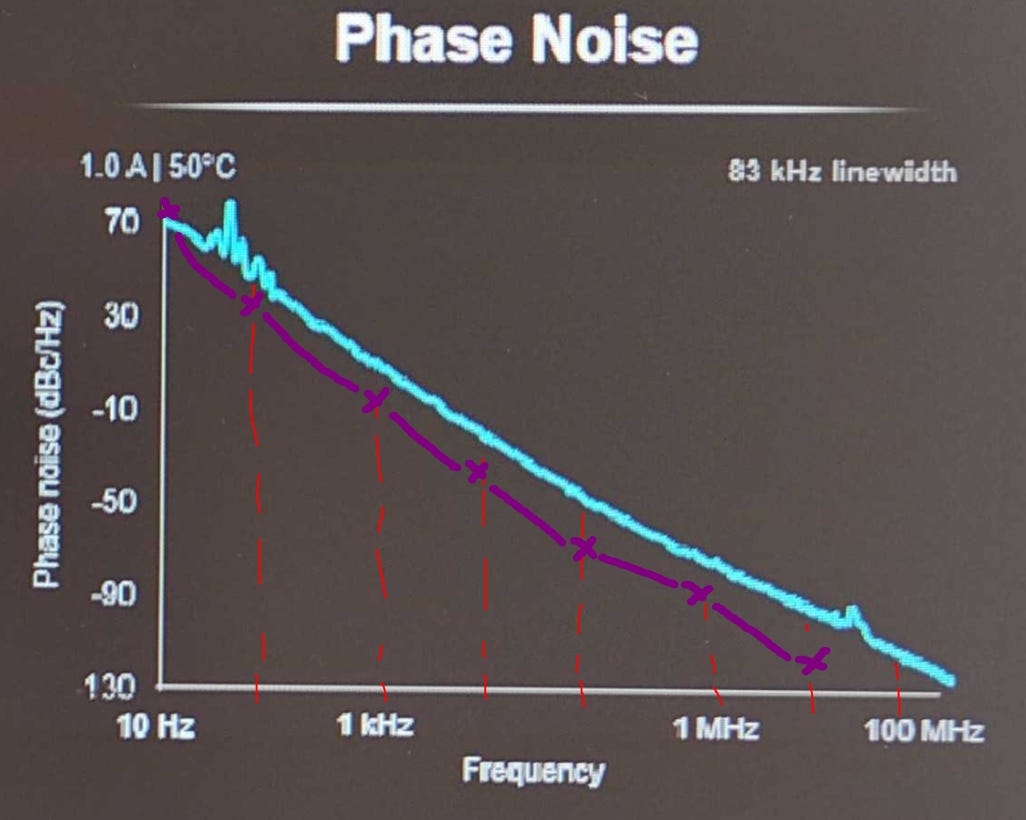
Coherent’s CPO/NPO laser misses 1 MHz effective-linewidth requirements, Irrational Analysis argues.
CoStar spent more than $1 billion building Homes.com to challenge Zillow, betting seller-agent leads, proprietary listing content and…
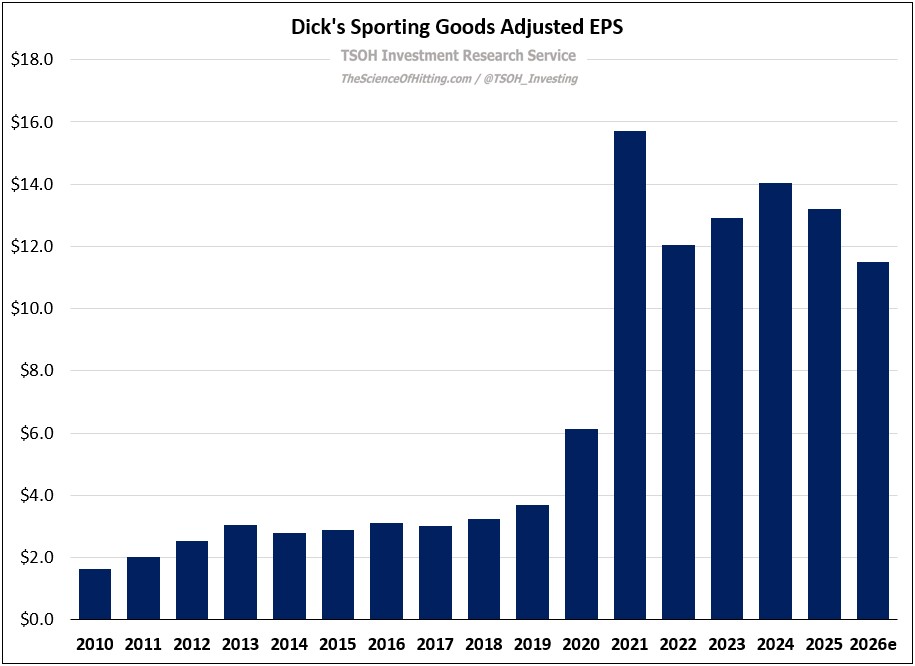
Dick’s Sporting Goods’ $2.4 billion Foot Locker acquisition nearly quadruples its store count and adds international exposure, risking a…
Latticework’s weekly briefing spotlights discounted European assets including Barco, Bolloré, Brookfield and D’Ieteren, with catalysts…
Genuine Parts targets NAPA network improvements, Motion’s industrial recovery and a 2027 Automotive-Industrial separation to lift sales,…
 Value Capital Research 2 clicks
Every publication on this site, hand-picked.
Albert Anthony Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.