Beyond Meat’s Q2 2026 revenue fell 8.2% as U.S. retail and foodservice volumes declined, while a flatter, not inverted, Treasury curve…
S PETITION 1 click
POSCO Holdings trades at a 78.6% P/B discount as lithium, gas and trading profits reshape the steelmaker, while capex and lithium prices…
SA  Capital Connoisseur 1 click
Research Roundup covers AAON's data-center cooling ramp, Knife River's margin recovery, ChronoScale's Microsoft-backed neocloud buildout…
S Monte Independent Investment Research 1 click
Asia's elevator boom favors maintenance and modernization providers, with Otis deriving nearly 90% of operating profit from after-sales…
BL Asian Century Stocks 2 clicks
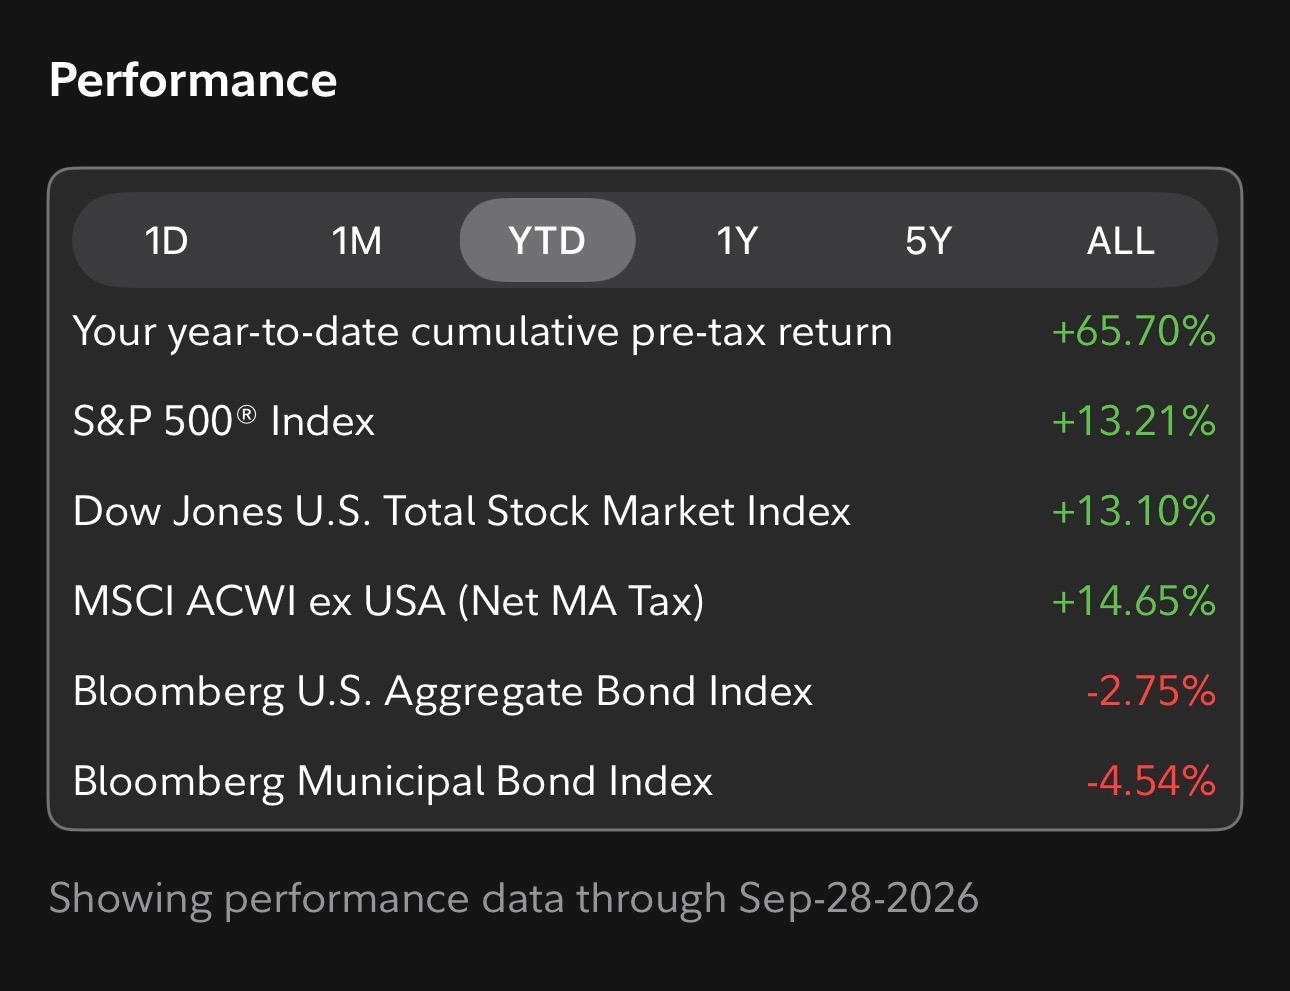
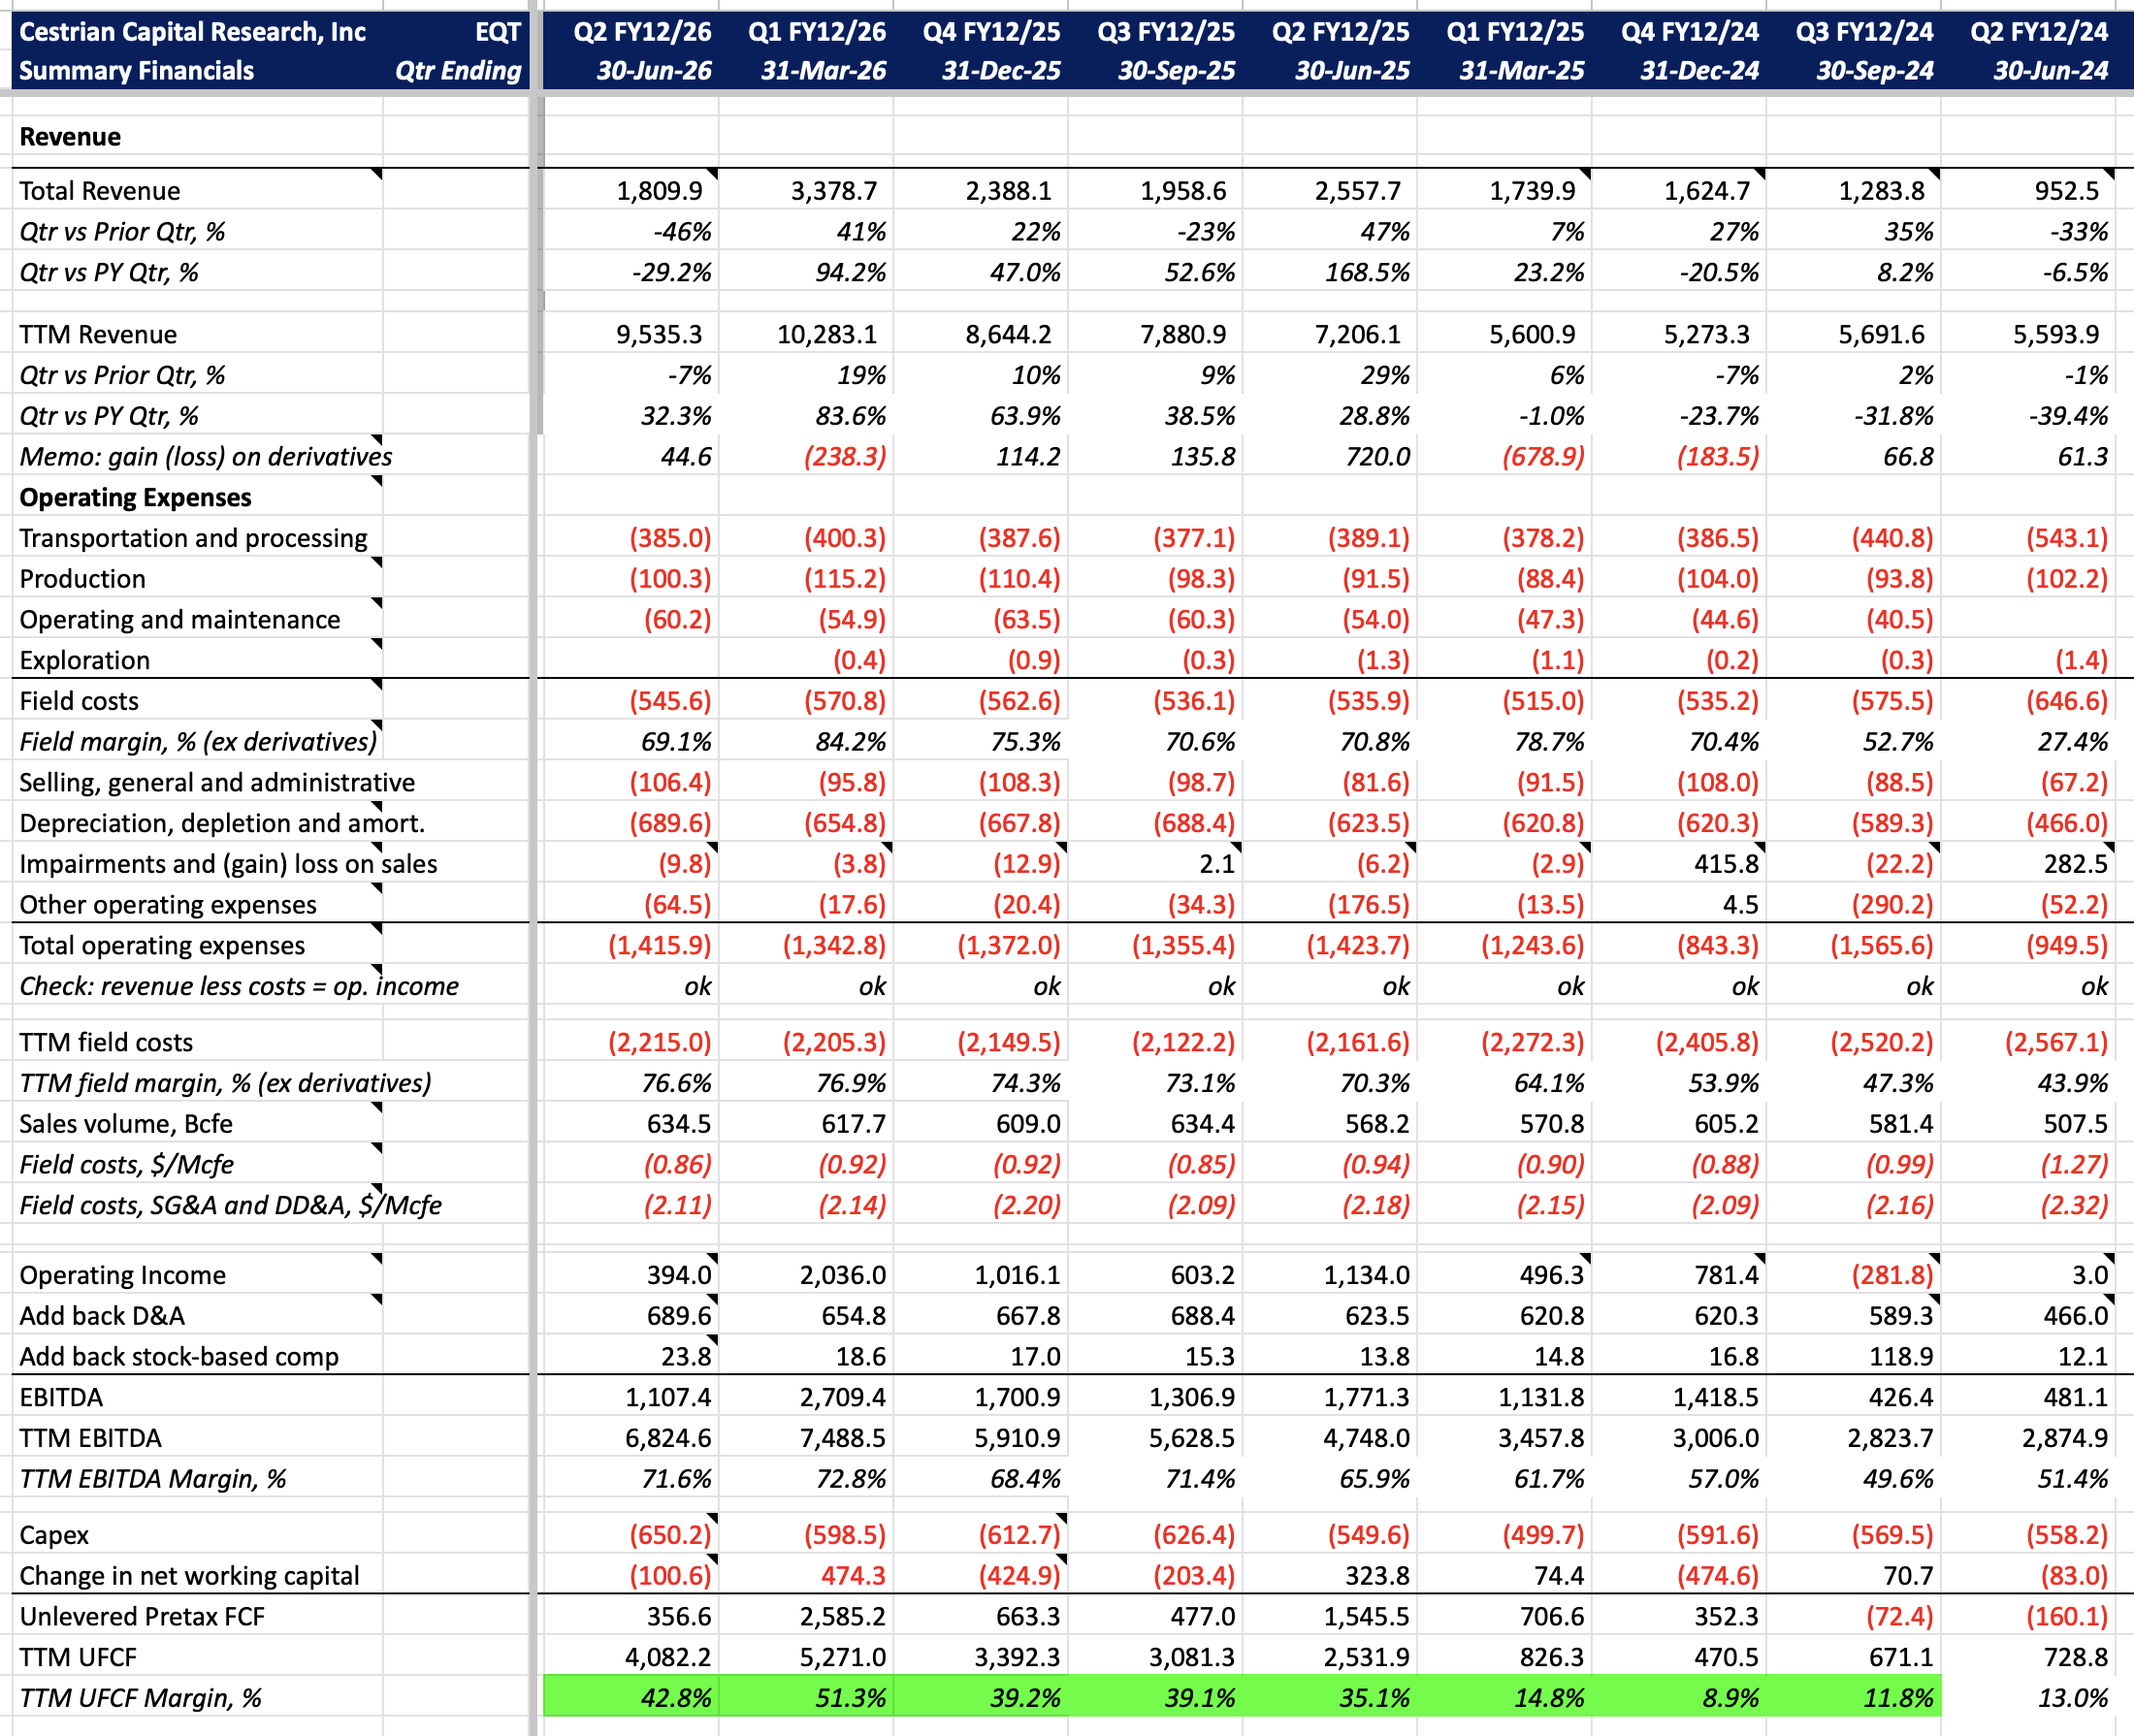
Portfolio returned 65.7% through September 28 versus the S&P 500’s 13.2%, while backing Tourmaline, EQT, Athabasca and SLB on gas demand…
S Guardian Research 6 clicks
FTAI Aviation’s engine-exchange model swaps CFM56 engines in days rather than 200-day overhauls, driving Aerospace Products adjusted EBITDA…
S Bristlemoon Capital 4 clicks
Archer Aviation's Insitu, Wisk and SkyGrid acquisitions add military and drone revenue, cutting FAA-certification dependence and leaving…
SA  The Alpha Analyst 3 clicks
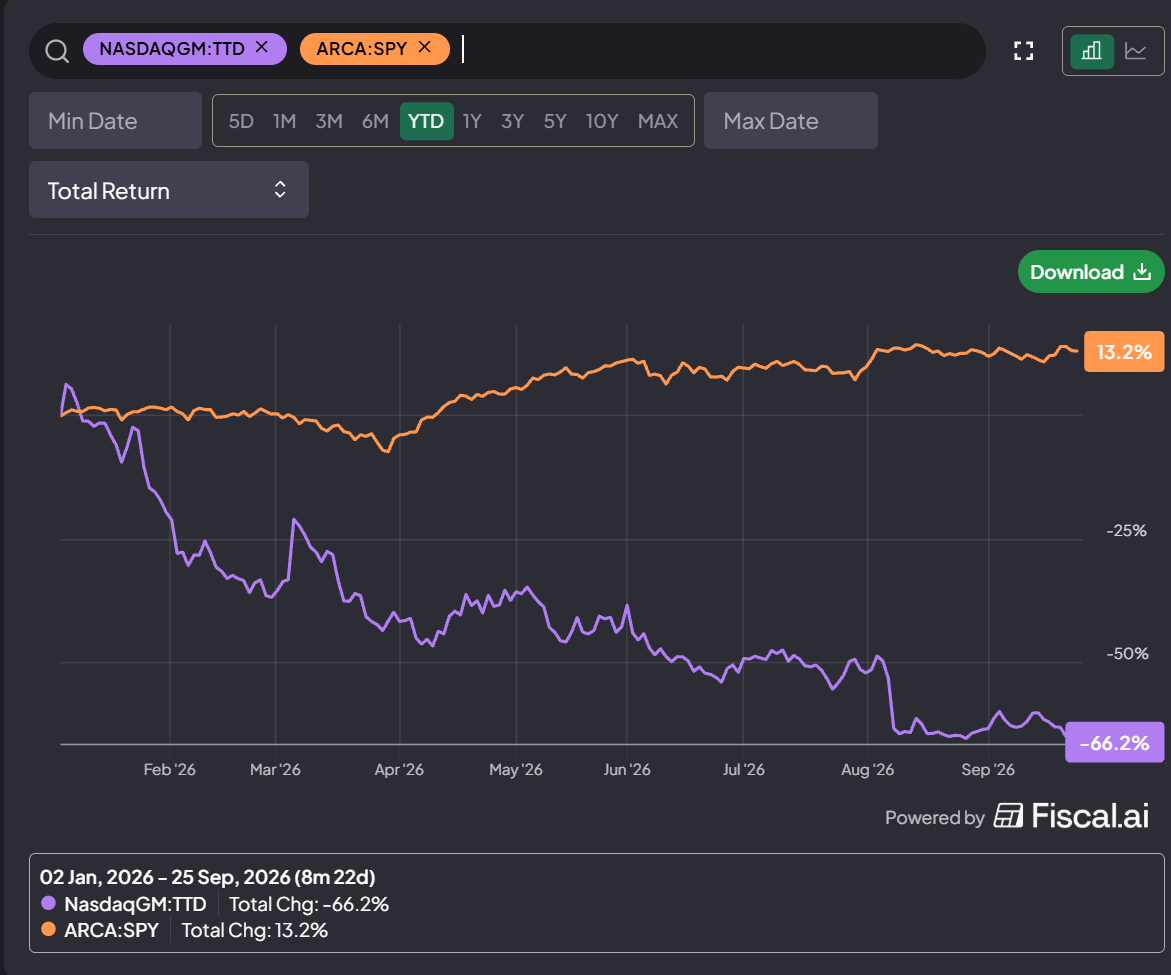
The Trade Desk’s CEO received a new 10-year option package targeting $105 per share as the company seeks shareholder approval to reprice…
S Yet Another Value Blog 7 clicks
Cullinan Therapeutics plans December 2026 autoimmune updates for CLN-978, while zipalertinib awaits an FDA decision in previously treated…
SA  Myriam Alvarez 3 clicks
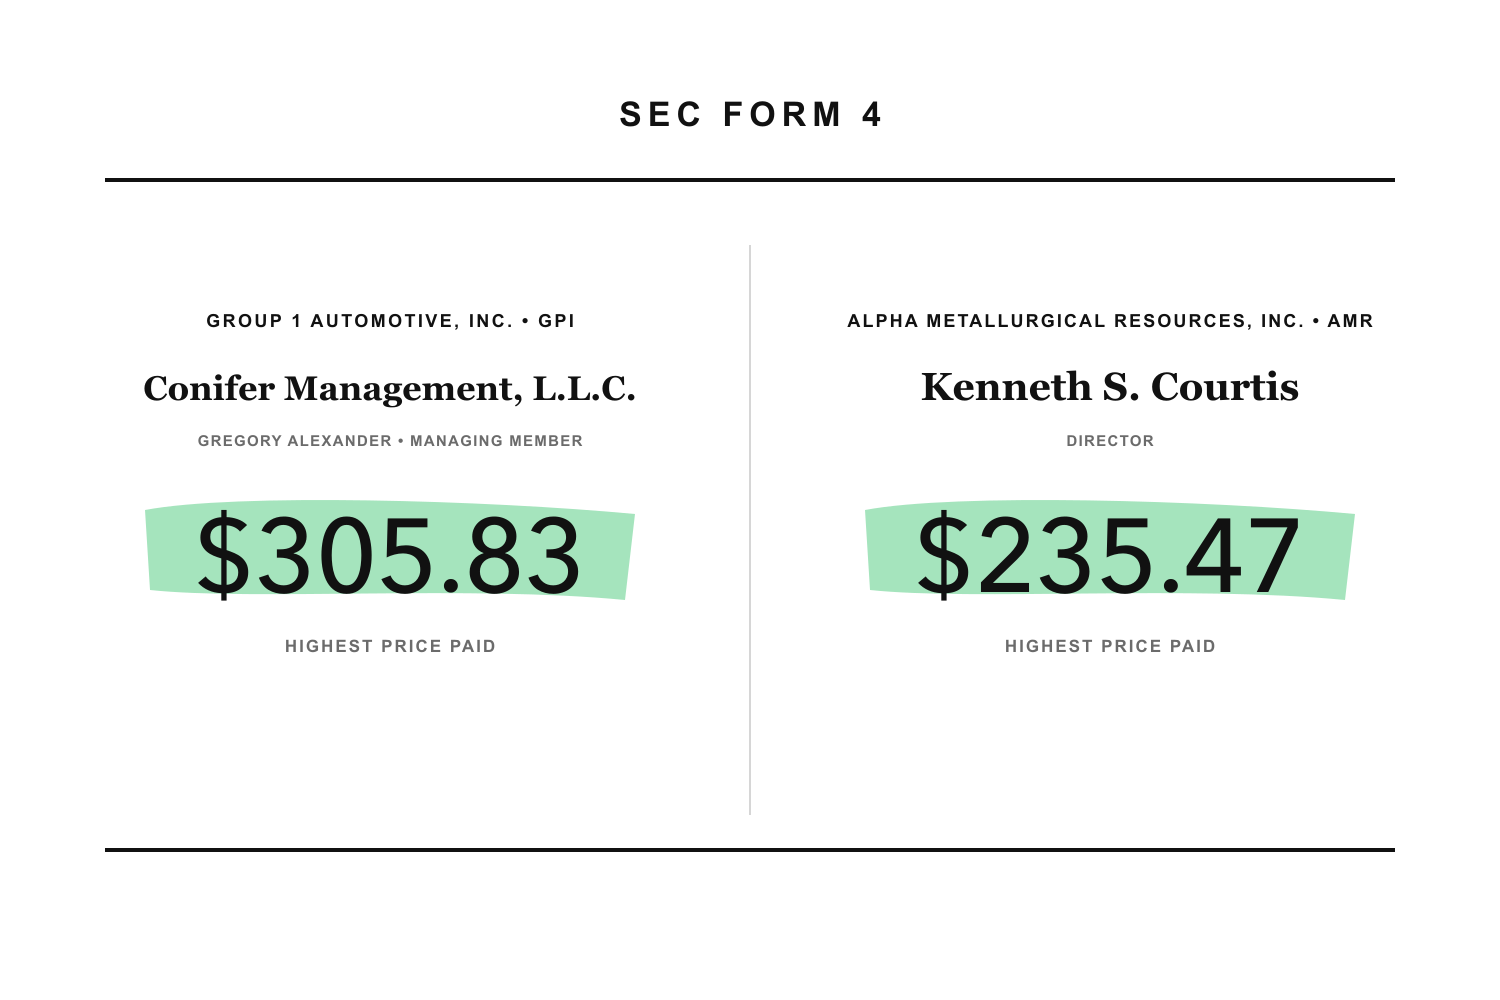
Alpha Metallurgical Resources director Ken Courtis bought $10.5 million above $190 after a blackout lifted, while Conifer’s 12.7% Group 1…
S Cannibal Stocks 5 clicks
 SEER · long
SEER Inc became a founder-offer special situation just before publication.
BL Value Investors Club 2 clicks
Kimberly-Clark's 5% dividend yield and Kenvue merger upside outweigh Tylenol litigation risk after a 30% share-price decline.
SA  Zoltan Ban 1 click
Monte Investments upgrades Karman Holdings to Buy with a $133 target after a 65% drawdown, citing 28.83x EV/aEBITDA and governance changes.
S Monte Independent Investment Research 2 clicks
Robinhood’s long-term value rests on retaining customer assets and becoming a primary financial platform beyond trading.
SA  Thomas Veth 1 click

Zscaler posted 25% Q4 revenue growth to $898.2 million and a 24.3% operating margin, but guided FY27 growth down to 16.6%-17.5% as free…
BL Cestrian Capital Research 4 clicks
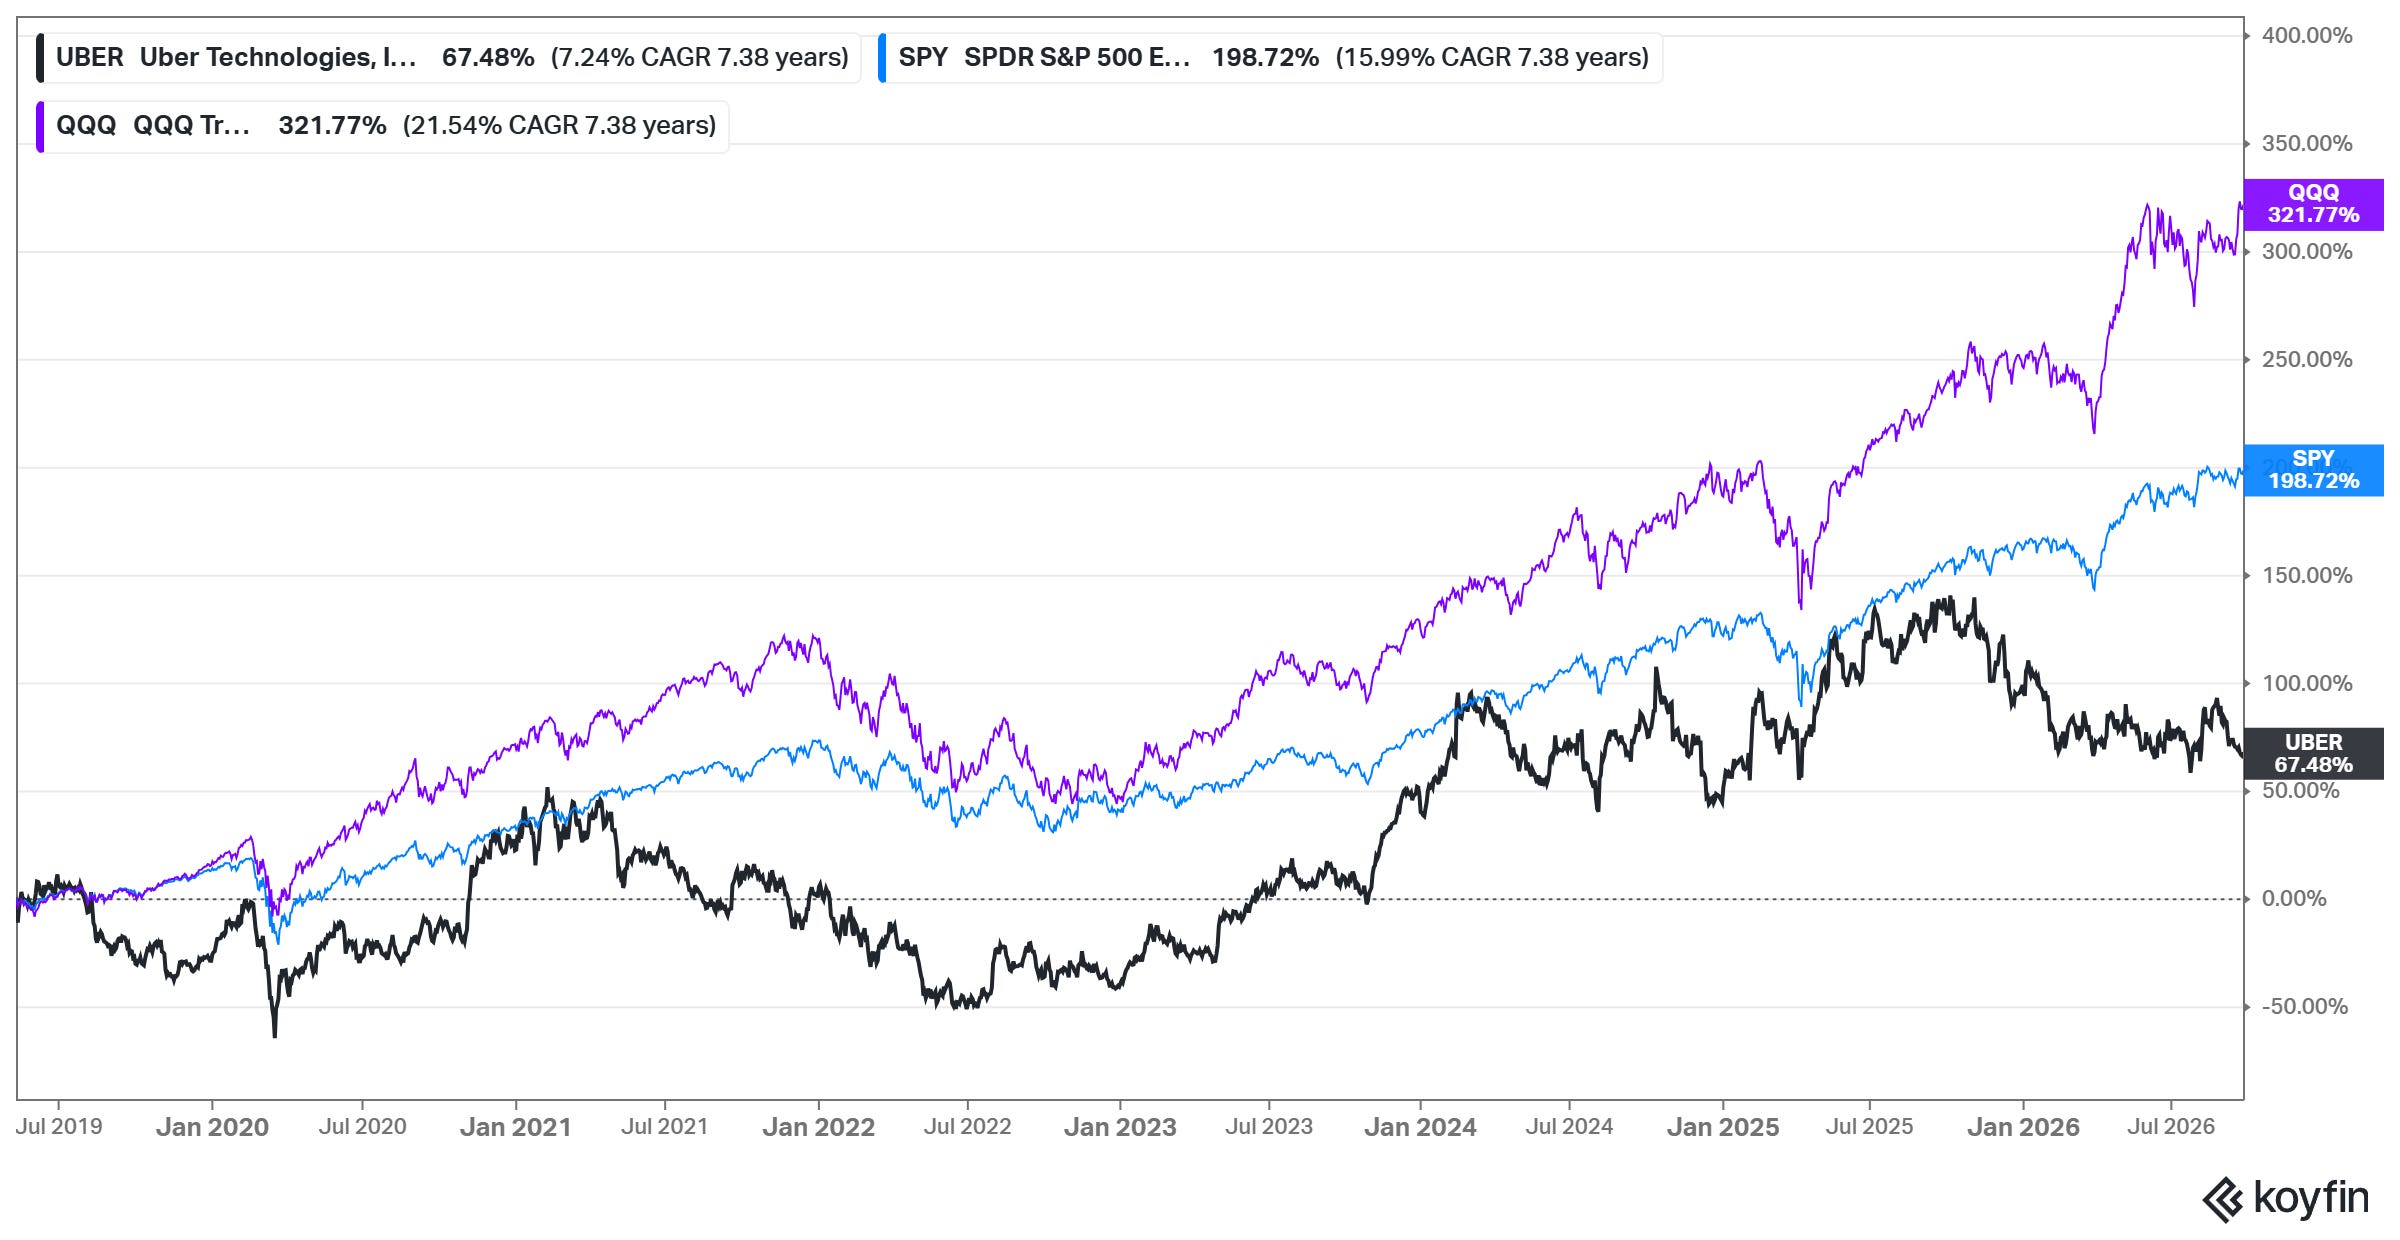
Uber's $193 billion in gross bookings and $10 billion in free cash flow contrast with modest stock gains as autonomous vehicles and…
S MBI Deep Dives 3 clicks

Veeva Systems moved VEEV to Distribute at $277 after a 41% gain in less than two months, despite Q2 revenue growth of 18% and 45% EBITDA…
BL Cestrian Capital Research 5 clicks
Gentherm’s Oct. 1 Reverse Morris Trust with Modine adds commercial and off-highway operations, leaving THRM at 7.4x pro forma EBITDA with…
S Value Don't Lie 5 clicks
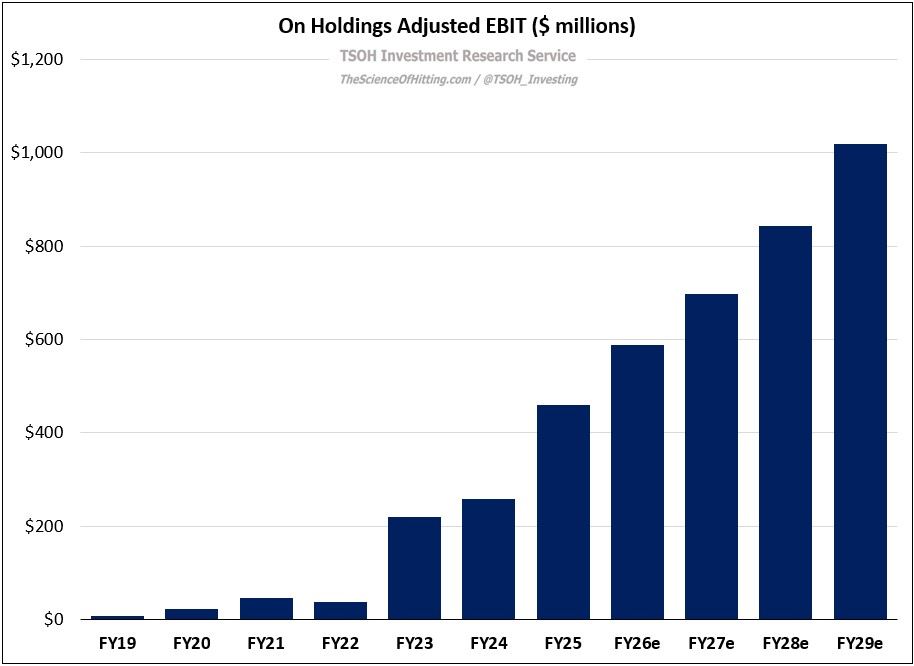
On Holdings targets premium growth through 2029, using LightSpray soccer cleats and higher pricing, with ASPs rising from $145 to $170…
S TSOH Investment Research 5 clicks
Shake Shack combines 23% restaurant-level margins, 703 locations and positive free cash flow; the bullish thesis targets $4 billion…
SA  Security Analysis 3 clicks