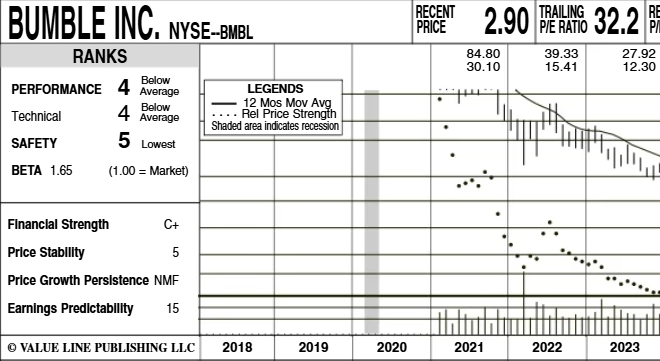
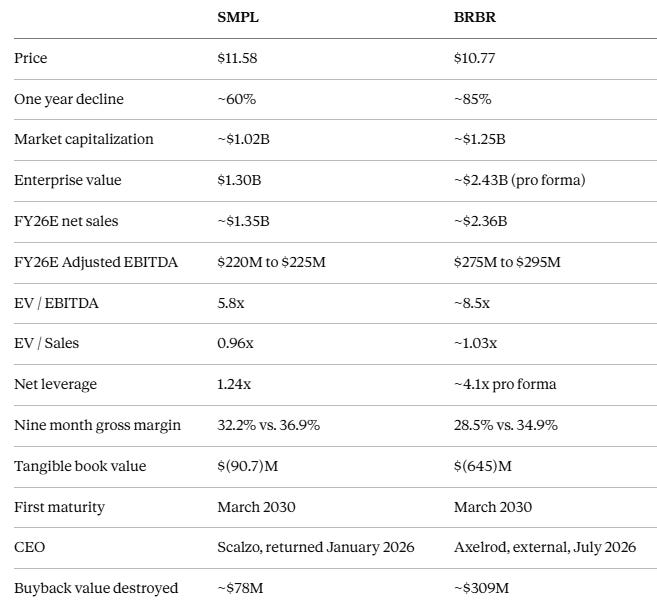
Bumble trades at roughly 2x owner’s earnings and 4.76x enterprise value, with Whitney Wolfe Herd’s return central to a rerating case.
S Calvin Blissett Sep 20 4 clicks
Special-situations survey flags Cooper’s $3 billion buyback, Grab’s $900 million repurchase, and Beretta’s $44.80 partial tender for Sturm…
S Latticework by MOI Global Sep 18 1 click
Pioneer Bancorp’s acquisitions lifted loans 13.6% and Q2 net interest margin to 4.30%, but expenses, weaker profitability ratios and a…
SA Crimson And Gold Research Sep 17 4 clicks Groupon CEO Dušan Šenkypl and CFO Rana Kashyap discuss rebuilding the local-experiences marketplace with AI infrastructure, better…
S Mispriced Assets Sep 11 5 clicks
Independence Realty Trust is buying Centerspace in stock to create an $8.1 billion apartment REIT, targeting 5% 2027 Core FFO per-share…
SA Dane Bowler Sep 11 Sofwave Medical grew Q2 revenue 43% as recurring usage fees reached 46% of sales for its non-invasive ultrasound skin-tightening devices.
S Substack von Philipp Sep 11 1 click
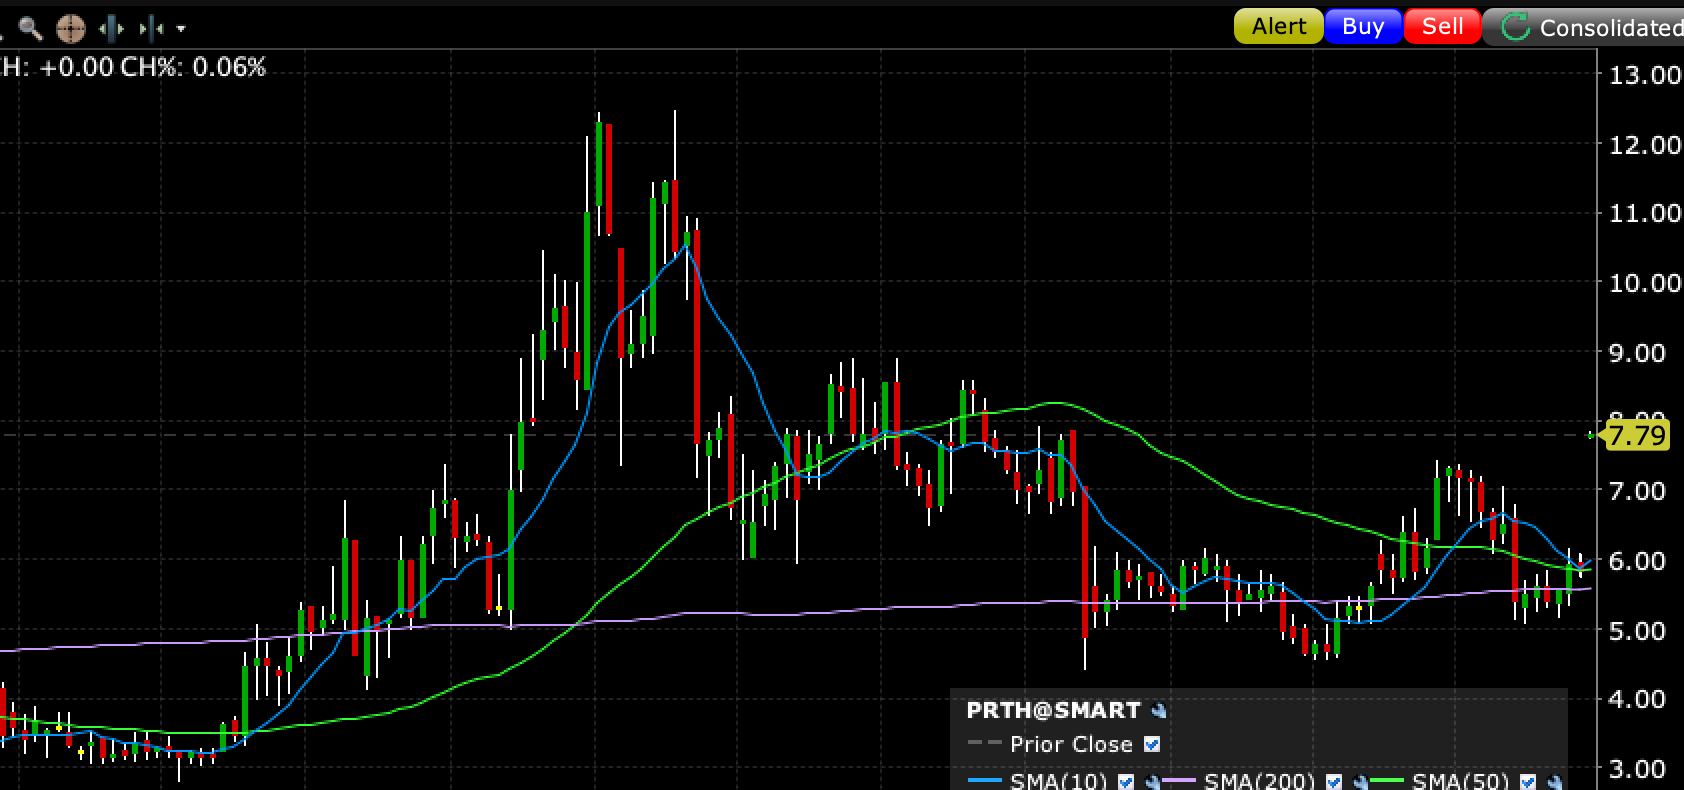
Priority Technology’s chairman offered $6.00 to $6.15 a share to take PRTH private, while Zack Buckley argues Treasury Solutions and…
YT Yet Another Value Podcast Sep 10 3 clicks
GeoPark’s Bare Block acquisition targets $1.2 billion of 2030 EBITDA, but 42.1 million to 47.6 million new shares and Gilinski control…
S HFI Research Sep 10 2 clicks
ContextLogic will acquire specialty-solvent maker gChem for $850 million, funded by a $650 million rights offering and $250 million of…
S Hidden Gems Investing Sep 8 5 clicks
Kodiak AI’s stock collapse coincides with a planned year-end long-haul driverless launch, while cash burn, customer concentration and…
SA High Alpha Professor Sep 8 1 click SFIX · long Stitch Fix’s 2017 IPO rested on overly ambitious long-term growth expectations and an unrealistic definition of its addressable market.
BL Value Investors Club Jun 30 1 click
Annexon targets functional recovery in geographic atrophy and Guillain-Barré syndrome, with ARCHER II vision-endpoint data due in Q4 2026…
SA Equity Eagle Sep 27 2 clicks Build-A-Bear Workshop, the toy retailer.
Two U.S. protein-snacking companies lost $6 billion in market value as impairments, inventory growth and margin pressure test whether the…
S The Value Road Sep 2 12 clicks
Tectonic Therapeutic's TX45 CpcPH-HFpEF program gains support from Merck's CADENCE data; Phase 1b hemodynamics and cash through Q1 2029 set…
SA Equity Eagle Sep 2 2 clicks EVC reported a solid second quarter and outlook.
S Nat Stewart - Stock Picking Newsletter Sep 1 15 clicks
Limbach's EBITDA fell 30% as organic revenue declined, but 1 Main Capital calls the weakness temporary and views CYMCOR as its first…
YT Yet Another Value Podcast Sep 1 9 clicks
Shattuck Labs pivots to DR3-targeted IBD therapy SL-325, funded through a Phase 2b readout as it competes with anti-TL1A drugs.
SA Equity Eagle Sep 1 EverQuote, an $864 million digital insurance marketplace, and PAR Technology, an $808 million restaurant software provider, lead a…
S Inglenook Growth Aug 30
Michael Burry on Build-A-Bear Workshop, Part 1.
S Cassandra Unchained Aug 29 2 clicks