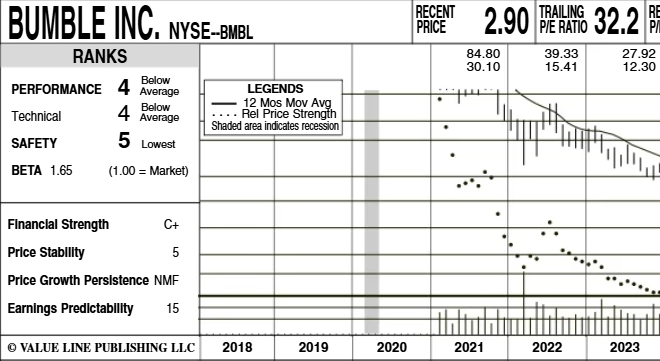
Bumble trades at roughly 2x owner’s earnings and 4.76x enterprise value, with Whitney Wolfe Herd’s return central to a rerating case.
S Calvin Blissett Sep 20 4 clicks
Special-situations survey flags Cooper’s $3 billion buyback, Grab’s $900 million repurchase, and Beretta’s $44.80 partial tender for Sturm…
S Latticework by MOI Global Sep 18 1 click
Pioneer Bancorp’s acquisitions lifted loans 13.6% and Q2 net interest margin to 4.30%, but expenses, weaker profitability ratios and a…
SA Crimson And Gold Research Sep 17 4 clicks Groupon CEO Dušan Šenkypl and CFO Rana Kashyap discuss rebuilding the local-experiences marketplace with AI infrastructure, better…
S Mispriced Assets Sep 11 5 clicks
Independence Realty Trust is buying Centerspace in stock to create an $8.1 billion apartment REIT, targeting 5% 2027 Core FFO per-share…
SA Dane Bowler Sep 11 Sofwave Medical grew Q2 revenue 43% as recurring usage fees reached 46% of sales for its non-invasive ultrasound skin-tightening devices.
S Substack von Philipp Sep 11 1 click
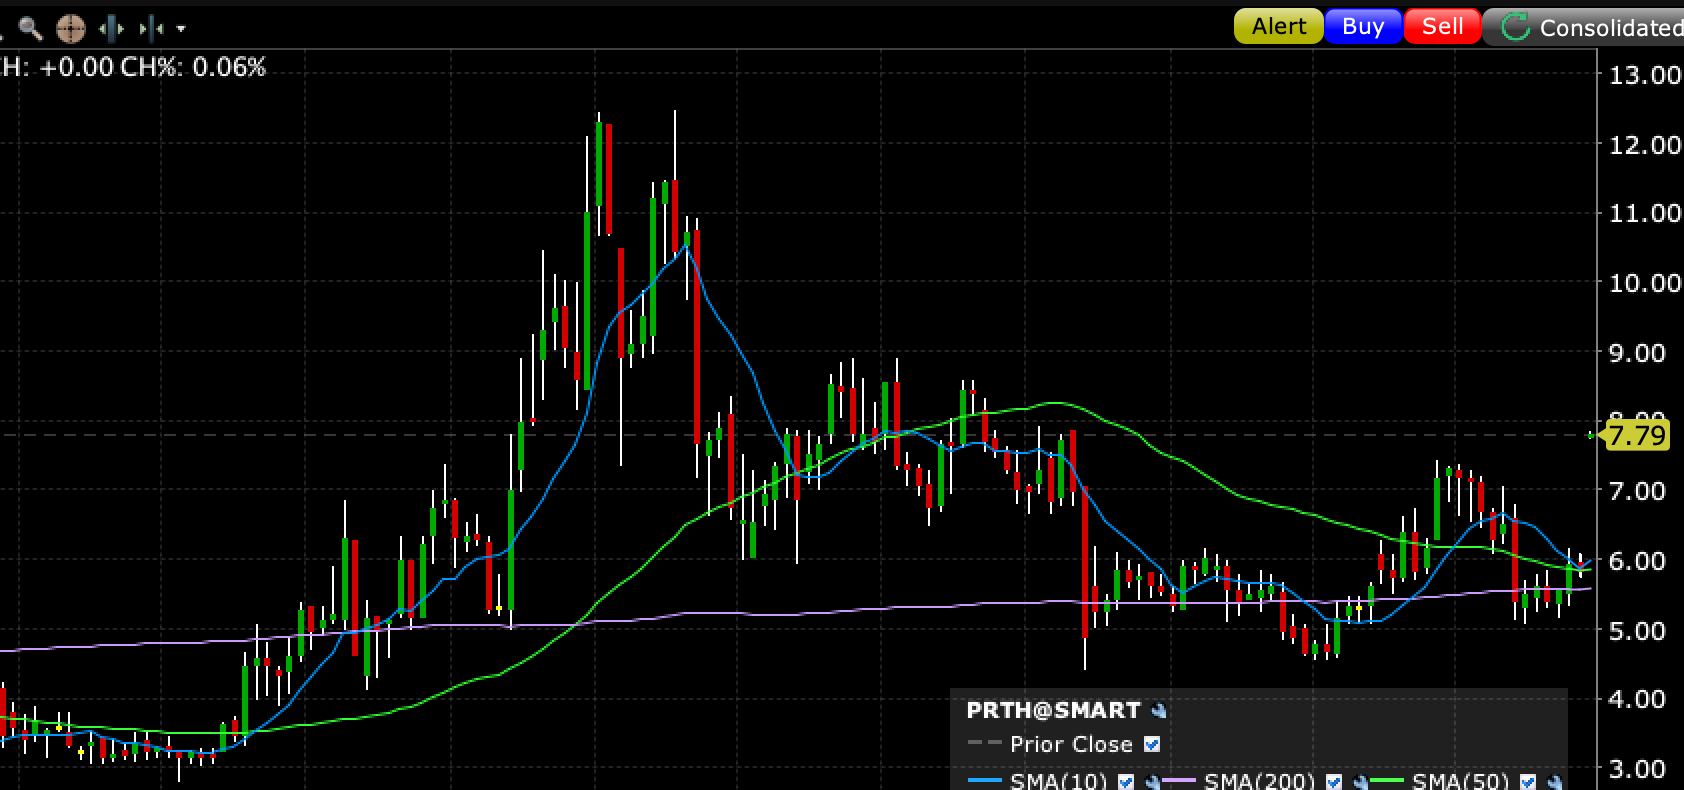
Priority Technology’s chairman offered $6.00 to $6.15 a share to take PRTH private, while Zack Buckley argues Treasury Solutions and…
YT Yet Another Value Podcast Sep 10 3 clicks
GeoPark’s Bare Block acquisition targets $1.2 billion of 2030 EBITDA, but 42.1 million to 47.6 million new shares and Gilinski control…
S HFI Research Sep 10 2 clicks
ContextLogic will acquire specialty-solvent maker gChem for $850 million, funded by a $650 million rights offering and $250 million of…
S Hidden Gems Investing Sep 8 5 clicks
Kodiak AI’s stock collapse coincides with a planned year-end long-haul driverless launch, while cash burn, customer concentration and…
SA High Alpha Professor Sep 8 1 click TPLKF · long PVA TePla (XTRA:TPE) is presented as a long position.
BL Value Investors Club Jun 22 3 clicks
A debt-free American manufacturer now trades at roughly 7x annualized Q2 EBITDA, with $7.35 per share in net cash and a tender floor 18.5%…
S The Value Road Jul 30 4 clicks
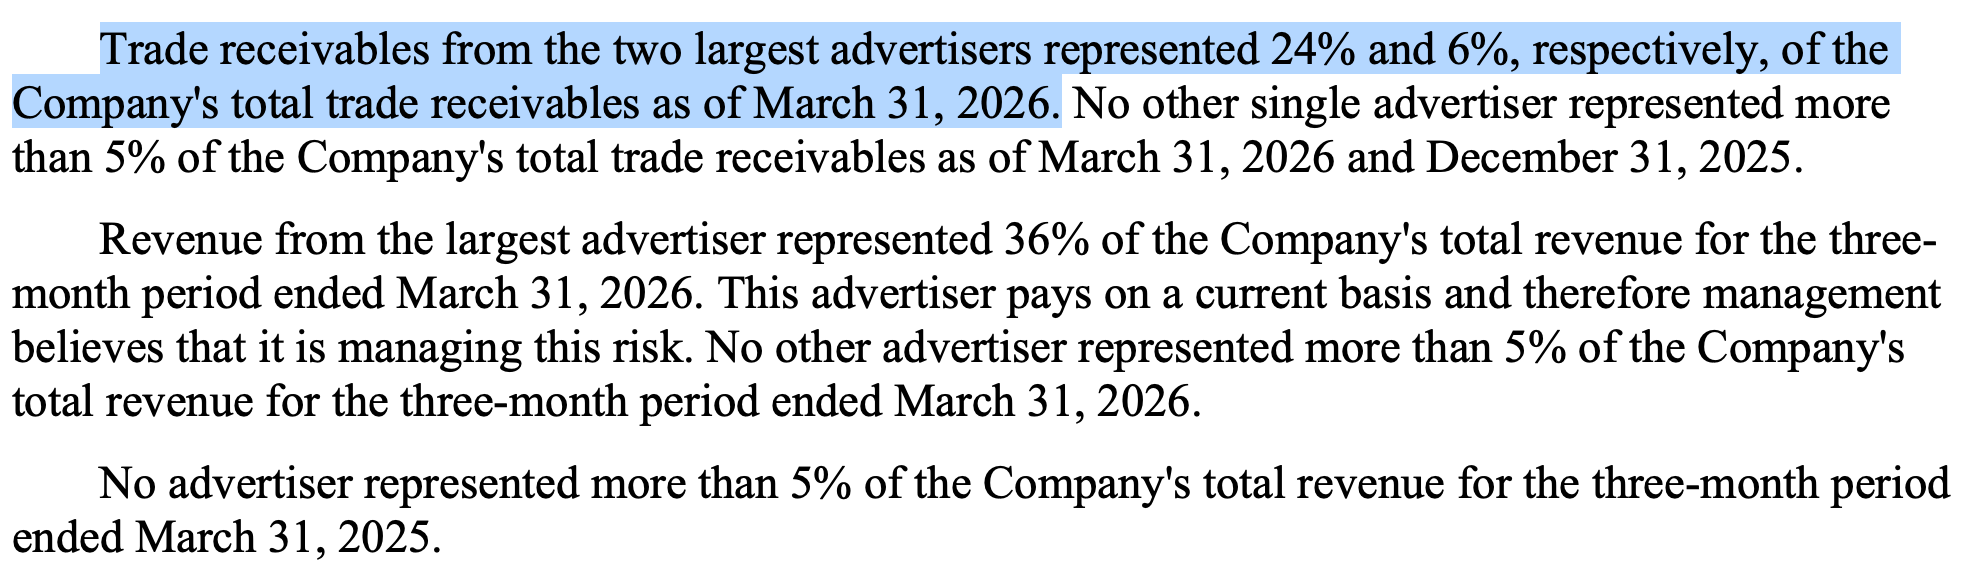
Entravision’s Q1 filings contain a new footnote disclosure pointing to a potential second large advertiser beyond its Hong Kong customer,…
S The Value Road Jul 28 11 clicks
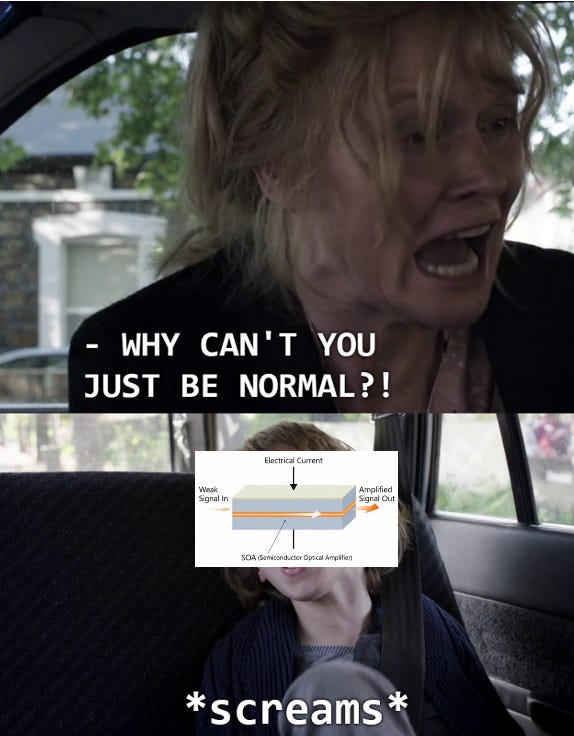
Aeva’s high-power InP SOA design could supply NPO/CPO optical modules at roughly 17% gross margins, versus 51% for eight discrete DFB…
S Irrational Analysis Jul 25
Semiconductor optical amplifiers offer compact, low-cost gain for LiDAR, long-haul links and ultra-high-power co-packaged optics, trading…
S Irrational Analysis Jul 18
Diversified Energy (DEC) has paid $21.84 per share in dividends since June 2017 and trades at $13.35 amid a bullish U.S.
S The Oak Bloke Jul 18 3 clicks
Groupon is building an AI “Brain” to personalize its app for each user, turning its turnaround plan into a product initiative.
S Mispriced Assets Jul 16
Fubo's Hulu Live merger leaves Disney with 70% ownership and resets its 2028 EBITDA target to $300 million; at $10, it trades at 4.2 times…
Betterware de Mexico sells locally designed home organizers through direct sellers in informal neighborhoods, generating 67% gross margins;…
S Phynvesting Jul 13 1 click
Stitch Fix’s rushed Freestyle pivot cannibalized its profitable Fix business, driving active clients below 3.4 million, quarterly revenue…
S MBI Deep Dives Jul 11 2 clicks