The Enron-Era Tricks Are Back in AI: How These Companies Are Hiding Their Debt | The Weekly Wrap
Steve Eisman says AI companies are reviving Enron-era off-balance-sheet and circular financing, alongside concerns around Oracle and Blue Owl.
Steve Eisman says AI companies are reviving Enron-era off-balance-sheet and circular financing, alongside concerns around Oracle and Blue Owl.
@SW_Resurgo I dunno, I see lots of very real cases of people doing shit like this. Remember the guy who went all in on $PDD and then had a royal crash out?
Caught a nice move in $META as they have executed nicely on Muse. However, I’m curious to see Muse’s retention stats. Muse’s agentic capabilities still seem like a bit of a novelty to me, and sometimes more of a hassle to use than a value-add. $META has also aggressively re-targeted me with ads on my feed based on my Muse activity. While impressive from a business monetization point of view, it makes me leery to connect my email and other sensitive accounts.
@WaterworldCapi1 @madthunderdome $TLN - Josh Shapiro will privatize it.
Blackjack 21 Index (favorite collection of global banks and insurers) jumps to +38%, 36% ahead of $XLF Notable ATH's: Juroku Financial, Mebuki Financial https://t.co/HIBUQ57PBF
And so will $AAPL $AMZN $GOOG, they will all attempt to protect their walled gardens. Nothing new or surprising there. https://t.co/ZzqZmFtBwO
New low on $NKE -2% off BofA downgrade "Nike’s innovation continues to be overshadowed by pressure on its classics business." https://t.co/ClkHft164S
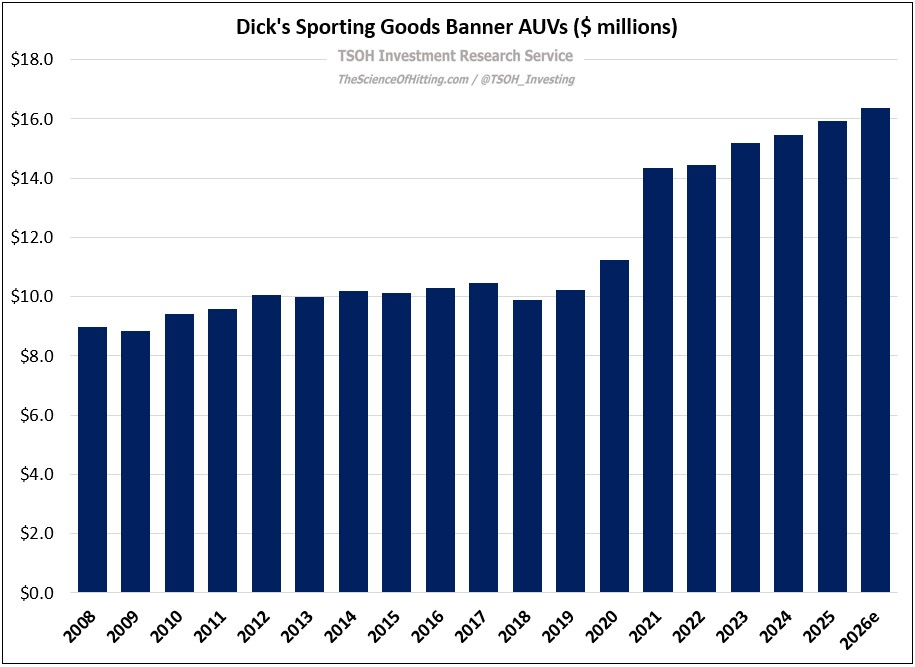
TSOH Weekly Roundup covers Ralph Lauren’s $1 billion distribution pullback, Peloton’s $2,195 foldable treadmill and $800 million…
IonQ's Q2 2026 revenue rose 287% to $80.1 million, but durability hinges on its $485 million RPO and enterprise adoption for production AI…
 Deep Value Investing 2 clicks
Rocket Companies combines Redfin, Rocket Mortgage and Mr. Cooper into an end-to-end homeownership platform, adding mortgage servicing fees…
Eckert & Ziegler trades near €12, about 14 times expected earnings, as its isotope supply business expands with radiopharma demand despite…
Berkshire Hathaway's succession elevates Greg Abel to CEO and Howard Buffett to chairman, reinforcing its acquisition, buyback and…
 Jim Sloan 6 clicks
Ciena and Fabrinet benefit as AI clusters require high-speed optics within and between data centers, through networking systems and…
Oracle’s Q1 FY2027 AI infrastructure push relies on leasing, debt, customer prepayments and OpenAI’s Stargate project, resembling a…
Honeywell is refocusing on automation after its Aerospace and Advanced Materials spinoffs, with a 1.1x book-to-bill ratio, raised guidance…
 Gen Alpha 1 click
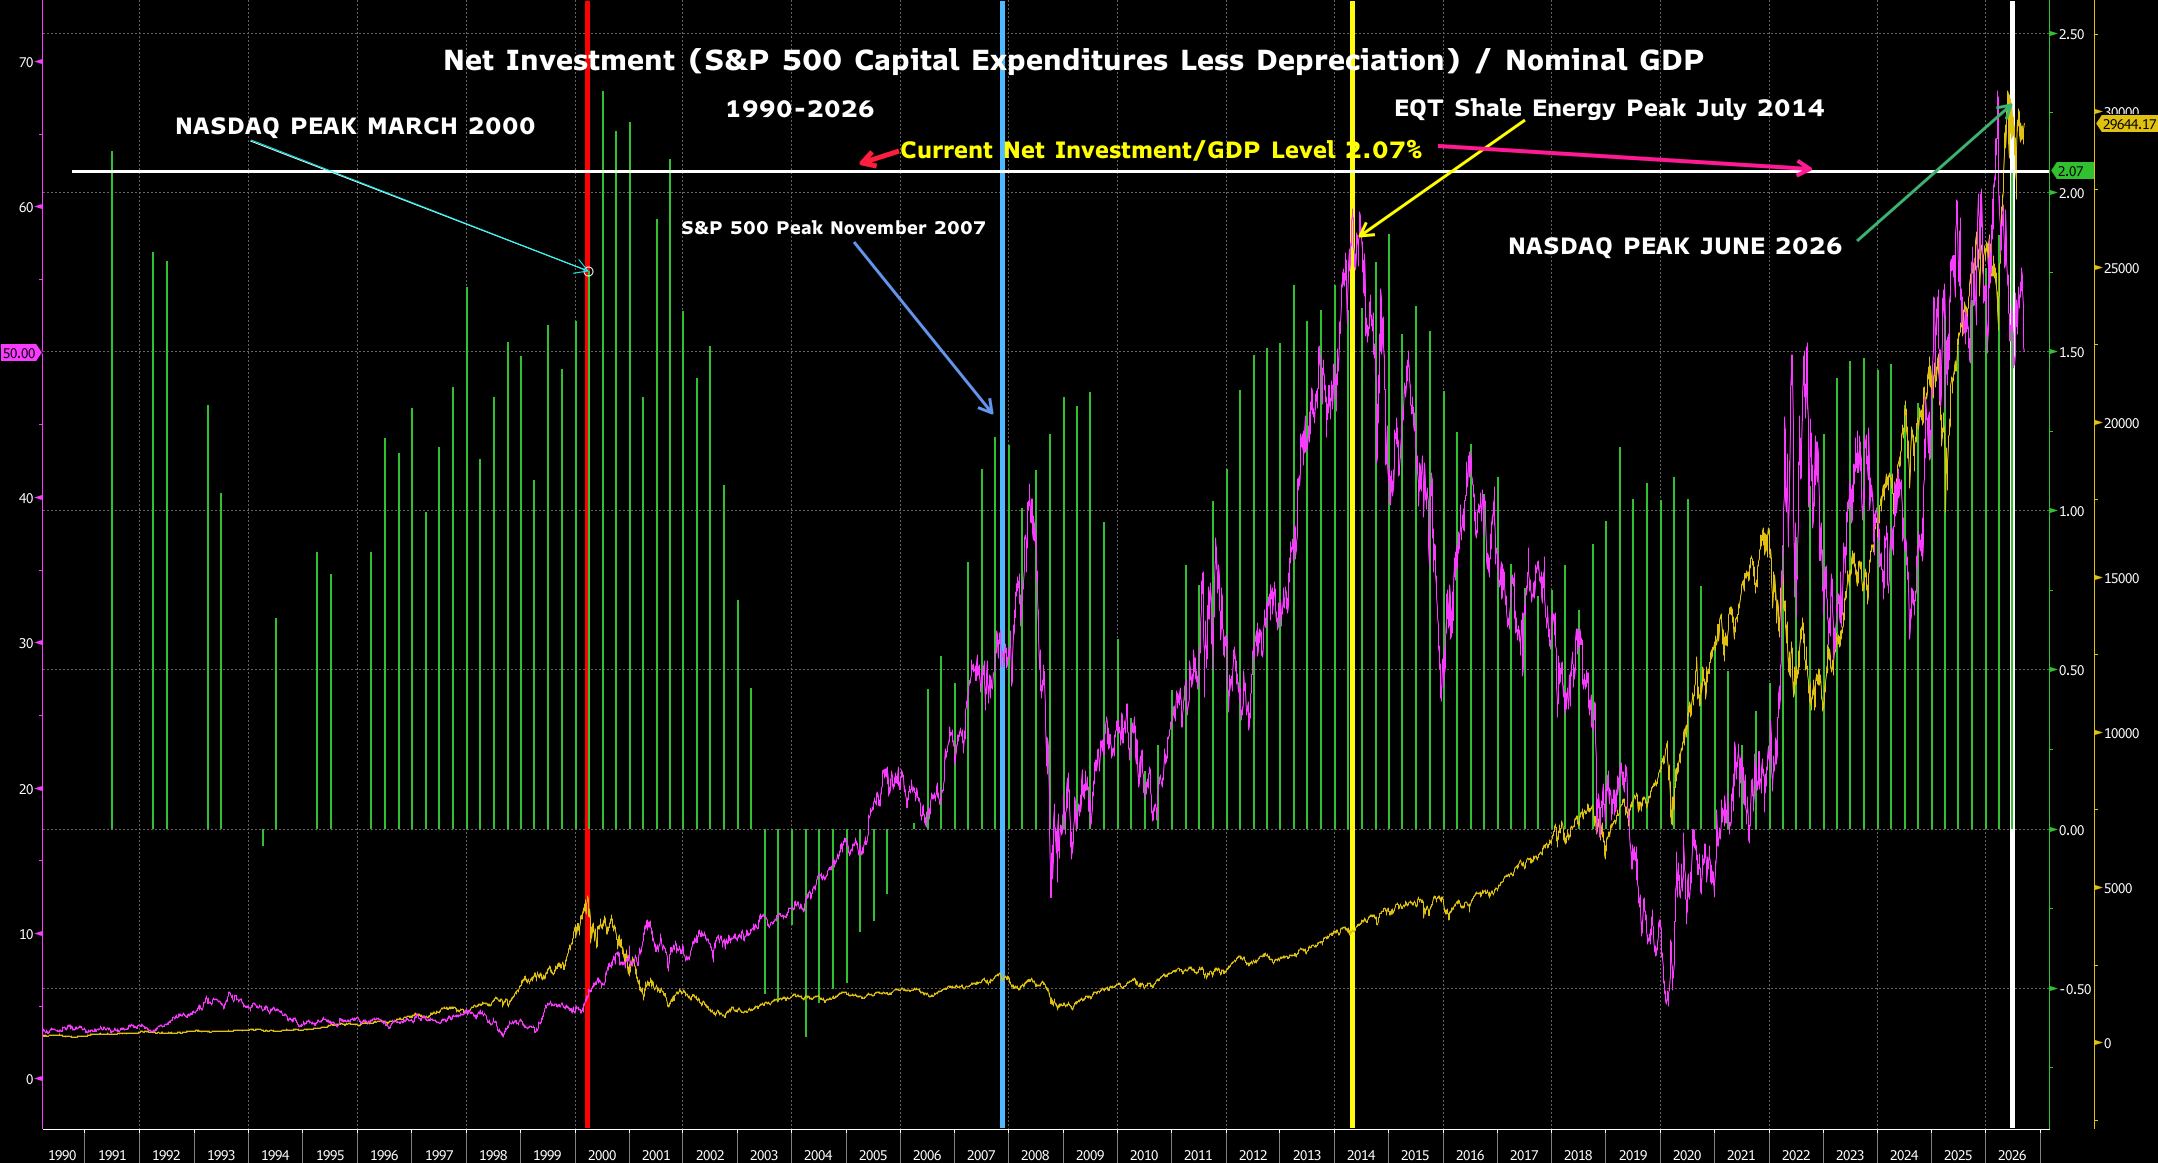
Microsoft, Amazon, Alphabet, Meta and Oracle have $3 trillion of commitments and are driving net investment to 2.07% of GDP, reviving…
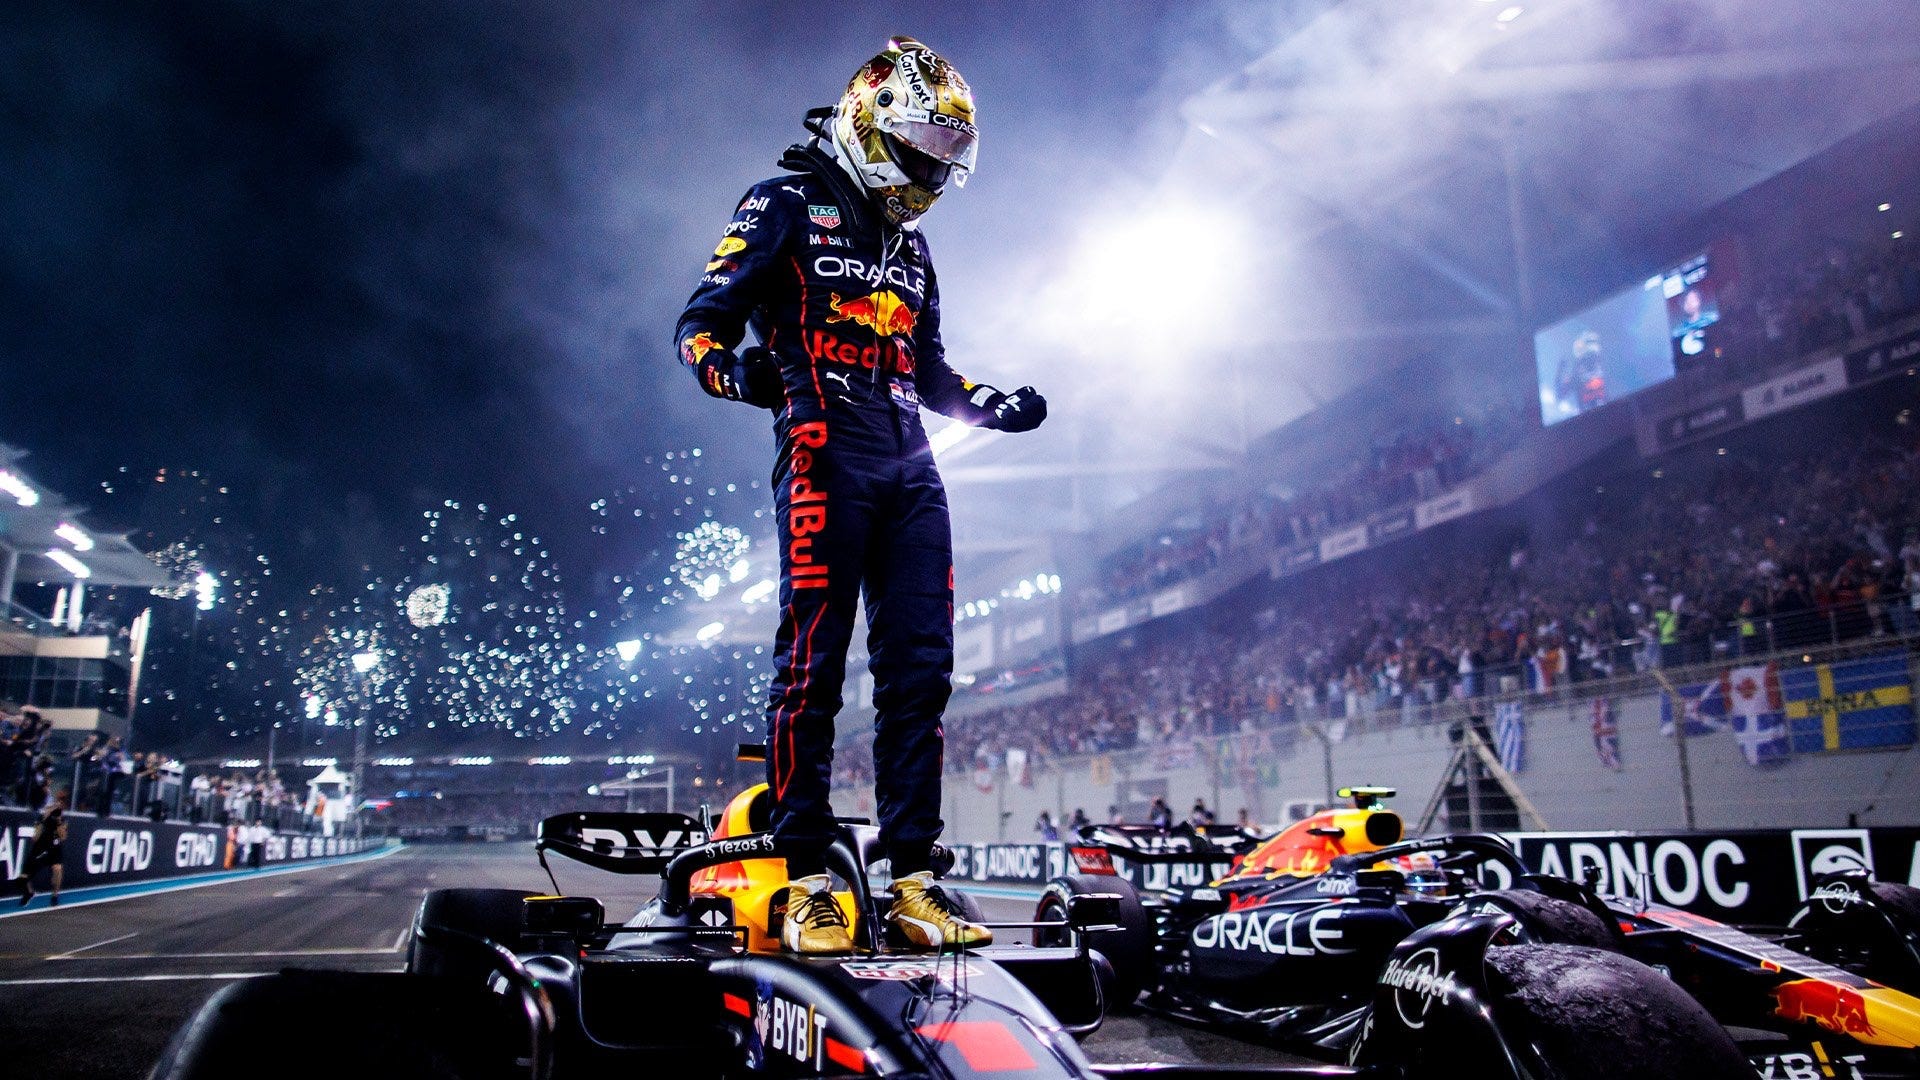
Liberty Media bought Formula 1 for $4.4 billion in 2017 and monetizes its exclusive commercial rights through racing, media and sponsorship.
 ZTS · long
Zoetis, the animal prescription-medicines company, is presented as a long investment despite concerns around its 2026 and 2027 outlook.
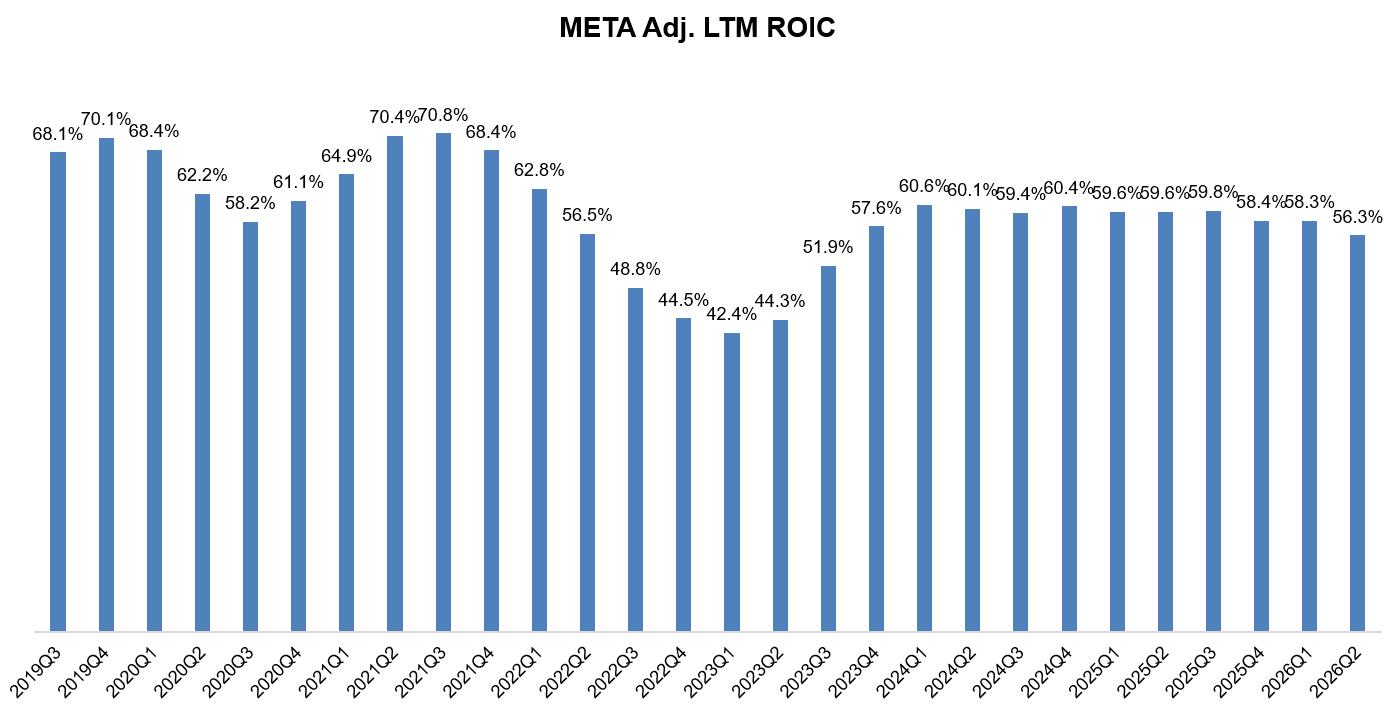
Meta’s adjusted LTM ROIC is in the mid-50s after excluding $80 billion of construction in progress; that capacity will lower returns as AI…
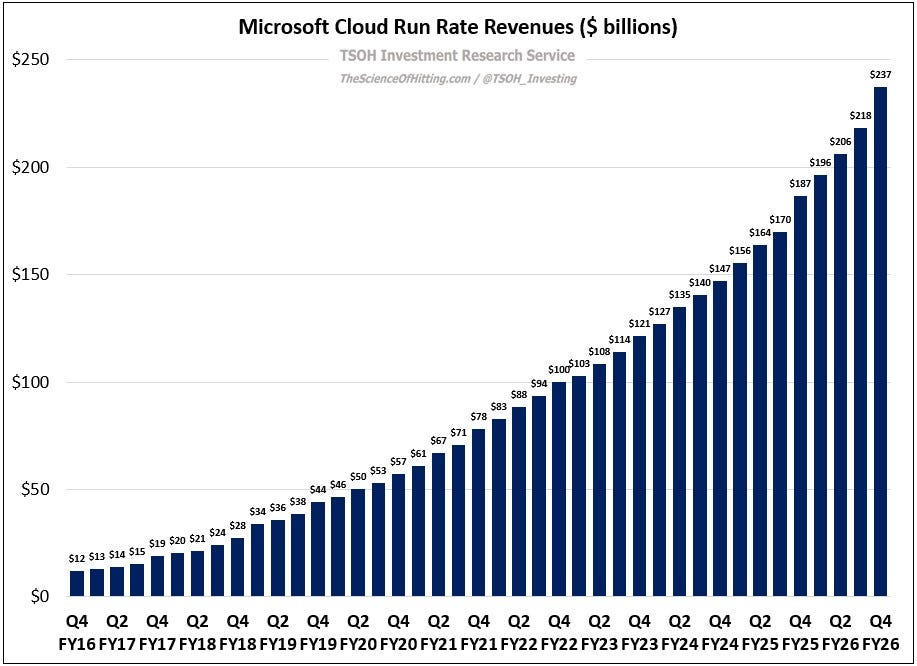
Microsoft’s cloud business grew from a $12 billion FY16 run rate to about $237 billion by FY26, while AI-era CapEx may exceed $200 billion…
ICE's purchase of MarketAxess spotlights takeout risk for value stocks, while the Situational Awareness blow-up, Kevin Warsh's FOMC presser…
Meta's Q2 advertising revenue rose 27% to $59.4 billion, while costs climbed 55%, cutting operating margin to 31%.
Roderick van Zuylen discusses Night Watch’s value strategy, catalyst-driven screening and positions in Asian equities including Dream…
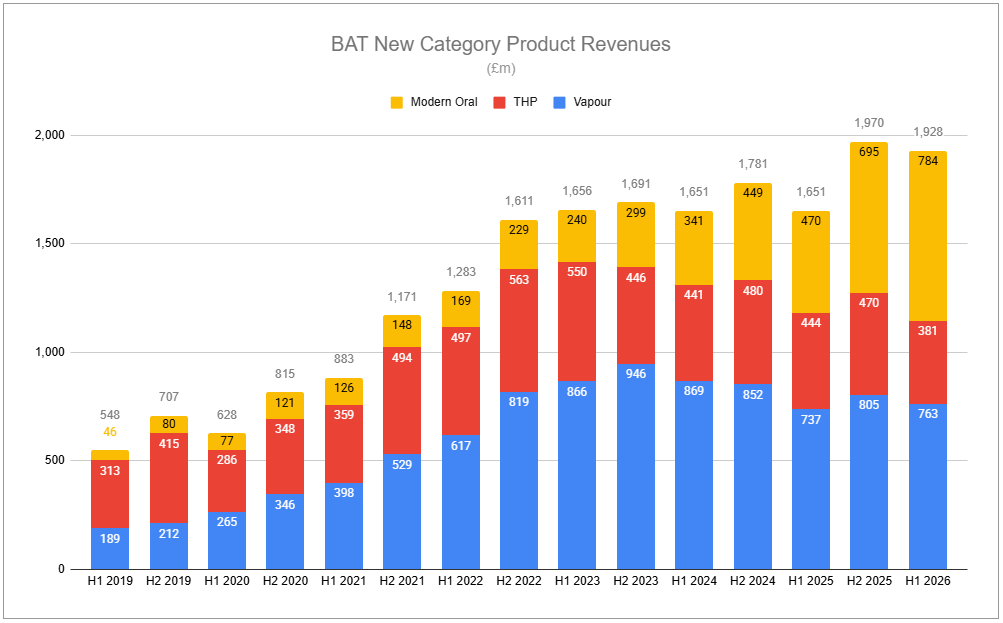
British American Tobacco targets 2 to 2.5x leverage by year-end as U.S. Vuse sales grow double digits and modern oral volumes rise 57.5% in…
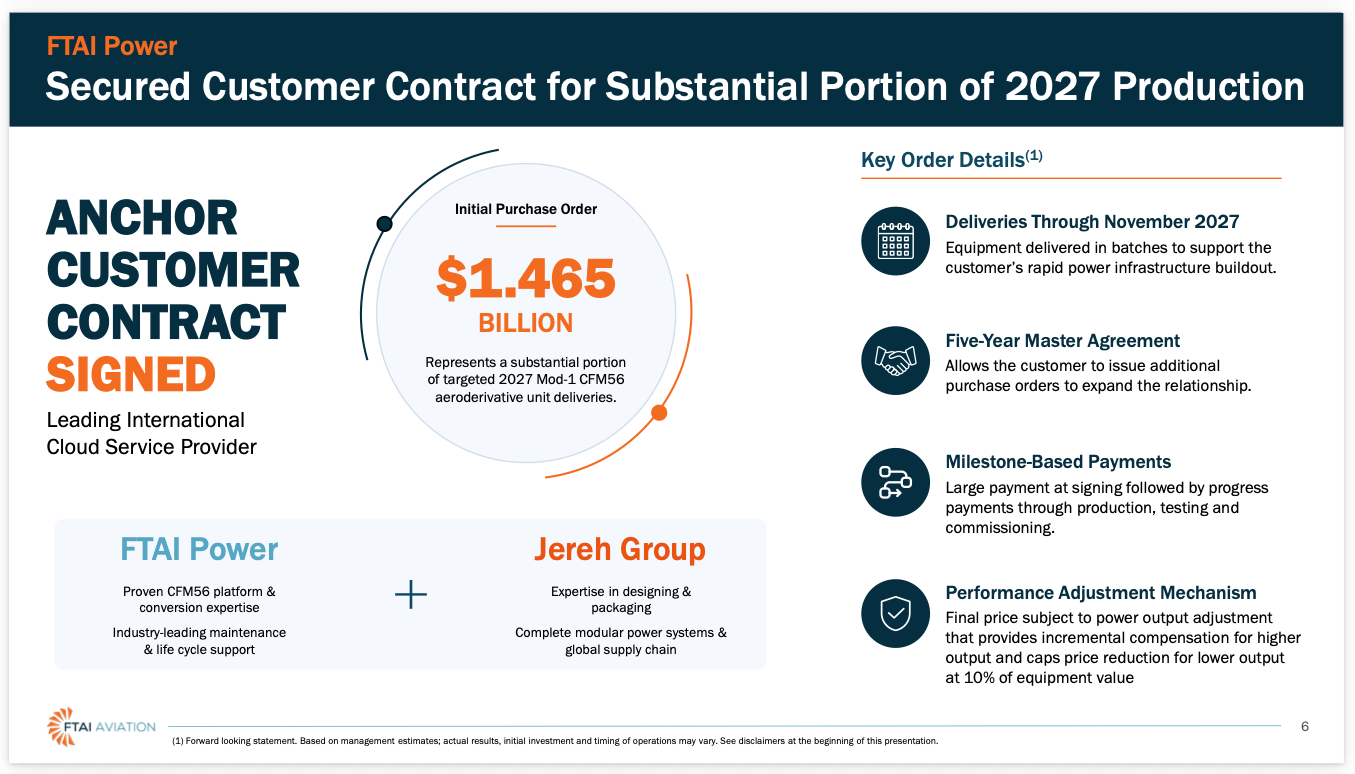
FTAI Aerospace margins fell to 28.5% as it pursues airline market share, while Power signed a $1.465 billion hyperscaler order and targets…
SoFi is GAAP-profitable for 11 straight quarters, with $14.8 billion in quarterly loan originations and over $45 billion in deposits…

Meta's 2Q26 revenue rose 27%, but capex, depreciation and nascent cloud and AI ambitions raise margin and return risks as it maximizes…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.