Updates
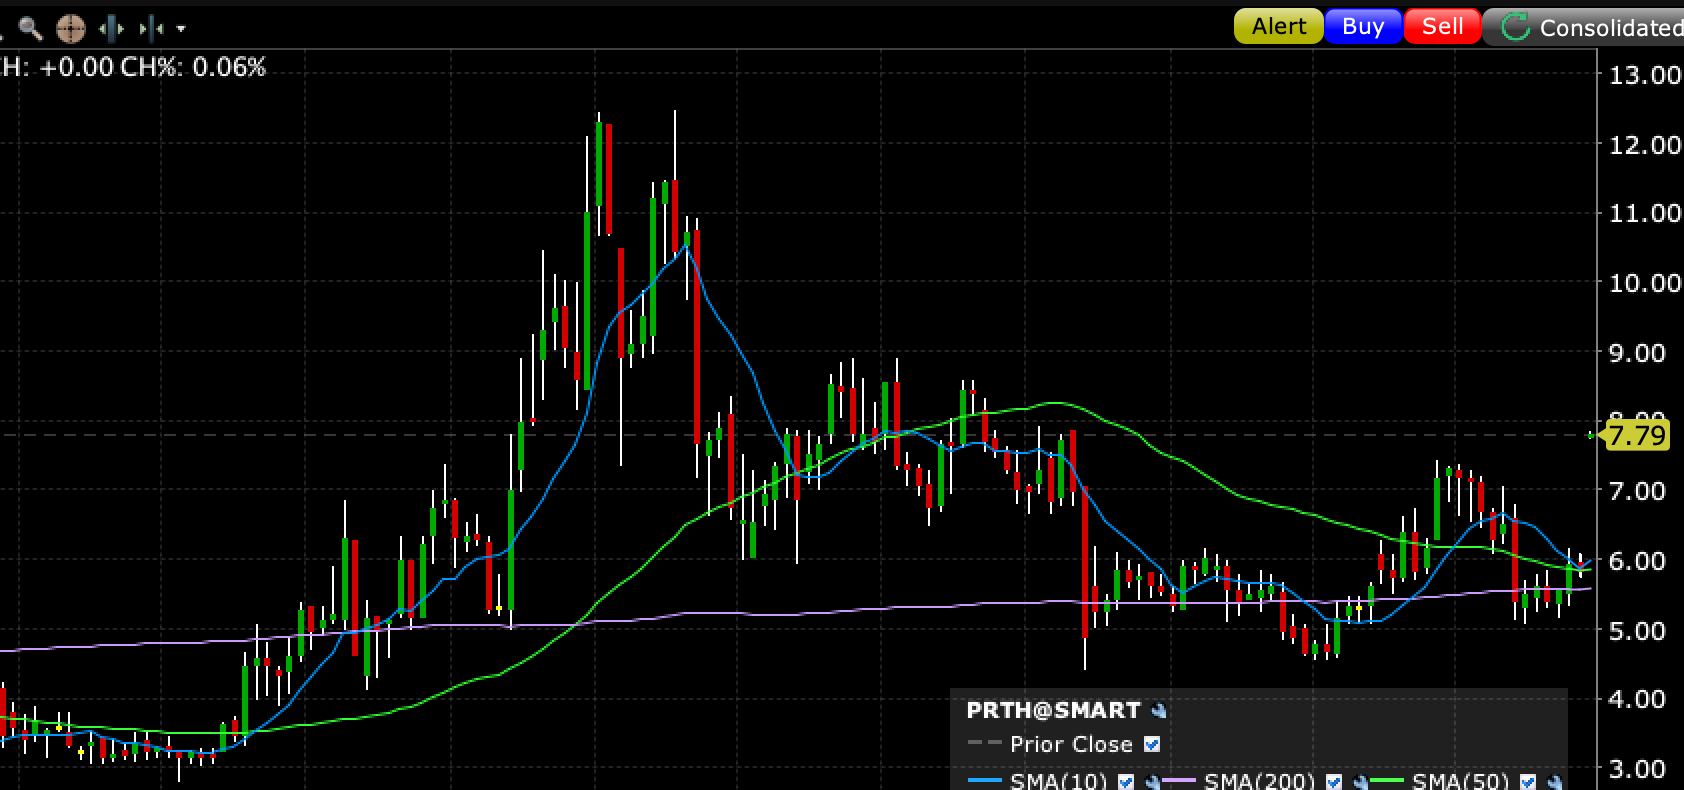
FGPR remains on track, PRTH's management buyout is set at $8.05, and microcap RAVE is described as cheap.
FGPR remains on track, PRTH's management buyout is set at $8.05, and microcap RAVE is described as cheap.
$NN Waiting a few extra months to get the NPRM doesn't matter compared to the ultimate value of the spectrum. Plus the NN spectrum can/will be used for many additional vital issues like IOT, drones and other AI uses.
$NN Finally, check out the comments recently made by Anterix regarding how they are thinking about the value of their spectrum. The numbers are much higher than I had ever imagined. I am long a bit of $ATEX. NN spectrum is far more powerful than the low band spectrum held by ATEX
Anyone who thinks @ryancohen won't run both $GME and $EBAY ... is wrong.
$POET $2.5B market cap Canada-based (formerly TSXV-listed) semi component designer. Perennially on the verge of commercialization ($1.4M LTM sales, hemorrhaging cash). Heavily promoted into a $400M offering on 5/18. Dubious order w related party, FEOC, PFIC, among many issues.
@Stl_MAR @Catahoula_Value I think (from past close experience) that the family calling the $TRCY shots is hopelessly inept. Doesn’t mean they won’t sell it at some point but they have turned away some great alternatives.
$BCOW Fact check: 100% true https://t.co/AqIAdOnsSa
@Catahoula_Value It feels like $BCOW management would rather continue stealing from the shareholders. $LRBI is performing well on its own and improving so not needed. Sure does spotlight the values though. $MBBC also in $PSBQ backyard where Nick Z is really improving his bank.
Home run merger for $PSBQ holders in sale to $BFC https://t.co/wujj6AML12
Oklo shares have fallen 77% since October 2025 as commercialization slips beyond 2027, revenue estimates fall and dilution continues.
 Ian Bezek 3 clicks
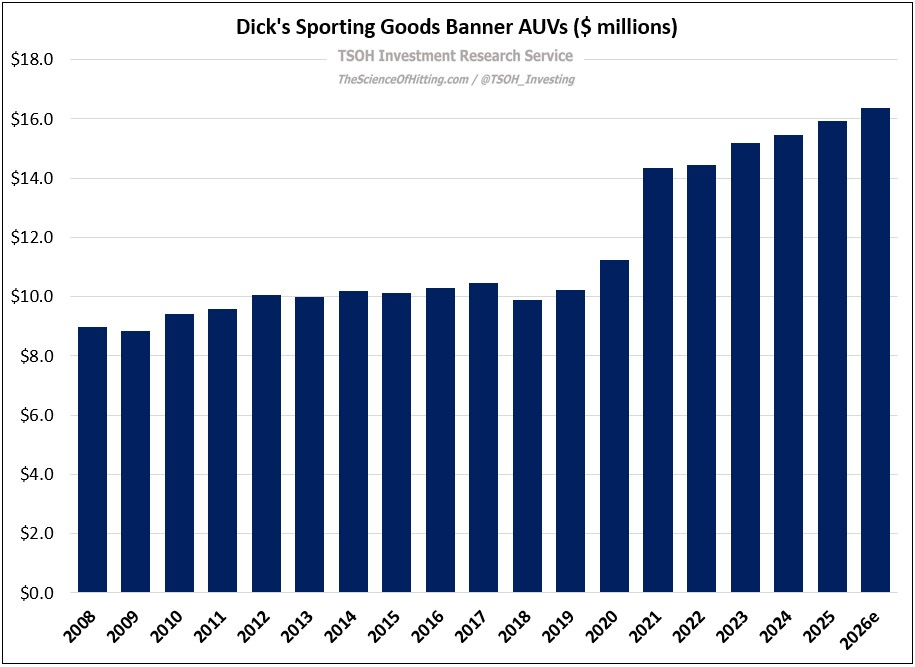
TSOH Weekly Roundup covers Ralph Lauren’s $1 billion distribution pullback, Peloton’s $2,195 foldable treadmill and $800 million…
IonQ's Q2 2026 revenue rose 287% to $80.1 million, but durability hinges on its $485 million RPO and enterprise adoption for production AI…
 Deep Value Investing
Rocket Companies combines Redfin, Rocket Mortgage and Mr. Cooper into an end-to-end homeownership platform, adding mortgage servicing fees…
Eckert & Ziegler trades near €12, about 14 times expected earnings, as its isotope supply business expands with radiopharma demand despite…
Mach Natural Resources' Q2 distributable cash fell to $60.1 million as development spending rose, prompting a distribution cut; its units…
Ouster began coverage at Accumulate as lidar revenue rose 56% in Q2, while annual cash burn near $80 million has driven an 86% share-count…
AAON's BASX data-center cooling business targets $1 million to $1.5 million per megawatt, with new capacity and backlog conversion expected…
Vista Energy's Q2 2026 production rose 32% and revenue 89% as Vaca Muerta acquisitions expand its Argentine export platform and cash…
 Alan Galecki 3 clicks
IEH booked $3.6 million in mobile-defibrillator connector orders, lifting its medical revenue outlook and diversifying beyond aerospace and…
Ciena and Fabrinet benefit as AI clusters require high-speed optics within and between data centers, through networking systems and…
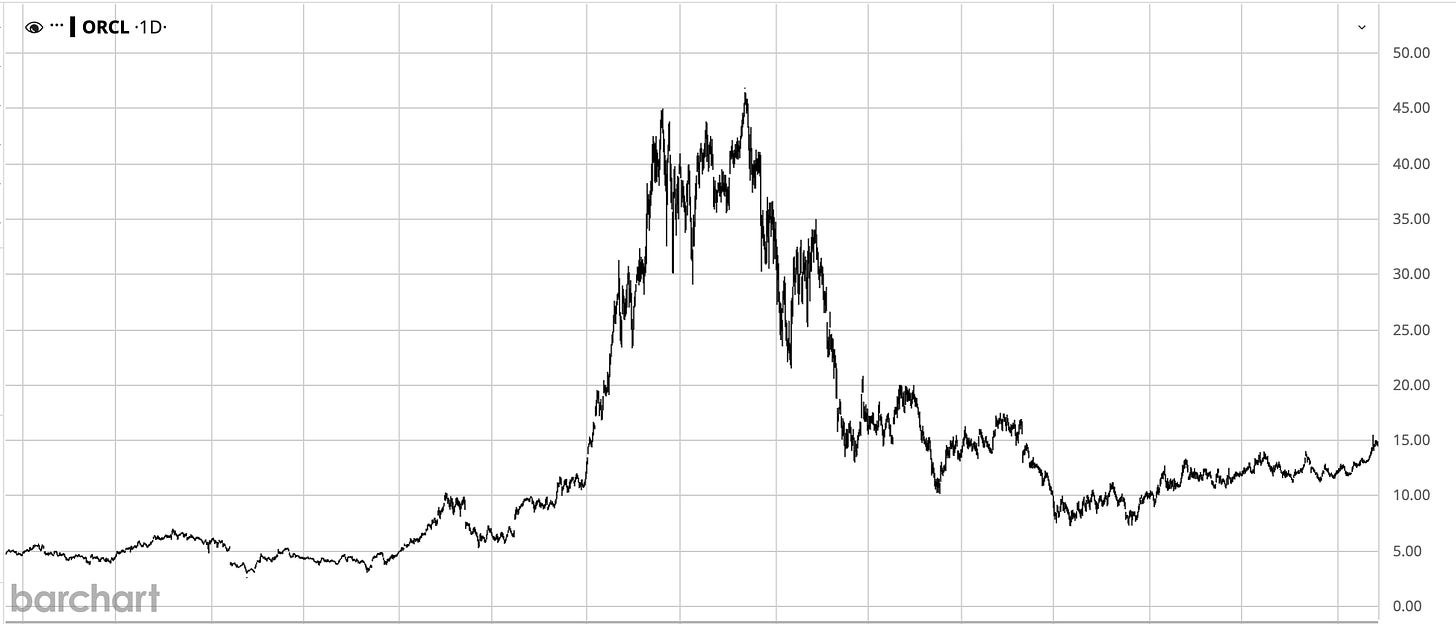
Oracle’s Q1 FY2027 AI infrastructure push relies on leasing, debt, customer prepayments and OpenAI’s Stargate project, resembling a…
Honeywell is refocusing on automation after its Aerospace and Advanced Materials spinoffs, with a 1.1x book-to-bill ratio, raised guidance…
 Gen Alpha 1 click
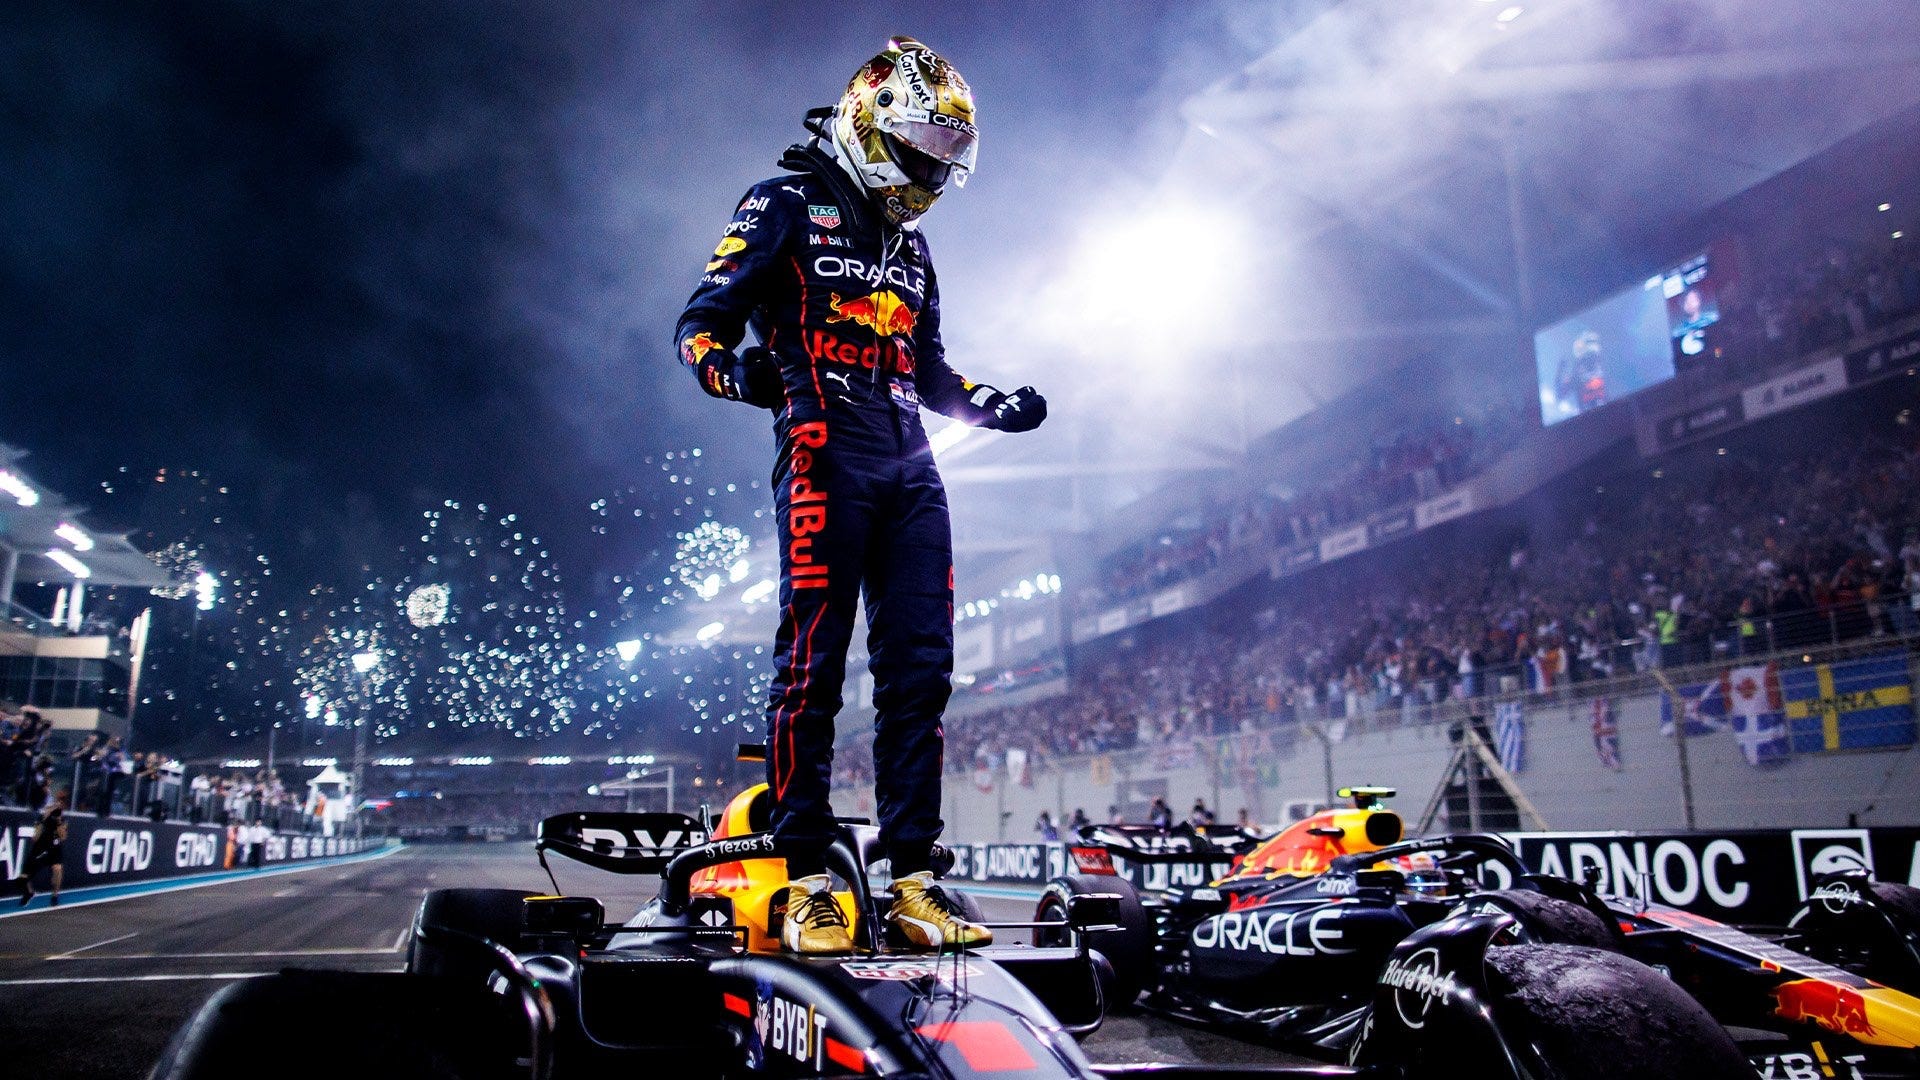
Liberty Media bought Formula 1 for $4.4 billion in 2017 and monetizes its exclusive commercial rights through racing, media and sponsorship.
Firefly Aerospace ended Q2 2026 with $1.5 billion backlog and a 2.49x book-to-bill ratio, adding lunar, defense and launch contracts for…
Atlassian targets a $140 billion market growing 14% annually, with Rovo reaching 5 million monthly active users and assisted actions rising…
 Muhammad Cheema
 GLIBA · long
Liberty Capital Corp, GLIBA, is pitched long following its July 2025 spinoff from Liberty Broadband.
Realty Income trades at 12.7 times forward AFFO with a 5.8% yield, supported by high occupancy, a 73% payout ratio and raised 2026 guidance.
 Sharon McArd 2 clicks
ZIM’s proposed deal carries a claimed 23% spread and 110% IRR by Q4 2026, with Q3 and Q4 dividends potentially raising returns if closing…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.