The Enron-Era Tricks Are Back in AI: How These Companies Are Hiding Their Debt | The Weekly Wrap
Steve Eisman says AI companies are reviving Enron-era off-balance-sheet and circular financing, alongside concerns around Oracle and Blue Owl.
Steve Eisman says AI companies are reviving Enron-era off-balance-sheet and circular financing, alongside concerns around Oracle and Blue Owl.
@SW_Resurgo I dunno, I see lots of very real cases of people doing shit like this. Remember the guy who went all in on $PDD and then had a royal crash out?
@WaterworldCapi1 @madthunderdome $TLN - Josh Shapiro will privatize it.
Blackjack 21 Index (favorite collection of global banks and insurers) jumps to +38%, 36% ahead of $XLF Notable ATH's: Juroku Financial, Mebuki Financial https://t.co/HIBUQ57PBF
New low on $NKE -2% off BofA downgrade "Nike’s innovation continues to be overshadowed by pressure on its classics business." https://t.co/ClkHft164S
@rubicon59 Problem is $APP is in the "this might be a total scam" bucket. If it's not, yeah it's cheap. I'm not so sure. Could be wrong, but it never smelled right to me.
You guys are sleeping on $GME https://t.co/i9EzDPRTz1
IonQ's Q2 2026 revenue rose 287% to $80.1 million, but durability hinges on its $485 million RPO and enterprise adoption for production AI…
 Deep Value Investing 2 clicks
Rocket Companies combines Redfin, Rocket Mortgage and Mr. Cooper into an end-to-end homeownership platform, adding mortgage servicing fees…
Eckert & Ziegler trades near €12, about 14 times expected earnings, as its isotope supply business expands with radiopharma demand despite…
Ciena and Fabrinet benefit as AI clusters require high-speed optics within and between data centers, through networking systems and…
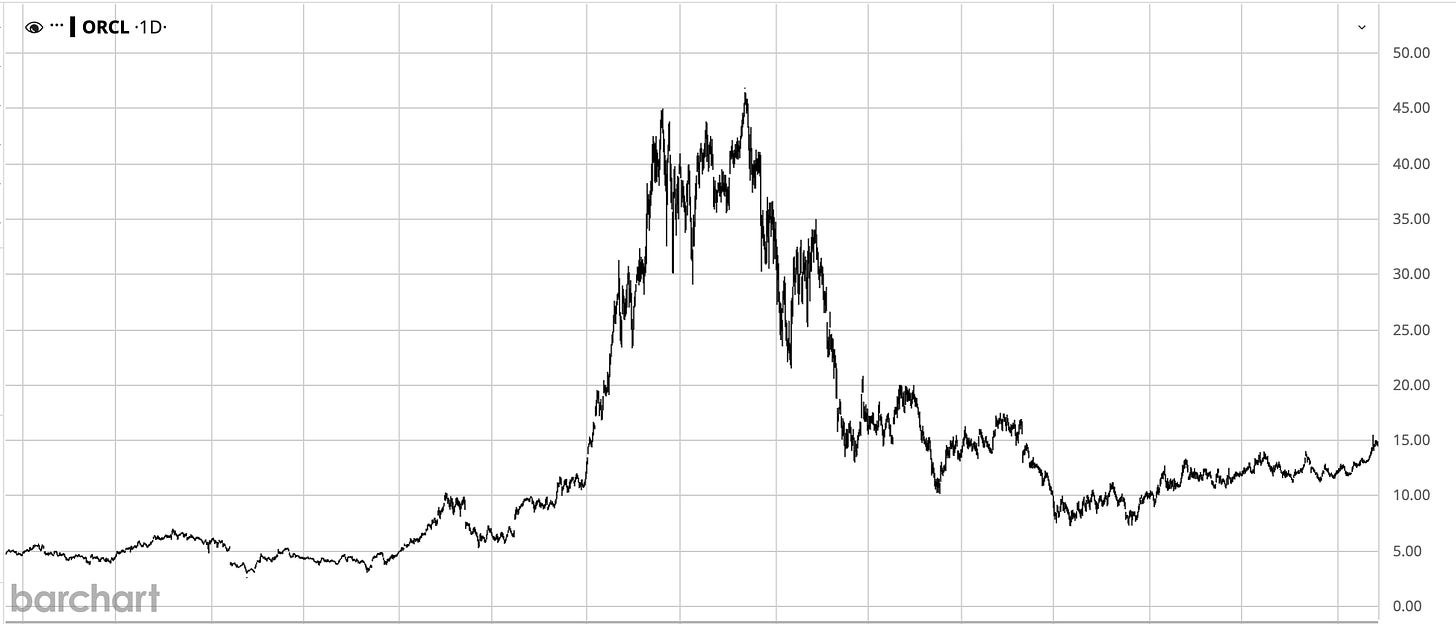
Oracle’s Q1 FY2027 AI infrastructure push relies on leasing, debt, customer prepayments and OpenAI’s Stargate project, resembling a…
Honeywell is refocusing on automation after its Aerospace and Advanced Materials spinoffs, with a 1.1x book-to-bill ratio, raised guidance…
 Gen Alpha 1 click
Liberty Media bought Formula 1 for $4.4 billion in 2017 and monetizes its exclusive commercial rights through racing, media and sponsorship.
Micron’s customer agreements, Analog Devices’ acquisitions, Ondas’ GATE deal and Baker Hughes’ power systems position them for AI…
SiTime’s MEMS timing portfolio, Renesas acquisition and 1.6T transition are positioned to drive growth and margin expansion as supply…
 Gil Rotstein 2 clicks
 RBLX · long
Roblox's valuation has fallen from 30x to 50x forward EBITDA, framing the selloff as a long opportunity despite near-term headwinds.
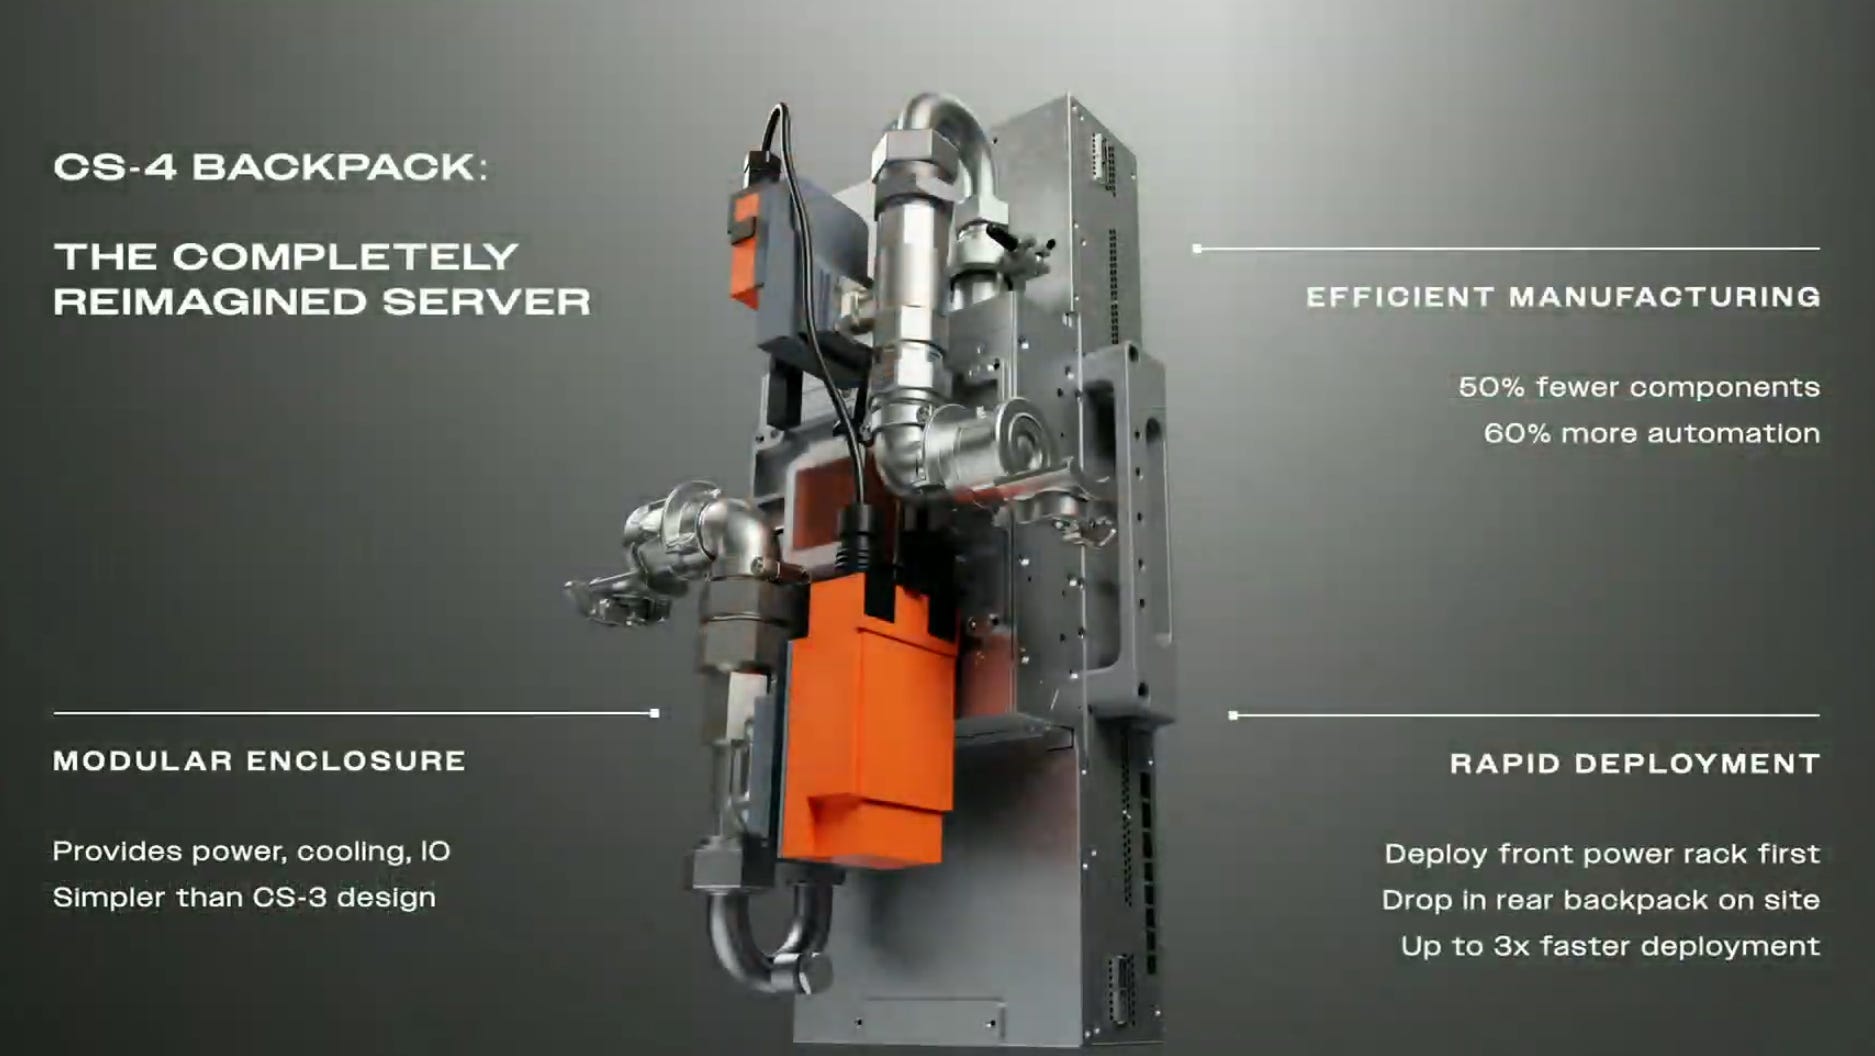
Cerebras’ three-wafer Supernova system doubles I/O and clock speed, improving latency and parametric yield, but hardware gross-margin…
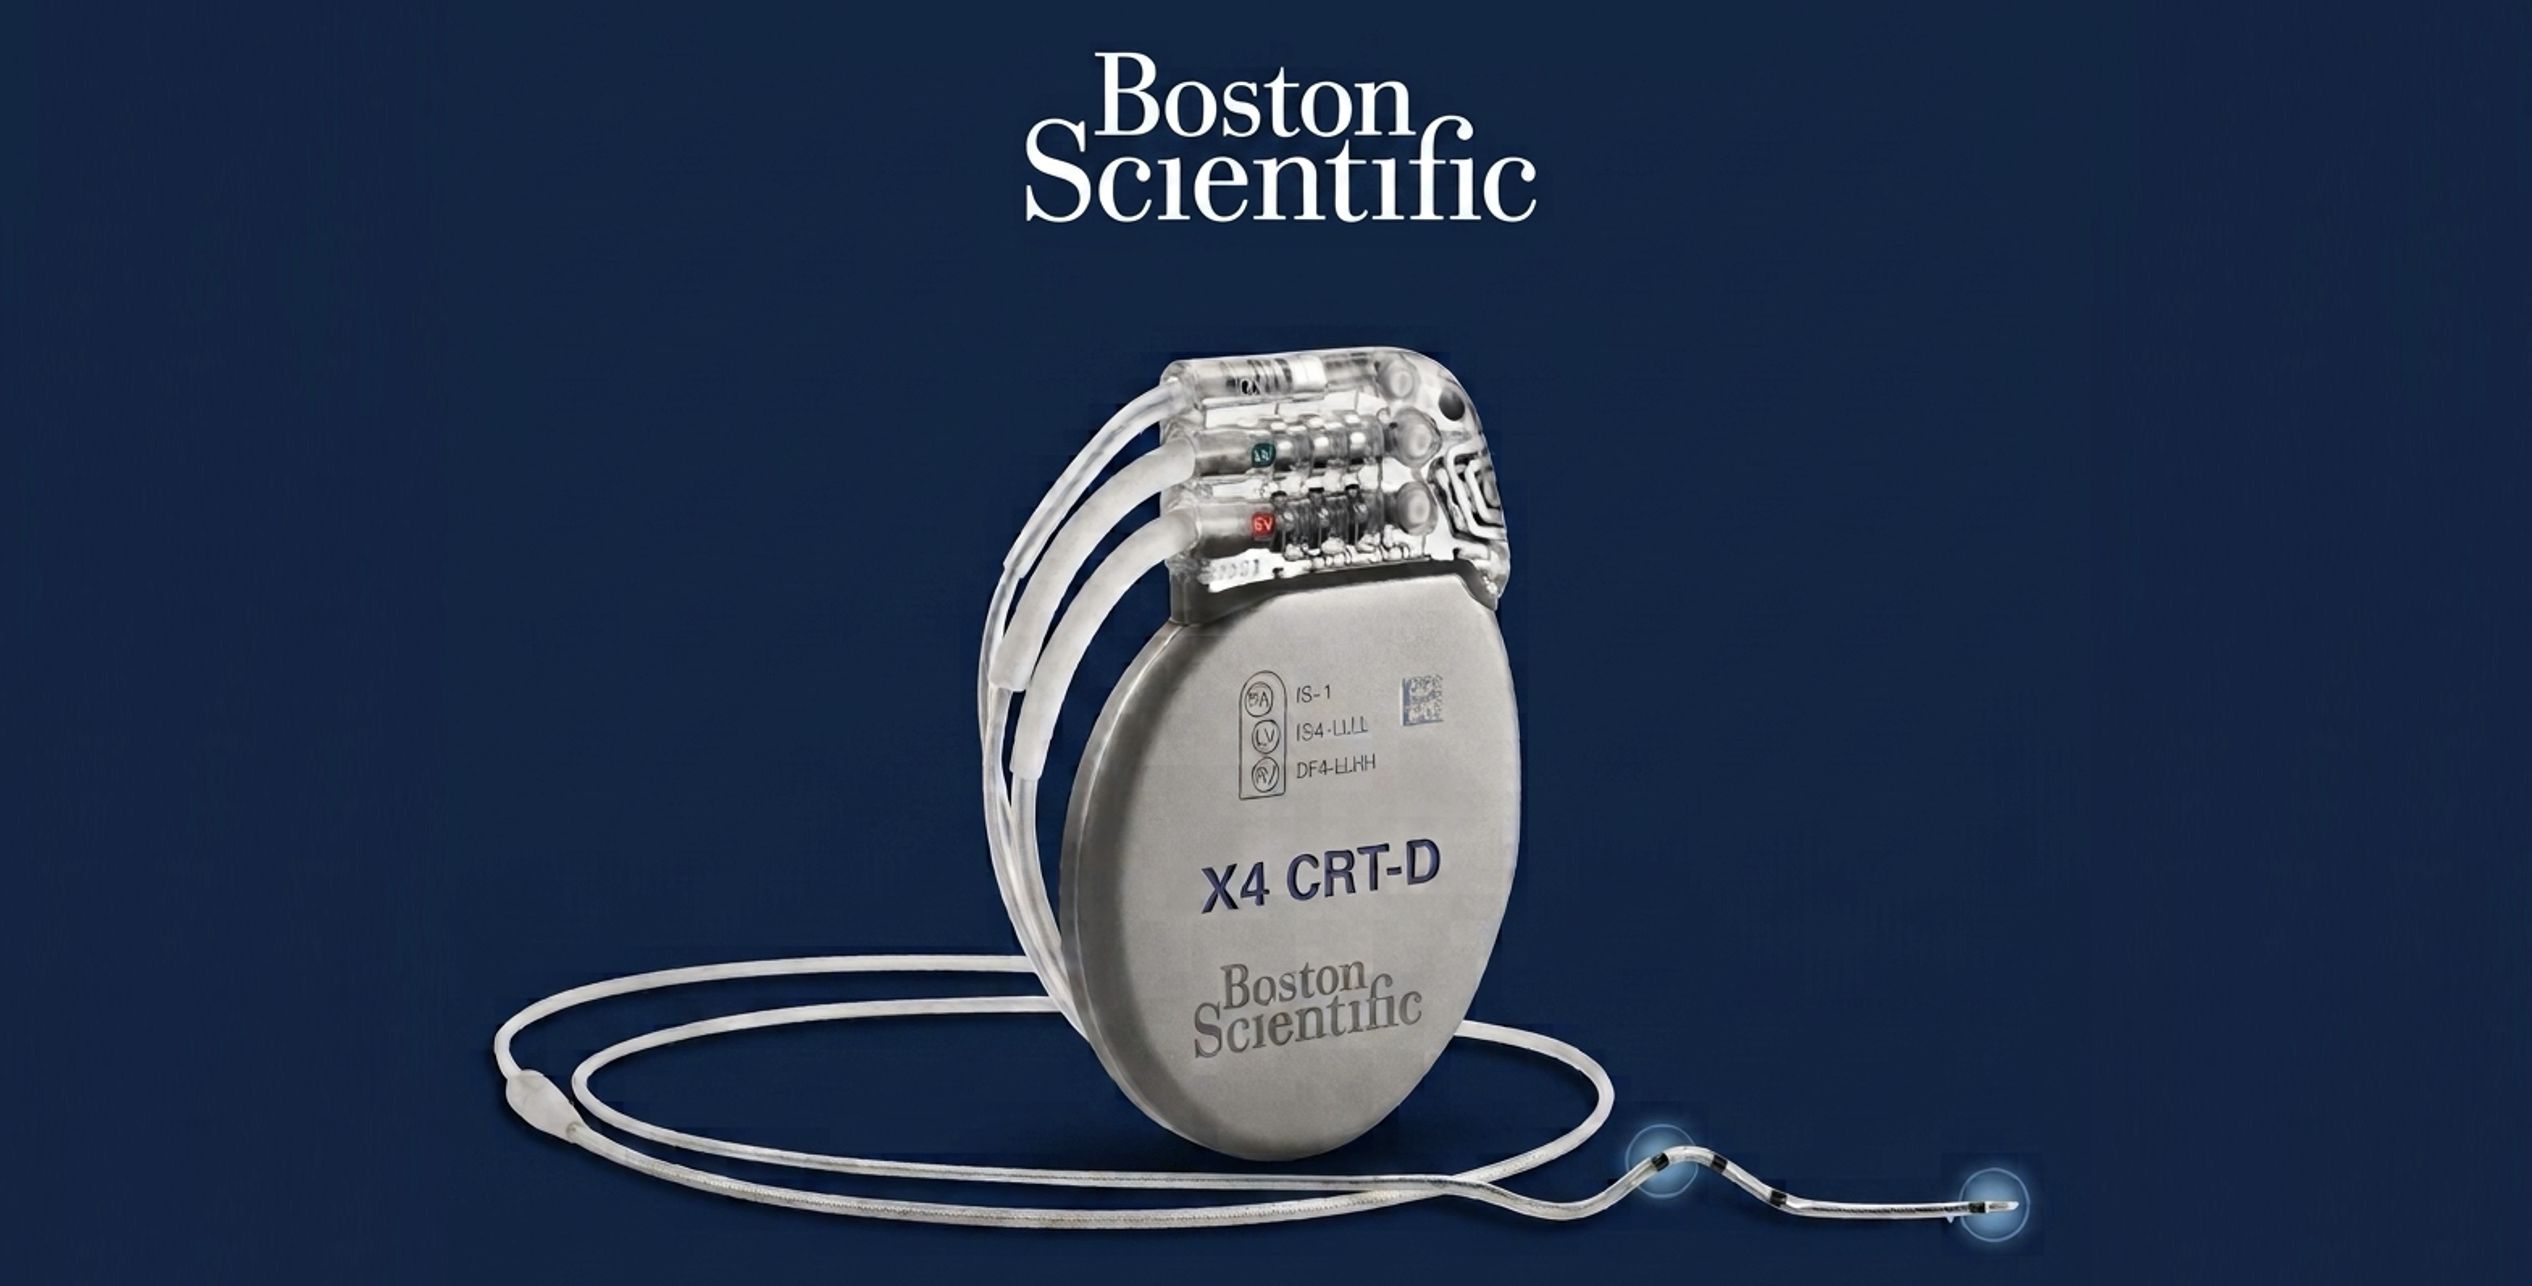
Boston Scientific’s Farapulse competition and weaker Watchman demand have slowed growth, prompting a $2 billion buyback, restructuring and…
TWG Global’s roughly $2 billion Carvana stake is already pledged to Citigroup, limiting Mark Walter’s ability to use CVNA shares for…
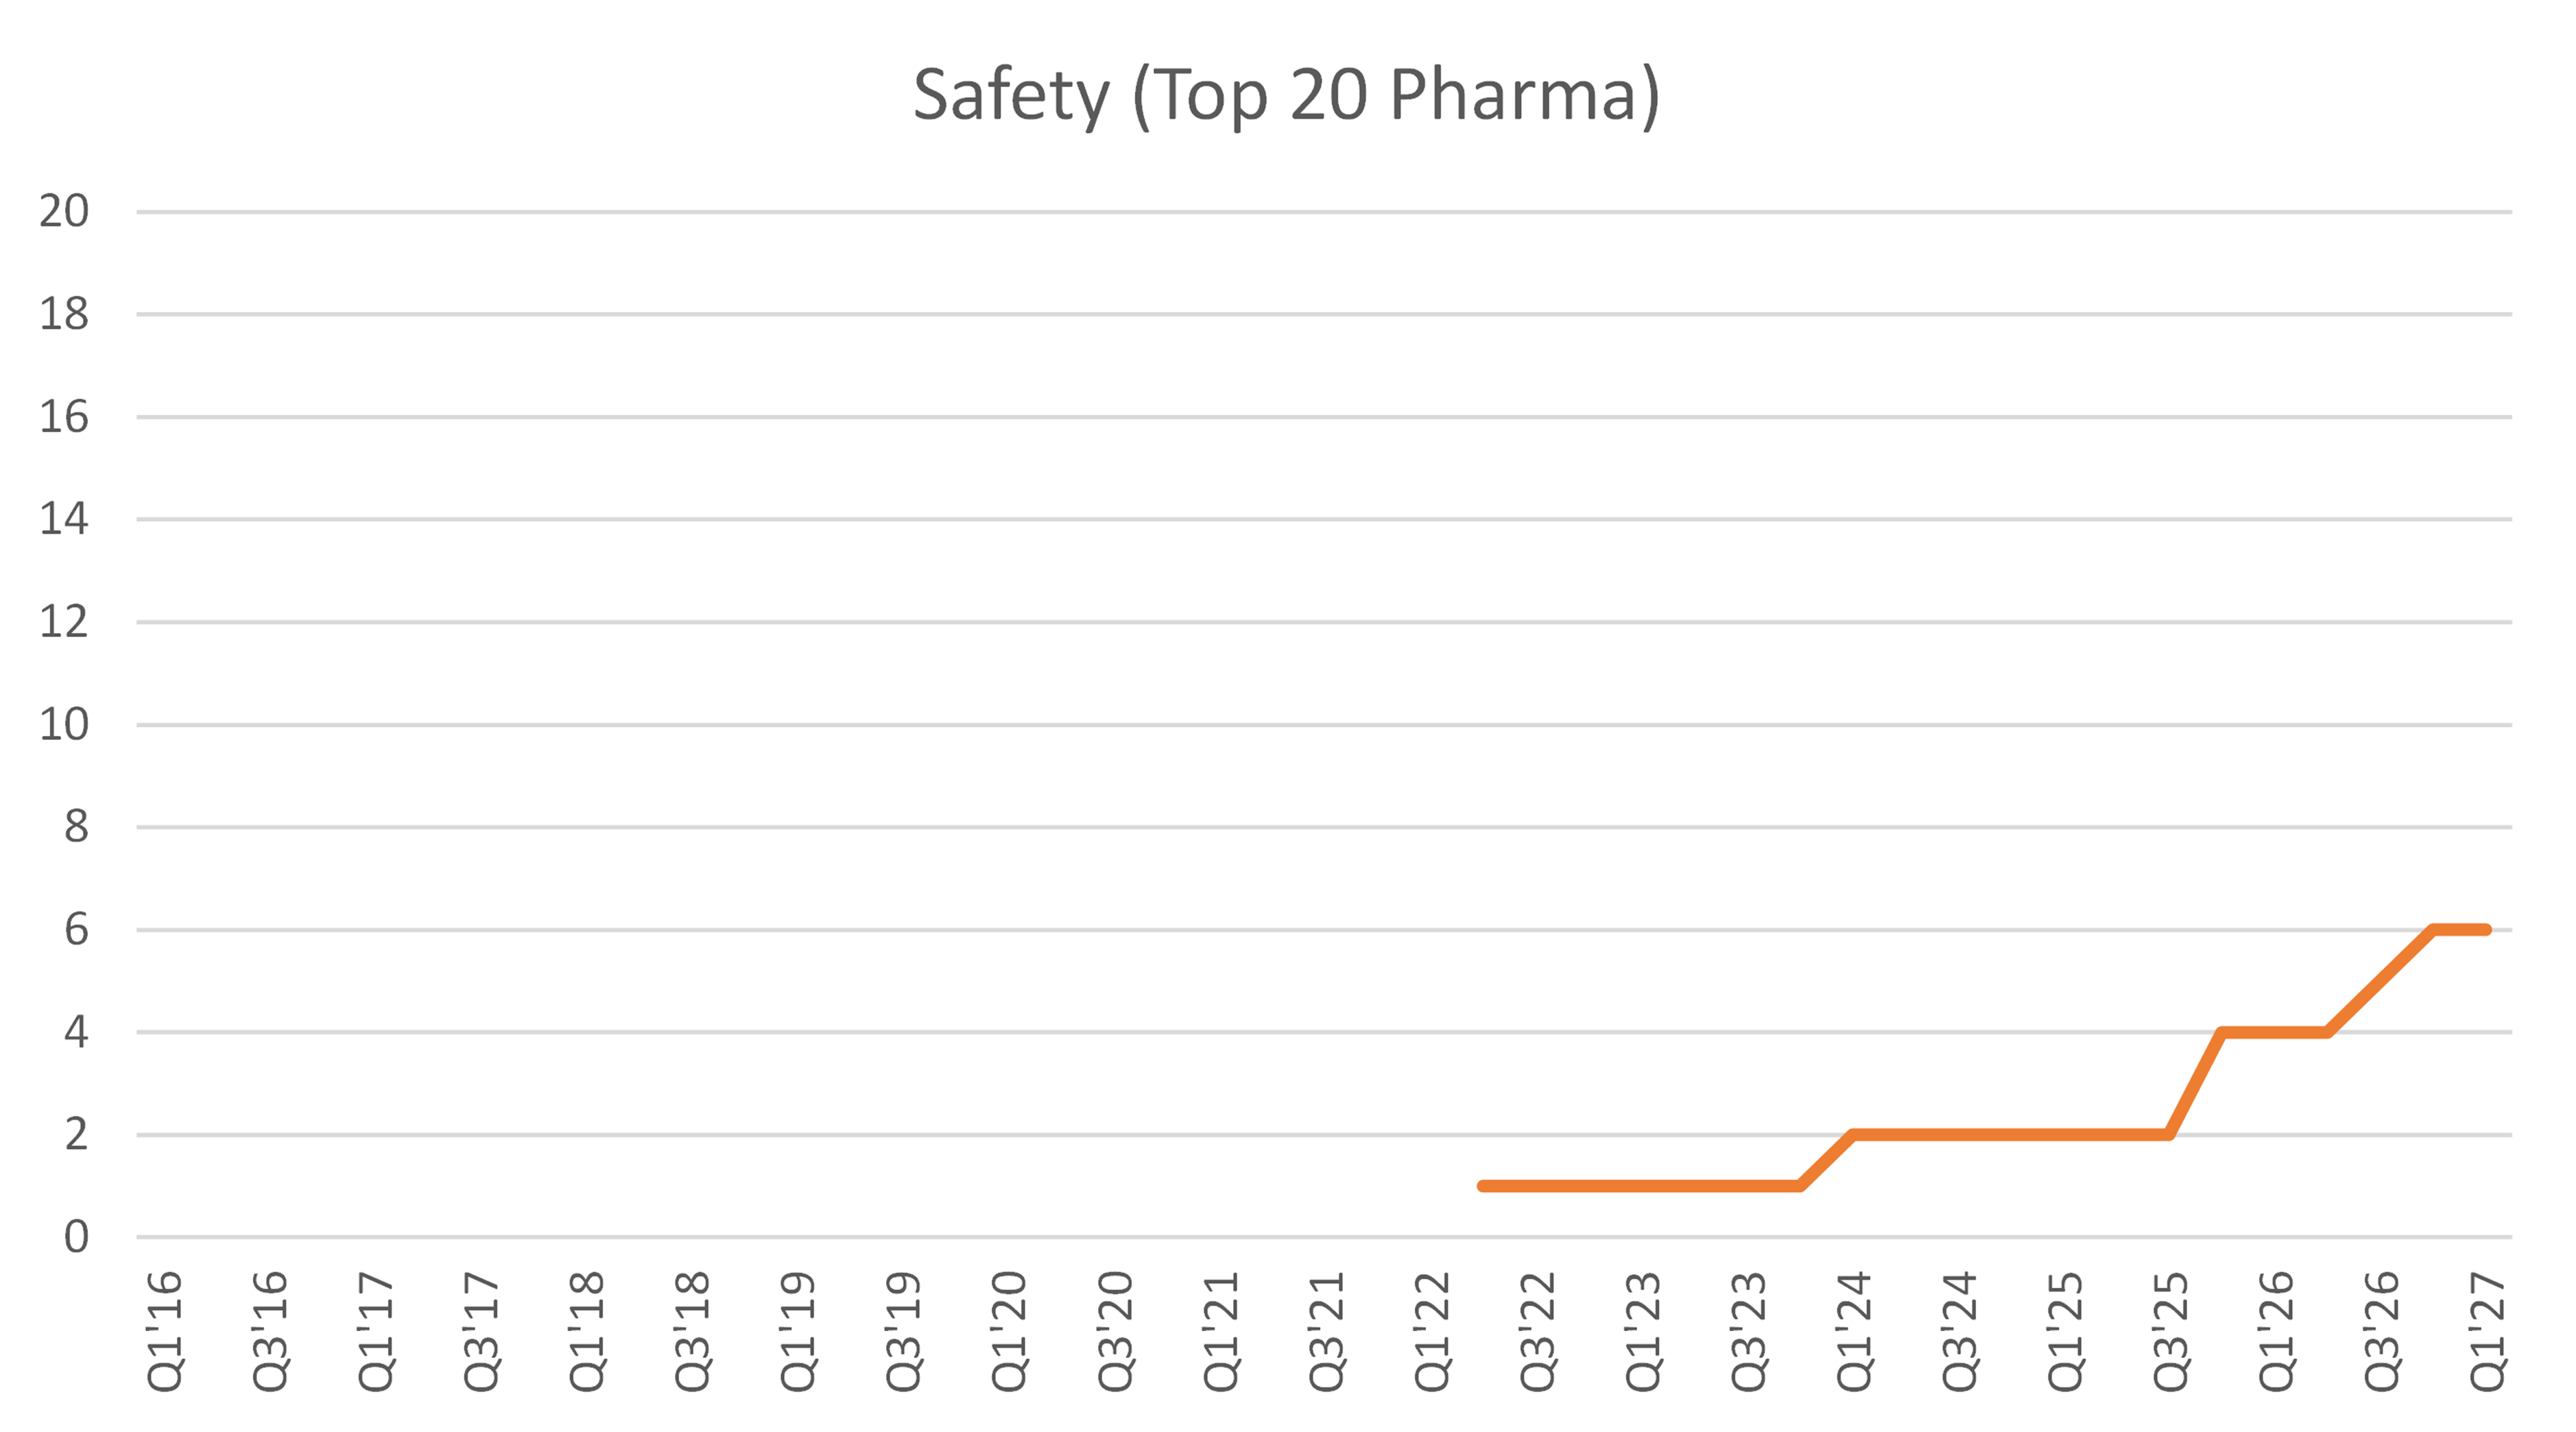
Veeva plans Falcon agents for pharmacovigilance, clinical-trial documents and regulatory writing, targeting multibillion-dollar…

IREN awarded each co-CEO roughly 9 million RSUs, about 2.5% of shares and $400 million, in exchange for no further equity grants until…
Rocket Lab and Firefly won access to US space contracts as AI-driven HBM demand tightens memory-chip supply through 2027.
Ukraine’s Black Sea attacks on CPC infrastructure threaten Kazakhstan’s 1.4 million bpd oil export route through Russia, putting Chevron’s…
Intel's silicon photonics CPO work shows precise 16-wavelength lasers but suffers SOA four-wave-mixing noise and weaker link performance…

Nubank's 140 million customers, 20% efficiency ratio and 30% ROE frame whether its high-teens P/E reflects a scalable fintech or a maturing…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.