CoreWeave, Inc (CRWV)
CoreWeave funds GPU data-center expansion with debt backed by $104 billion in contracted revenue, while GPU cloud rentals generate roughly 99% of sales.
CoreWeave funds GPU data-center expansion with debt backed by $104 billion in contracted revenue, while GPU cloud rentals generate roughly 99% of sales.
Newest out. Altria: An Oral History "Q1'26 note" $MO $PM $BTI $IMBBY $HAYPP $STG https://t.co/eeDaXkTgn3
@DSacksCreative $NN The low band spectrum controlled by NN is quite valuable. $GSAT is a terrific comp. Sold for 11.6 billion. In many ways, our spectrum is extremely valuable and can carry more data and is more vital. Very desirable asset.
Seems like $PSUS and $PS going to trade worse than I expected. Looks like PSUS could open at a 20% discount to NAV and PS to trade below the $10 bn valuation from the latest 3rd party pre-IPO raise. https://t.co/Ix6uqF61LJ https://t.co/F5UNDNNVMb
@EricTheUmpire If you want exposure, buy $PSH.LN (or $PSHZF) which is trading at around 70% of NAV (implies $35/share for $PSUS). https://t.co/oSFLPLfnqr
Newest out. Philip Morris International: Centered "Q1'26 note" $PM $BTI $MO $IMBBY $HAYPP $STG https://t.co/QWIjmx81rA
I just published my Earnings Update about the Q1 2026 of Evolution $EVO $EVVTY. You can find it in the Portfolio section of the blog :) https://t.co/QXlBS93lji
Copart’s $1.9 billion ACV Auctions acquisition targets renewed growth, with EPS accretion expected by fiscal 2028 as insurance…
 Robert J. Lake 2 clicks
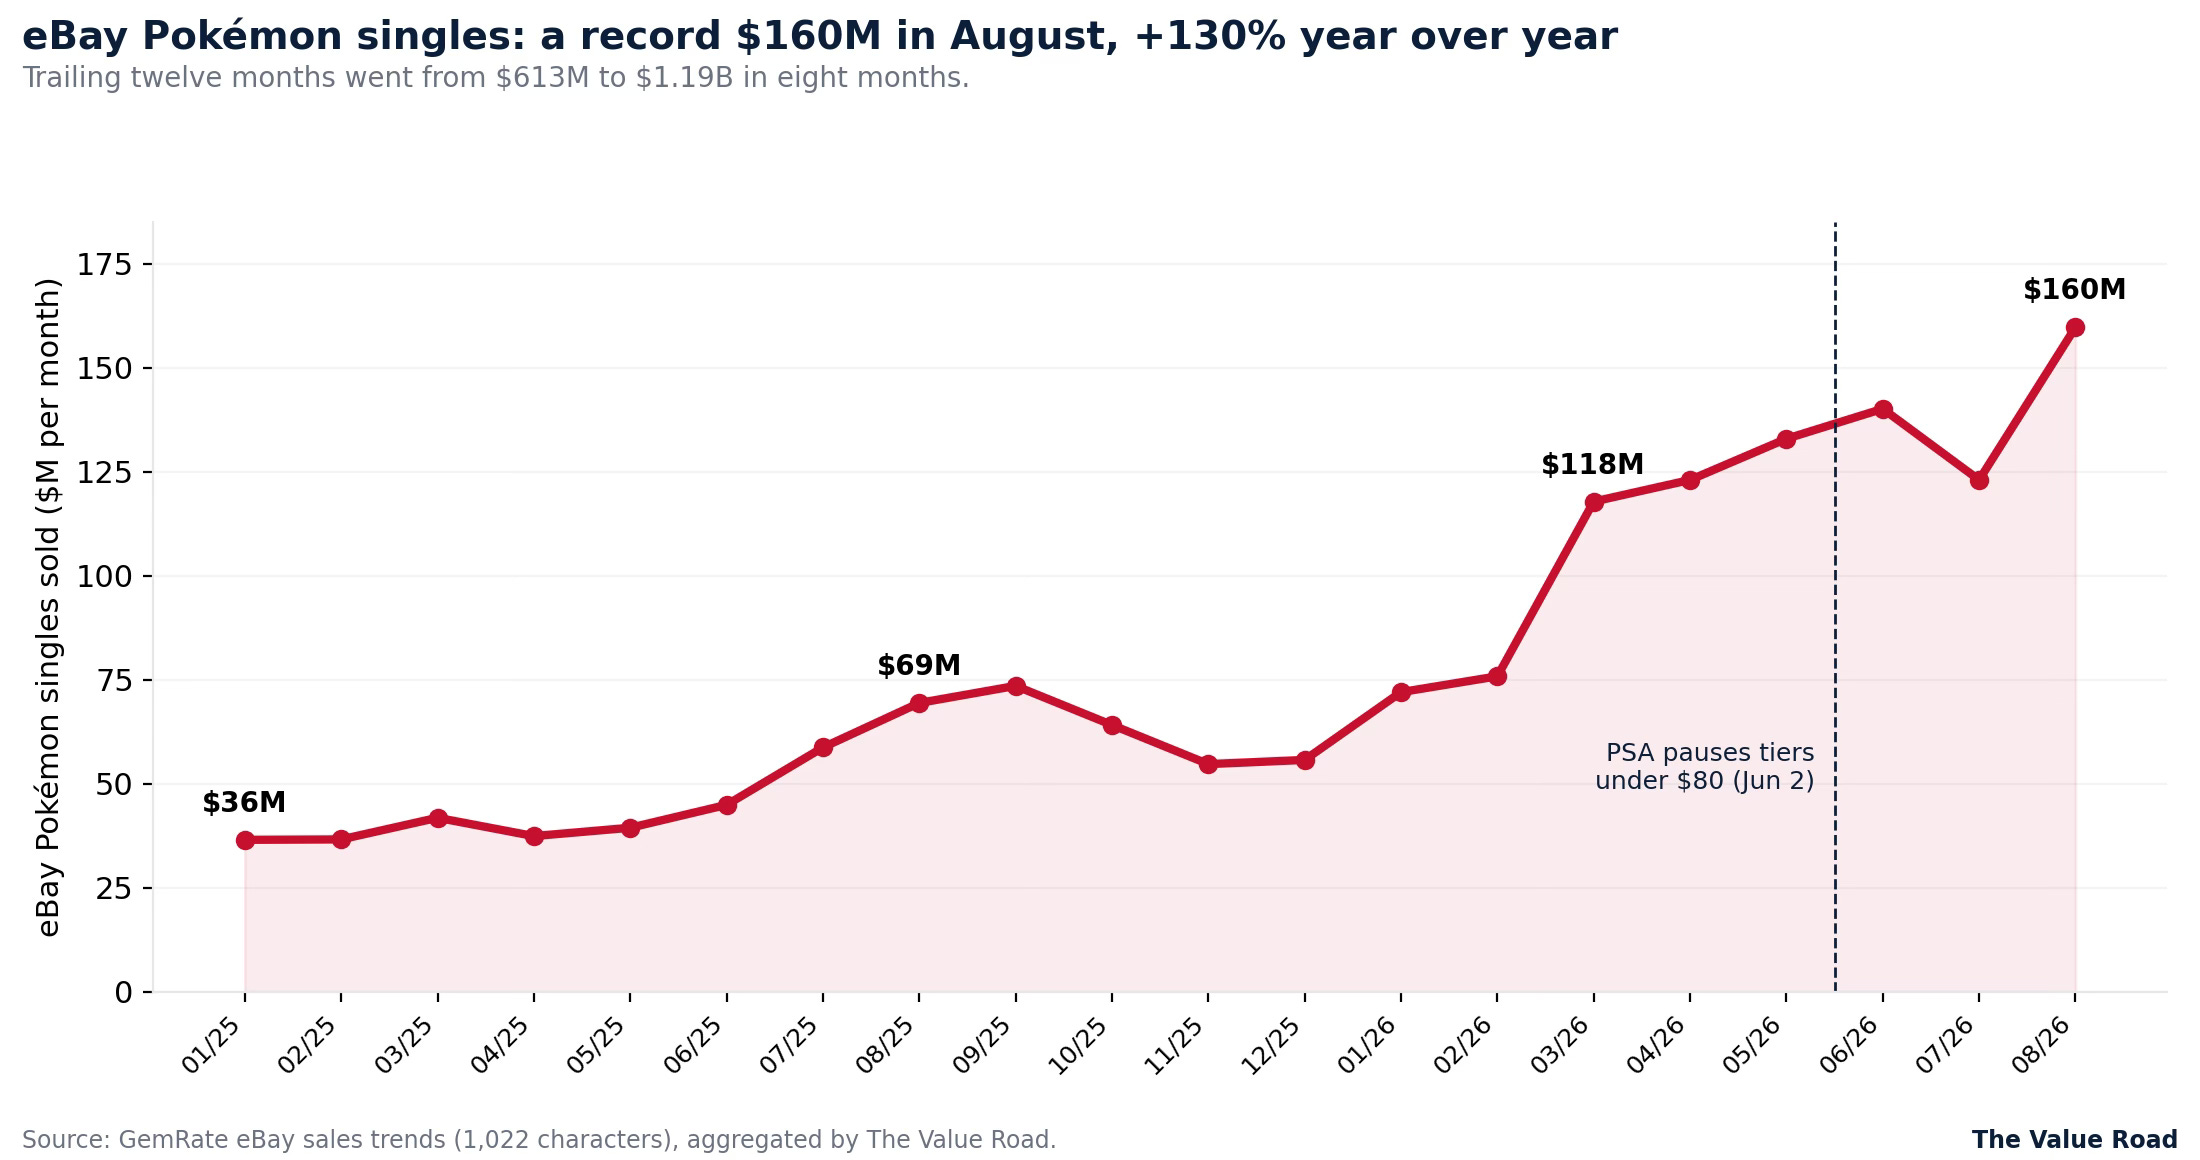
GameStop's collectibles mix rose to 45% of sales as gross margin reached 44%, supporting a deep-value case built on cash and store…
A2Gold’s first Taylor drill holes returned 20.96 g/t AuEq over 1.5m and 209.4 g/t silver over 10.7m, alongside 141.10 g/t gold at…
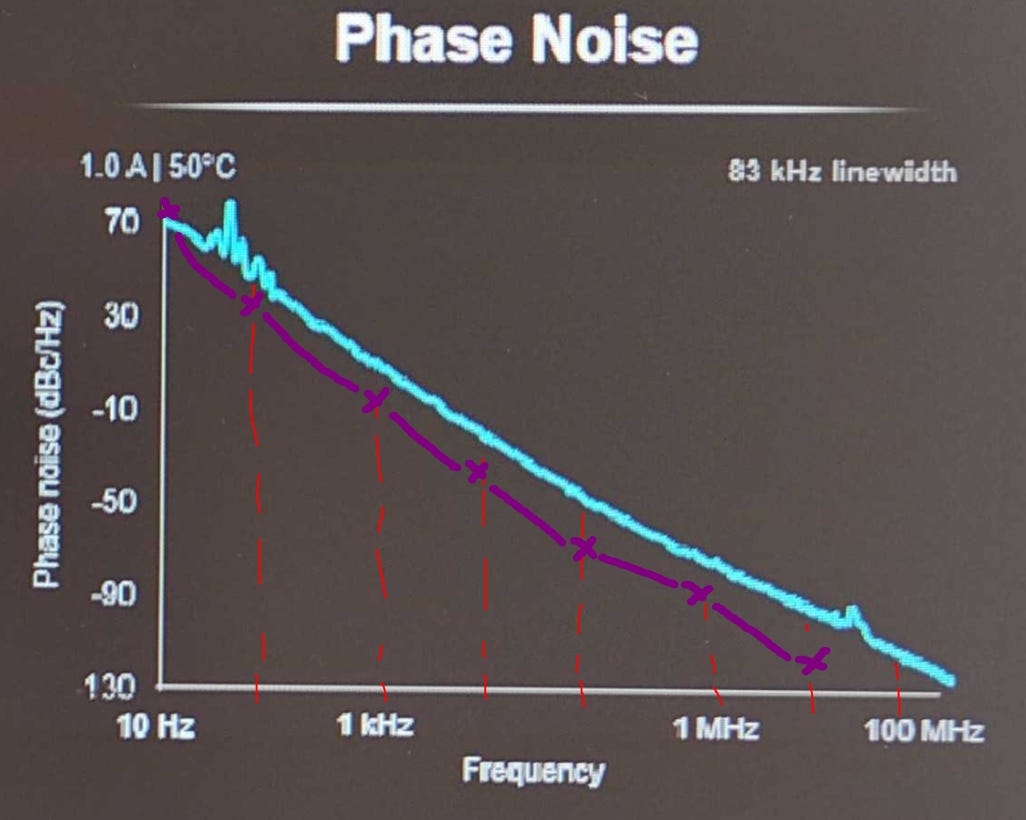
Coherent’s CPO/NPO laser misses 1 MHz effective-linewidth requirements, Irrational Analysis argues.
Pfizer offers a 6.22% yield at 9.3 times 2026 consensus EPS, backed by cost cuts and 5% operational growth in its non-COVID portfolio.
 Steven Fiorillo 1 click
CoStar spent more than $1 billion building Homes.com to challenge Zillow, betting seller-agent leads, proprietary listing content and…
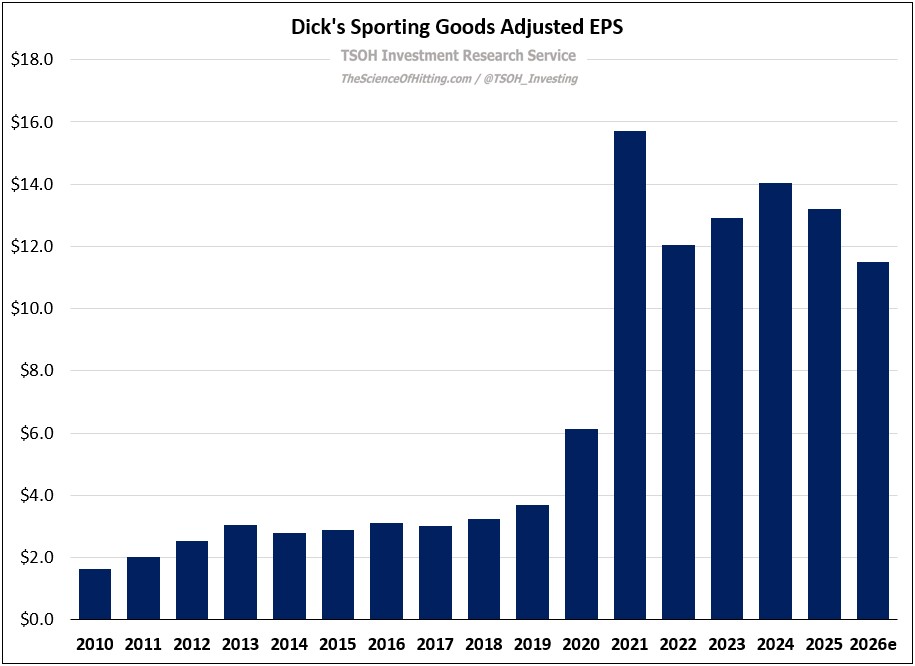
Dick’s Sporting Goods’ $2.4 billion Foot Locker acquisition nearly quadruples its store count and adds international exposure, risking a…
Goldman Sachs posted $20.98 in Q2 EPS on $20.3 billion of revenue and raised its dividend to $5 per share, with M&A and issuance activity…
 Mike Zaccardi, CFA, CMT 2 clicks
Latticework’s weekly briefing spotlights discounted European assets including Barco, Bolloré, Brookfield and D’Ieteren, with catalysts…
Brookfield Corporation, down 20% YTD, manages $1.27 trillion across asset management, insurance and operating businesses as rates, debt and…
 INVH · long
Invitation Homes owns more than 85,000 homes valued at $43 to $48 per share, versus a roughly $30 share price, with occupancy above 96%.

Palo Alto Networks posted 34% Q4 revenue growth to $3.41 billion, boosted by CyberArk and Chronosphere, while NGS ARR reached $9.1 billion…
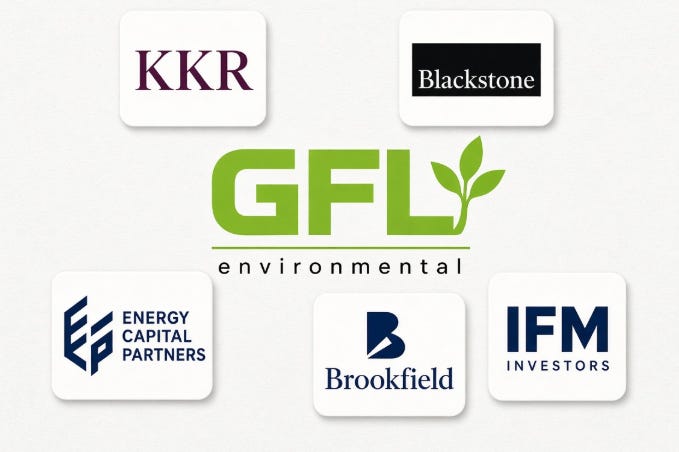
GFL’s take-private process has drawn KKR, Blackstone, Brookfield and IFM, while CEO Patrick Dovigi signals he will accept only the right…
Brookfield is recasting itself from an industrial owner into a $1.3 trillion asset manager and insurer, betting AI infrastructure can…

Steve Eisman argues AI extinction warnings from Dario Amodei and Sam Altman seek regulation that creates pricing moats.
Nintendo's Switch 2 attach rate, flat Switch Online accounts and rising memory costs fuel a bear case, while Spotify and Netflix margins…

DoorDash's grocery push targets a shift from weekly stock-up trips to frequent online fill-in orders, though smaller baskets complicate…
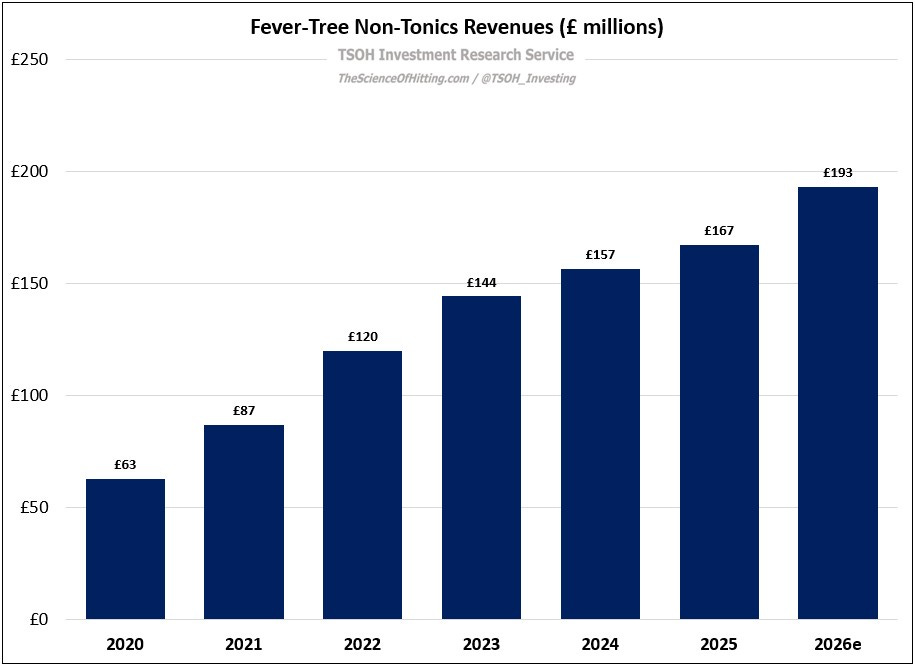
TSOH Weekly Roundup covers organized retail crime, Home Depot’s centralized operating missteps under Bob Nardelli, and research updates on…
Generac’s $2.4 billion Amazon generator agreement for 2027-28 anchors its data-center growth thesis, with 30% projected revenue growth in…
 Fernanda Galvez Jalil
Grab generates 53% of revenue from delivery, 36% from mobility and 10% from financial services, using its Southeast Asian marketplace to…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.