
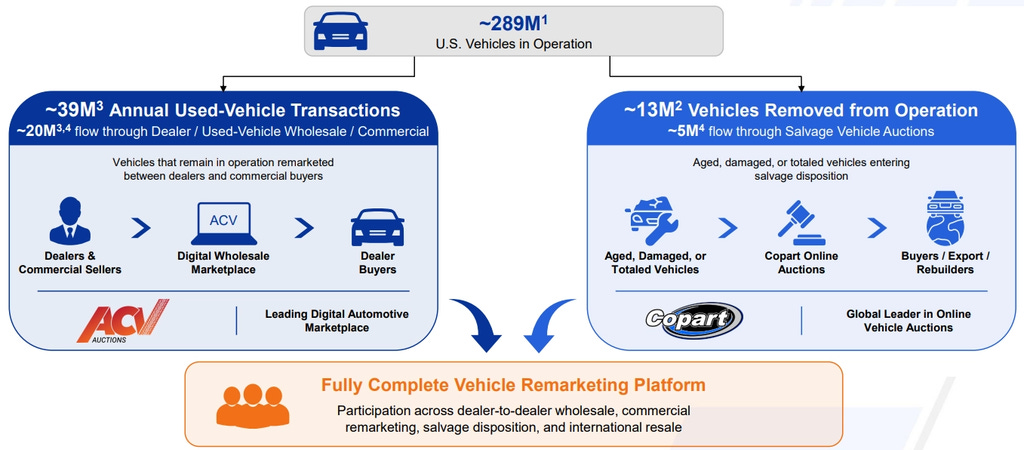
Copart 4Q26 Business Update: Thesis Shift?
Copart’s 4Q26 revenue grew 2.4% as U.S. insurance volumes fell 7.5%, while a customer loss and higher yard costs pressured profits despite international growth.
Copart’s 4Q26 revenue grew 2.4% as U.S. insurance volumes fell 7.5%, while a customer loss and higher yard costs pressured profits despite international growth.
$PLUS Numbers don’t add up. 50% sales $CSCO product (sales -13% MRQ, guided -11%). MRQ $PLUS sales +13% (reported yesterday). Earnings call question: “OEM Cisco have talked about bottlenecks, weak orders. You’ve been unscathed…how are you outperforming the market significantly?”
$EXLS Highly innovative founder-CEO rapidly taking share w AI-based services. High-teens topline growth w expanding margins, higher value-add mix to attractive end-markets. 17x P/E yet to reflect business transformation. 100% FCF to buybacks. Winning customers from $ACN $DXC $WIT
8/ There is a lot more to talk about (24% sequential increase in new home sales, ward village condo sales etc.) but I am hungry. So to wrap up, if you're selling $HHH on this quarterly report you do not understand what you own and I will be buying your shares at tomorrow's open.
1/ So first things first, $HHH missed on top and bottom line. Am I concerned? Absolutely not. Value was created for shareholders and I'll briefly explain why...
$OII Niche leader in subsea robotics at 12x P/E. Offshore rig count accelerating (70% share), A&D growing DD, new autonomous tech a major growth driver in other end markets (lifts, etc). Investor day next week will showcase products and new LT targets. >50% NTM upside, IMO.
@TheMuffinMan28 SRS is a PE rollout, bit of a hodgepodge of assets. Concentration in landscaping, pool and roofing. No exclusive relationships (GMS is for $AWI, regional duopoly across most categories). End customers are small homebuilders (more competitive, less scale benefit for distributors).
$GMS Underfollowed building products distributor, HSD growth, favorable mix shift/ margin, tracking to beat estimates, trading at 10x EPS, 7x EBITDA. Peers at >50% higher multiples. $HD just acquired lower quality peer SRS for 17x EBITDA. GMS = $240 or +150% at that multiple.
$LYTS Very attractive acq of EMI following successful prior M&A blueprint--significant cross-selling op, cost reduction, expands product set which further solidifies dominant national position. Seeing +50% upside to shares from here.
Dassault Aviation reported 46% first-half sales growth and a €45.4 billion backlog, with Rafale F5 demand offsetting Falcon 10X delays and…
 Dhierin Bechai 1 click
Adobe’s fiscal 3Q26 revenue grew 13%, while ARR growth slowed to 9.3% excluding Semrush.
Amazon’s refrigerated same-day network has lifted monthly perishable customers roughly 50%, using grocery frequency to deepen loyalty and…
Cestrian initiated Joby Aviation at Accumulate and upgraded Applied Materials and Broadcom to Accumulate for the week ended 11 September…

Oracle’s $88.3 billion net debt and $90-95 billion capex plan pushed five-year CDS to 215 bps, despite 121% OCI growth and a $664 billion…
MKS Instruments posted $1.25 billion in Q2 revenue and is expanding Penang capacity for a $200 billion to $250 billion wafer-fab-equipment…
 The Straits Strategist

Adobe’s fiscal 3Q26 revenue grew 13%, while ARR growth was about 9.3% excluding Semrush.
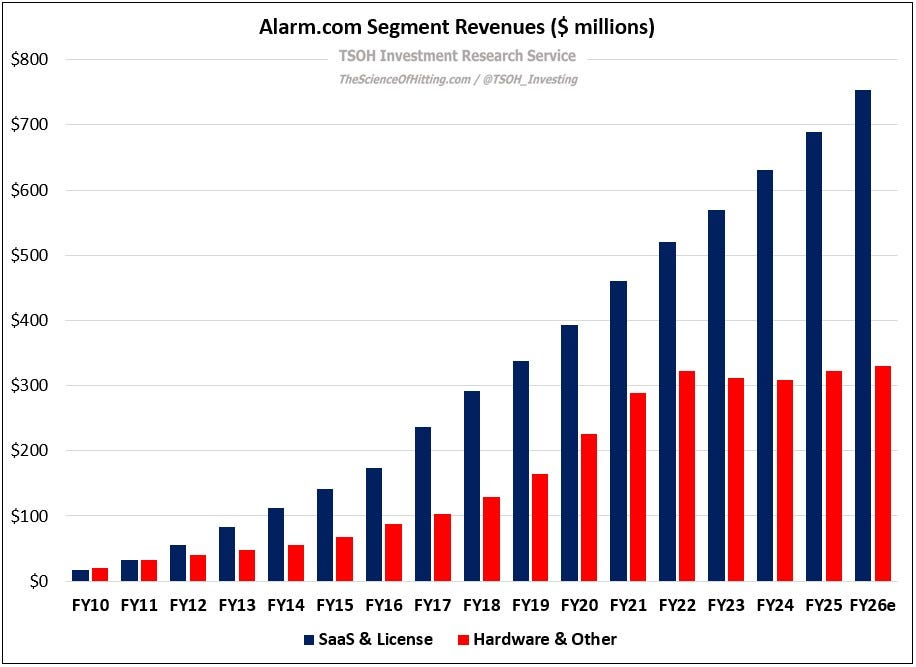
Alarm.com, founded after CEO Steve Trundle’s bad home-security experience, has fallen from $105 in 2020 to about $55, testing whether…
CHPY pairs a roughly 40% distribution rate with capped weekly upside for investors retaining semiconductor exposure amid Anthropic's AI…
 Geneva Investor 1 click
Zentek initiation report.
 GTLB · long
CVD Equipment is winding down manufacturing, cutting half its staff and weighing liquidation, with $23.5 million of cash and a…
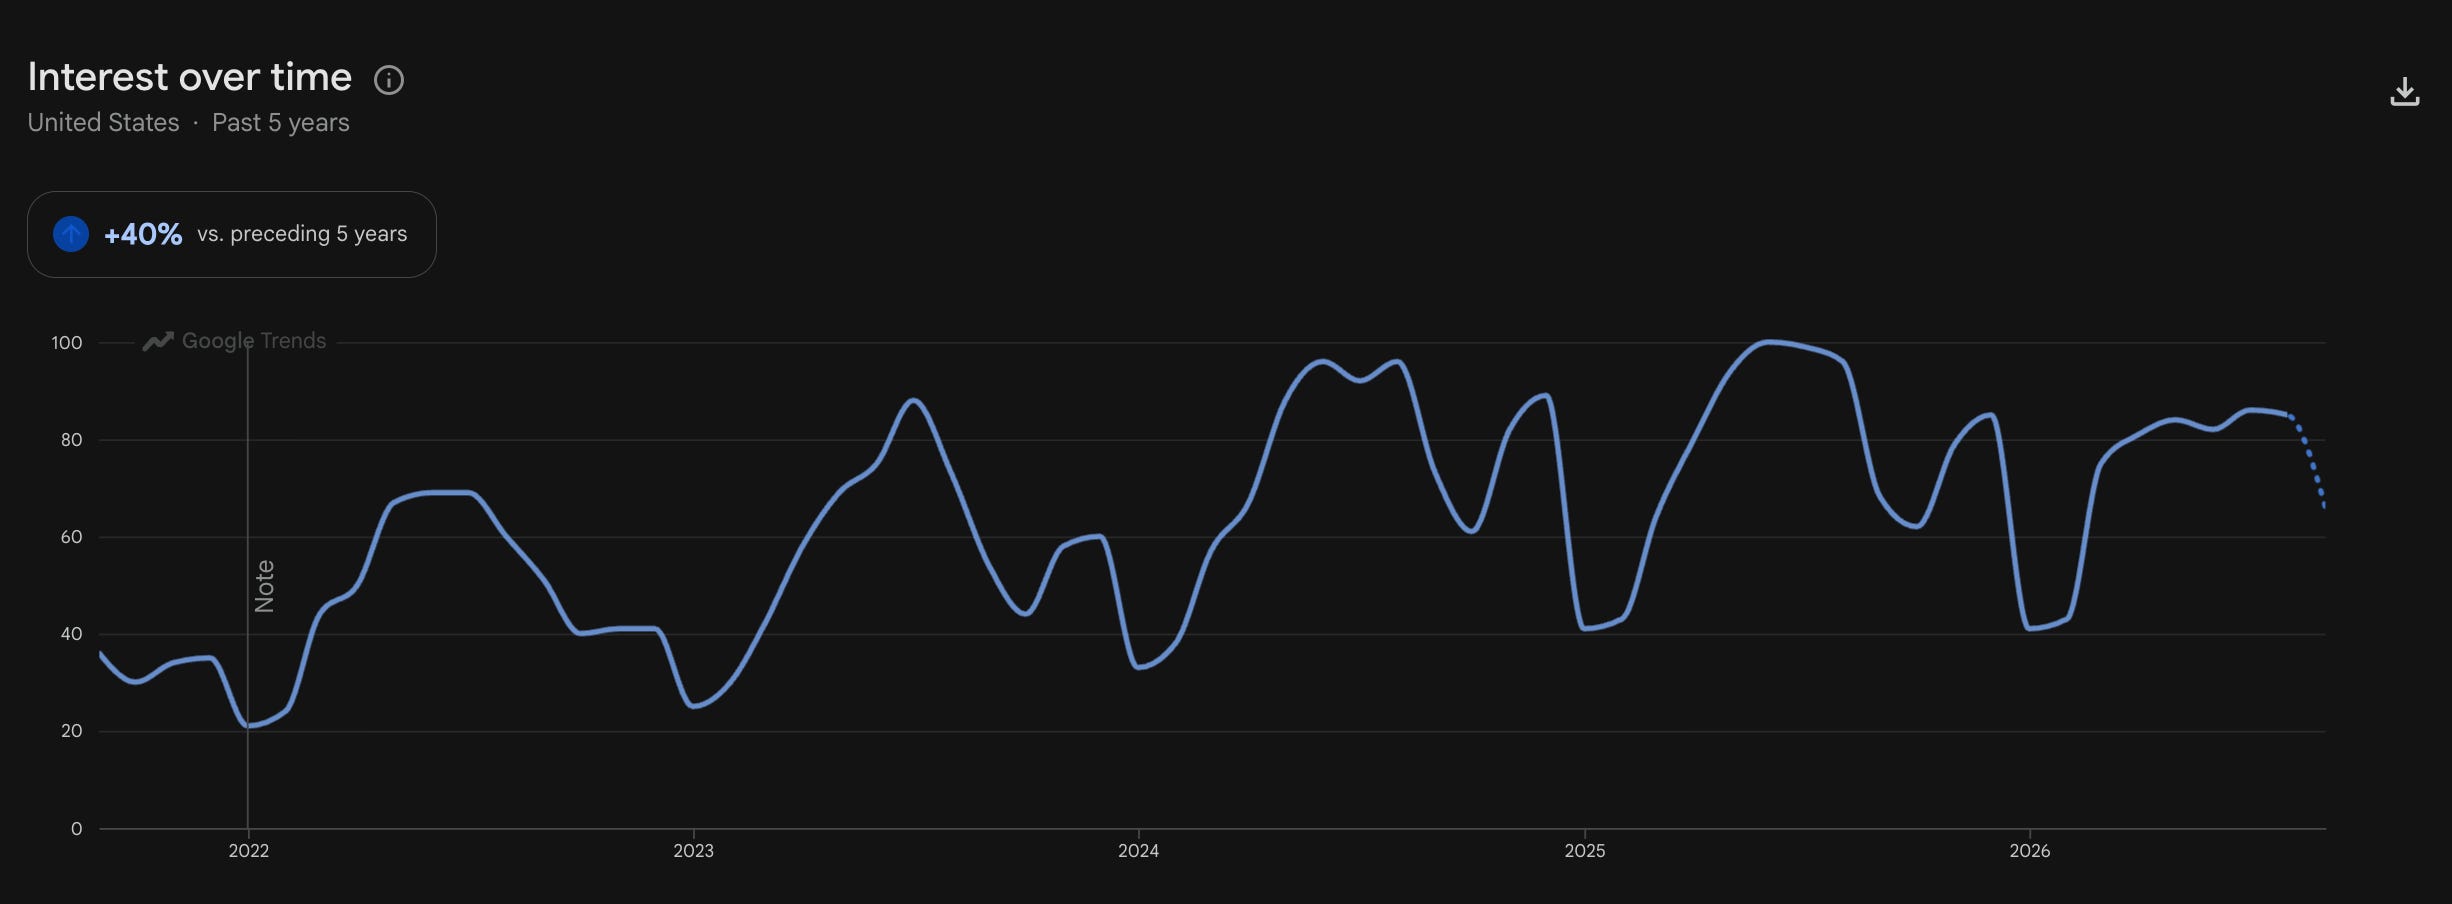
Genius Sports aims to turn official sports data into AI-driven, real-time advertising, with media and ads already about 40% of revenue.
Booking Holdings trades at 19x earnings, its lowest since 2022, after a 20% annual decline, with the thesis resting on durable online…
Oak Bloke’s 2026 picks have returned 37% in GBP, with AltynGold, Geiger Counter, Silvercorp and China-focused trusts still rated buys…
Nintendo expects software, digital sales and character licensing to drive growth, with FY2027 revenue forecast at ¥2.05 trillion and…
 LL Insights

Ten-year Treasury yields breach 4.9% as Steve Eisman discusses AI fears, OpenAI's price cut, Oracle's 30% revenue growth and Tesla's…

USA Compression targets nearly 30% full-year EBITDA growth as JW Power synergies, telemetry and maintenance reduce costs; its units yield…
 Ron Ferrie 3 clicks
Lululemon’s North American sales, margins and legging demand are falling as Alo and Vuori gain share, leaving its brand moat and depressed…
Chevron’s 2027 EPS could be underestimated by about $4.50 per share if U.S.-Iran conflict keeps oil near $100 rather than forecast $74 to…
 Envision Research 1 click
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.