No Cap? Currently Capped by Three Hundredths of a Percent: Medtronic’s MiniMed Split-Off Odd Lot
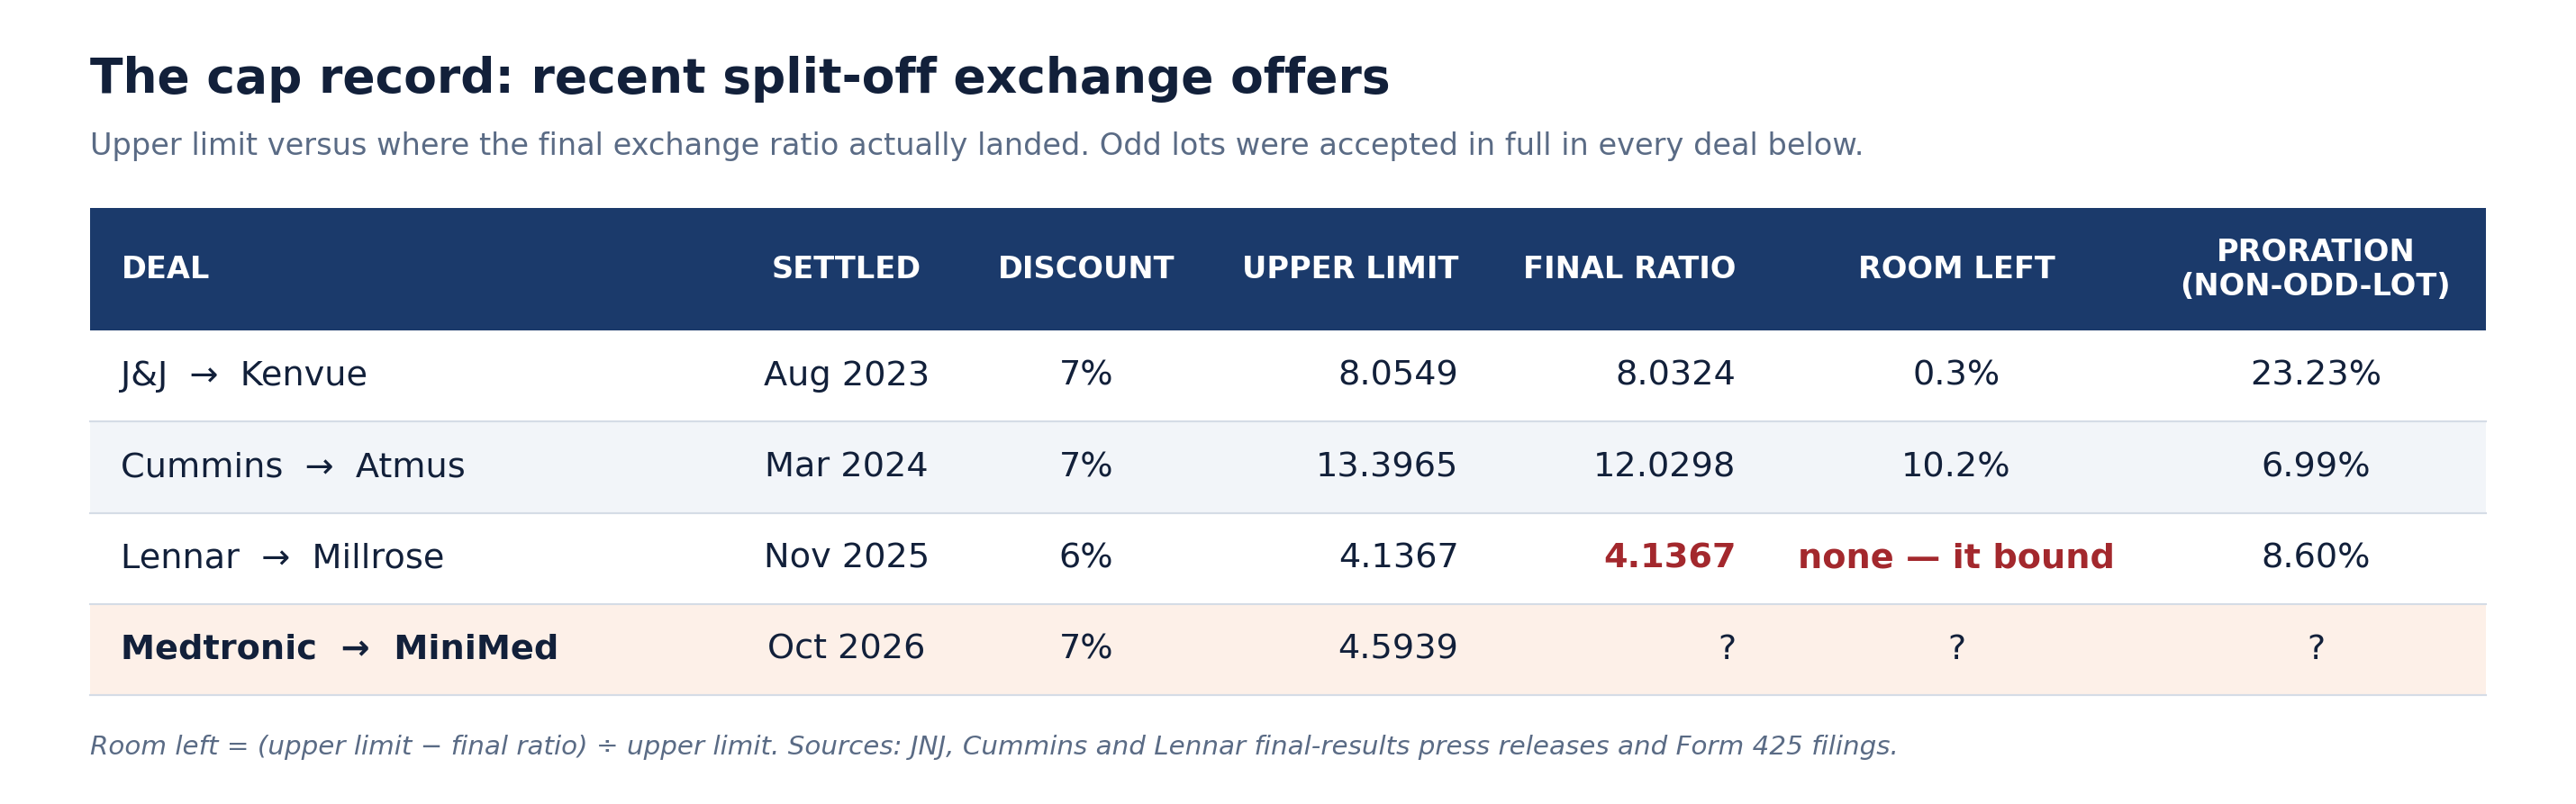
Medtronic’s MiniMed split-off gives odd-lot MDT holders priority on a 7% discounted exchange, but a 4.5939-share cap has begun reducing the payoff.
Medtronic’s MiniMed split-off gives odd-lot MDT holders priority on a 7% discounted exchange, but a 4.5939-share cap has begun reducing the payoff.
$ACA Levered roll-up (4x levered) hodgepodge of low-quality cap intensive commodity businesses w struggling end-markets (sub-scale aggregates, building products, ag). Negative organic growth w unrealistic guidance. Forced to sell an asset to avoid covenant breach. 30x P/E
$DAKT Just won the massive jumbotron project for the new Titans stadium. Estimated to be $180M. Will be the largest set of displays in the NFL. Bills, Browns stadiums to be announced soon. Wouldn’t be surprised if Mitsubishi acquires them given interest in the category.
With contract disputes and litigation set to surge, I believe Burford is well positioned to benefit. Struggling firms will increasingly look to shore up capital—Many cannot afford to wait 2+ years to see the case through. $BUR
Burford’s value prop is high to these firms, and the significant supply spike puts them in a fantastic position to capitalize on the demand for cash. Additionally settlement with Argentine government seems highly likely at this point. Long $BUR
$NX 5% of COGS/ direct input costs sourced from China. Tariffs + zero pricing power, high fixed cost structure + only 30% GMs = 25-30% hit to EBIT. Add 4x leverage, declining volumes, ambitious mgmt guidance while integrating a large acquisition is a setup for a trainwreck.
$AVO calling out the fact that they have been overearning and margins reverting. “experienced normalization of our per unit avocado margins during in Q1.” Noted weak harvest anticipated in Mexcico. $CVGW will be even more adversely impacted by these factors.
$DAKT CEO departing, new high-quality CFO (temp) w very attractive secular tailwinds in digital display demand + activist involvement = increased likelihood of takeout. Optimal business for PE. Multiple logical strategics. +75% upside.
$FTDR Vol declining (existing home sales=driver). Pricing lagging inflation, massively over-earning. Problematic given 25% churn w aggressive new entrants. Dubious company overall. Investor day yesterday was comical, compared themselves to $NFLX. Earnings misses coming.
Barnes & Noble Education is shifting from campus bookstore retail toward recurring-revenue infrastructure for inclusive-access course…
 Given Mahlangu 2 clicks
Zentek initiation report.
Genius Sports aims to turn official sports data into AI-driven, real-time advertising, with media and ads already about 40% of revenue.
Oak Bloke’s 2026 picks have returned 37% in GBP, with AltynGold, Geiger Counter, Silvercorp and China-focused trusts still rated buys…

USA Compression targets nearly 30% full-year EBITDA growth as JW Power synergies, telemetry and maintenance reduce costs; its units yield…
 Ron Ferrie 3 clicks

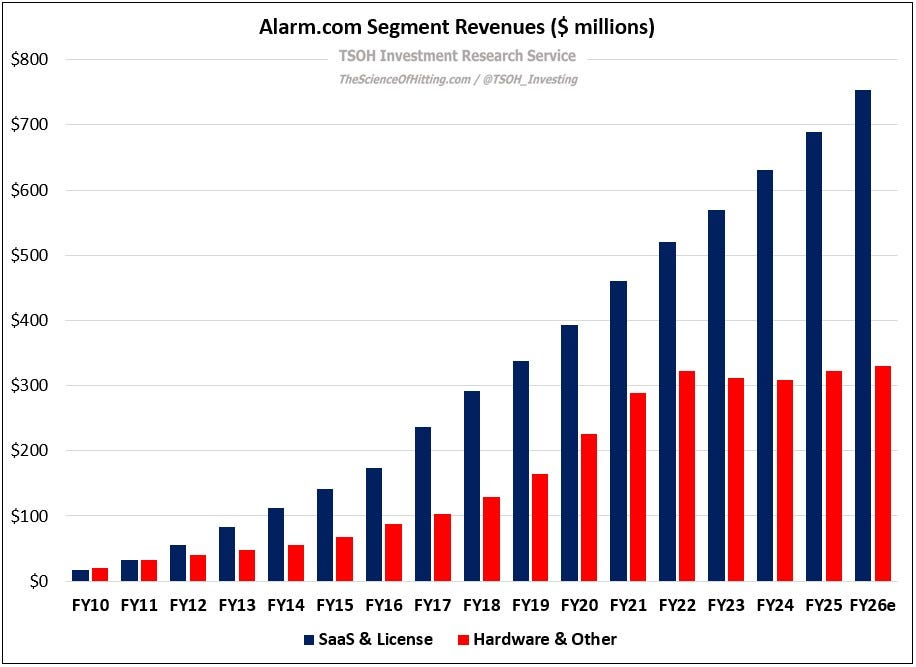
TSOH weekly roundup covers Meta’s child-safety settlement, Markel’s leadership transition, Peloton’s gym strategy and an upcoming Alarm.com…
NET Power’s $1.80 shares are paired with January $2 covered calls for 40 cents as the company pivots from carbon capture to Permian…

Tsakos Energy Navigation benefits from higher oil prices and stronger tanker sentiment, but faces long-term demand destruction and…
 Long Player

Joby Aviation is initiated at Accumulate after booking $116m of trailing revenue, forming a Toyota manufacturing venture and agreeing to…

Sofwave Medical grew Q2 revenue 43% as recurring usage fees reached 46% of sales for its non-invasive ultrasound skin-tightening devices.
 SLVM · long
Sylvamo, a $1.6 billion uncoated freesheet paper producer, has fallen about 60% from its November 2024 high above $95 to roughly $40.
Priority Technology’s chairman offered $6.00 to $6.15 a share to take PRTH private, while Zack Buckley argues Treasury Solutions and…

Imperial Petroleum's record Q2 cash generation, major share repurchases and a $32 million Suezmax sale gain set up another record quarter.
 Henrik Alex 3 clicks

Amplitude reported Q2 revenue of $100.9 million, up 21%, as agentic AI and LLM vendors challenge the moat of its product analytics software.
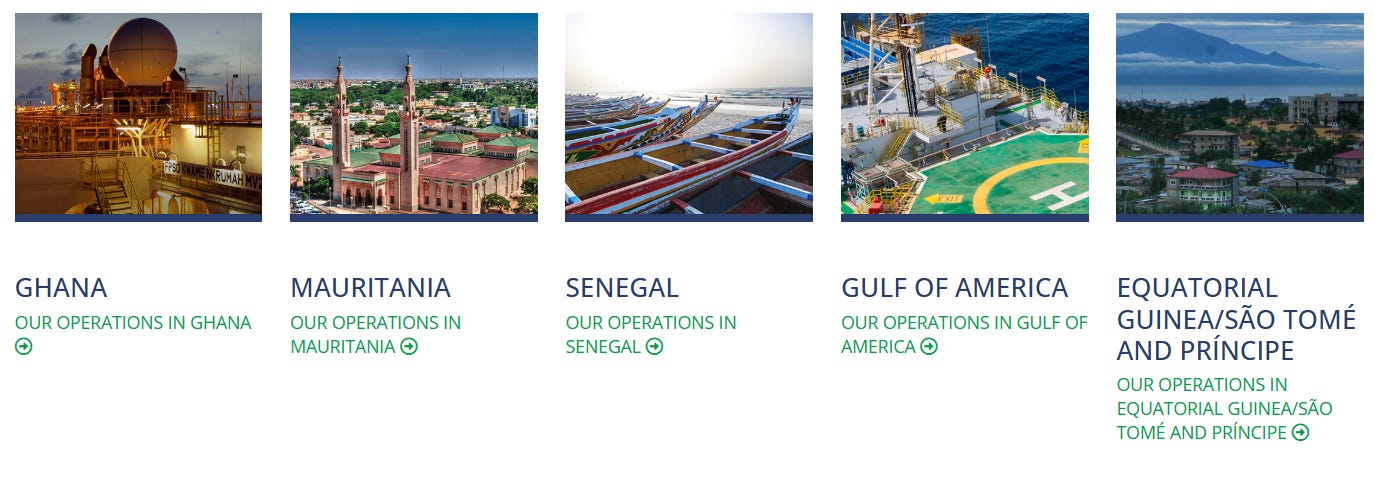
Kosmos Energy (KOS) is pitched as an oil stock poised to outperform if oil stays above $70-$80, supported by a claimed 2 billion-barrel…
ContextLogic will acquire specialty-solvent maker gChem for $850 million, funded by a $650 million rights offering and $250 million of…
Kodiak AI’s stock collapse coincides with a planned year-end long-haul driverless launch, while cash burn, customer concentration and…
 High Alpha Professor 1 click
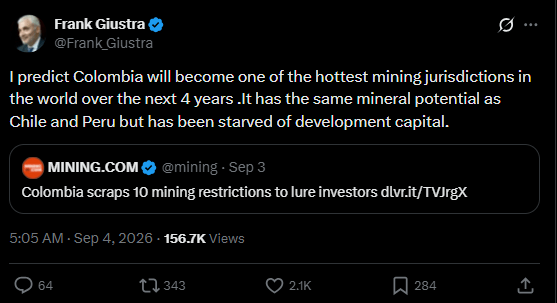
Tecnoglass could recover tariff- and FX-hit margins as U.S. blanket tariffs on Colombian goods lift.
Scholar Rock’s apitegromab could become the first muscle-targeted SMA therapy by September 2026, but manufacturing setbacks and a…
 Equity Eagle
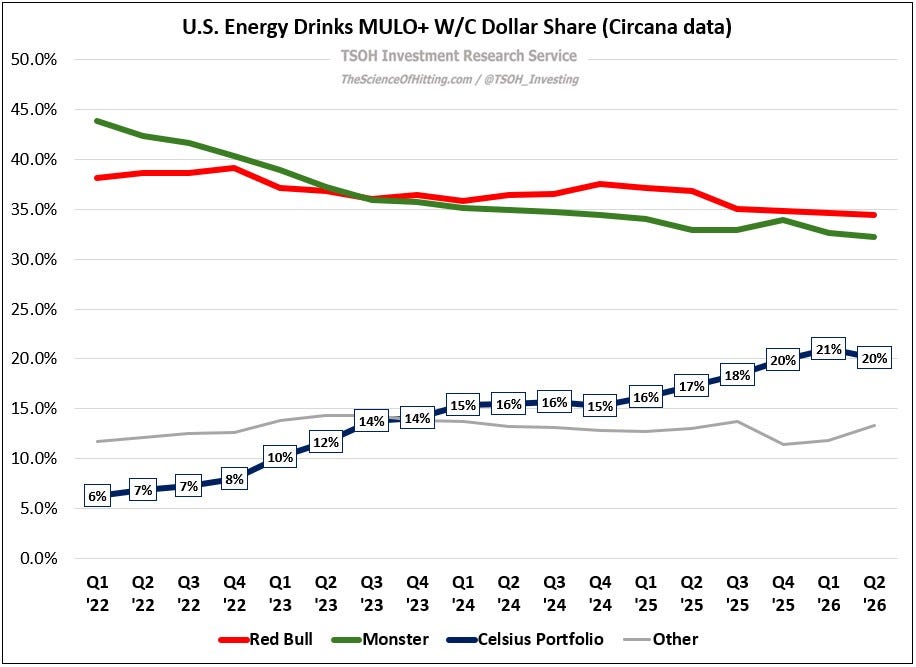
Celsius holds 20% of the U.S. energy-drink market and 40% of sugar-free sales, but its $1.65 billion Alani acquisition complicates…
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai Equity Eagle
 Eudaemon Research Henrik Alex High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.