Atlas Engineered Products ($AEP.V) FINS Review
Atlas Engineered Products reported Q2 revenue up 19% to $16.2 million, but ended cashless on its credit line as inventory rose 47% and year-to-date losses widened.
Atlas Engineered Products reported Q2 revenue up 19% to $16.2 million, but ended cashless on its credit line as inventory rose 47% and year-to-date losses widened.
Answer: aggressive revenue booking, financing sales, selling products at/ below cost to boost revenue and hoping to “then try to build it back up over time” per CEO. Contrast $PLUS performance w competitor and industry leader $CDW.
$PLUS Numbers don’t add up. 50% sales $CSCO product (sales -13% MRQ, guided -11%). MRQ $PLUS sales +13% (reported yesterday). Earnings call question: “OEM Cisco have talked about bottlenecks, weak orders. You’ve been unscathed…how are you outperforming the market significantly?”
$EXLS Highly innovative founder-CEO rapidly taking share w AI-based services. High-teens topline growth w expanding margins, higher value-add mix to attractive end-markets. 17x P/E yet to reflect business transformation. 100% FCF to buybacks. Winning customers from $ACN $DXC $WIT
8/ There is a lot more to talk about (24% sequential increase in new home sales, ward village condo sales etc.) but I am hungry. So to wrap up, if you're selling $HHH on this quarterly report you do not understand what you own and I will be buying your shares at tomorrow's open.
1/ So first things first, $HHH missed on top and bottom line. Am I concerned? Absolutely not. Value was created for shareholders and I'll briefly explain why...
$OII Niche leader in subsea robotics at 12x P/E. Offshore rig count accelerating (70% share), A&D growing DD, new autonomous tech a major growth driver in other end markets (lifts, etc). Investor day next week will showcase products and new LT targets. >50% NTM upside, IMO.
@TheMuffinMan28 SRS is a PE rollout, bit of a hodgepodge of assets. Concentration in landscaping, pool and roofing. No exclusive relationships (GMS is for $AWI, regional duopoly across most categories). End customers are small homebuilders (more competitive, less scale benefit for distributors).
$LYTS Very attractive acq of EMI following successful prior M&A blueprint--significant cross-selling op, cost reduction, expands product set which further solidifies dominant national position. Seeing +50% upside to shares from here.
Airbnb Experiences faces a supply bottleneck from manual approvals, while a farm host raised her price from $15 to $25 after stronger…
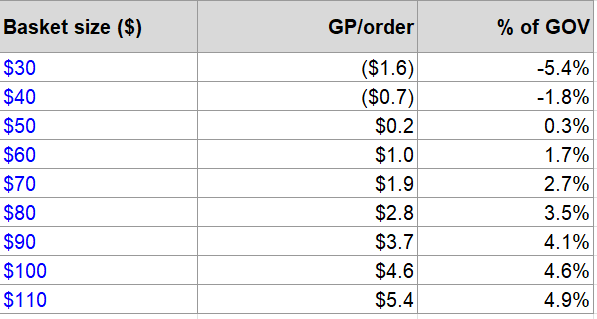
Instacart’s larger grocery baskets create disproportionately better delivery economics than DoorDash’s, making half the basket size worth…

El Al trades near 2x EBITDA after wartime near-monopoly profits, with $1.3 billion of net cash and owned aircraft weighed against…
 PTLO 2026-08-20
Portillo's guidance cut followed a 1.2% same-restaurant-sales decline and 1.9% margin compression, while its $343 million TRA liability…
 KC Research 2 clicks
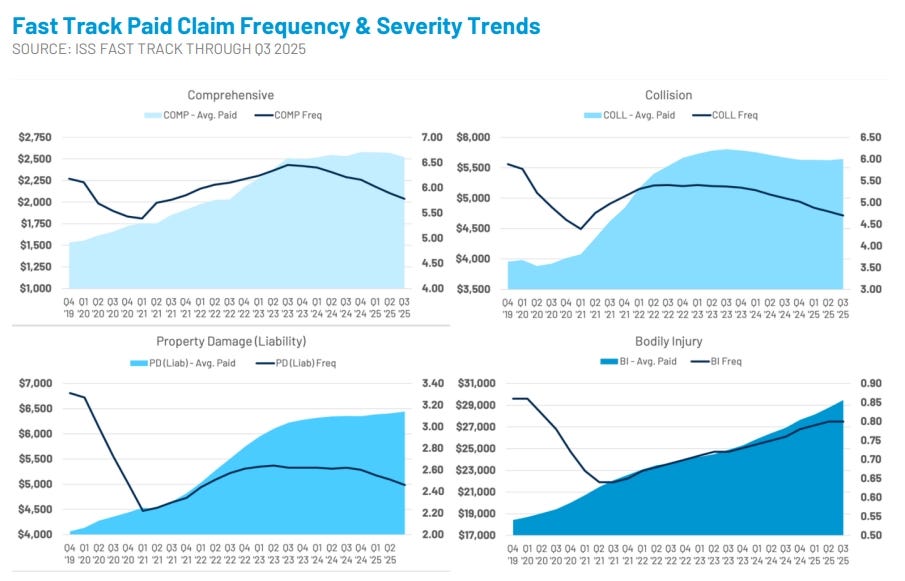
CCC, the dominant auto physical-damage claims estimator, connects 27 of the top 30 insurers with 31,000 repair shops as takeout rumors…
Verra Mobility's new seven-year Avis agreement replaces a customer worth over 10% of revenue on materially worse economics, exposing…
SA 2026-08-20 Seabridge Gold's KSM gold-copper project could re-rate on a joint venture, 2027 feasibility study and infrastructure progress, with gold…
 Redfern Research
Norwegian Cruise Line’s $15 billion debt and 2026-27 capex delay deleveraging, despite fuel-efficient new ships and stronger projected 2028…
PGY 2026-08-19 Pagaya Technologies reported Q2 2026 network volume of $3.54 billion, 19% revenue growth and 99% adjusted net-income growth, while trading…
 Akim Guerreiro
Jumia’s January 2028 $7/$15 call spread risks $1.15 for up to $6.85 if cost cuts and marketplace growth deliver adjusted EBITDA and…
 OFRM · long
Once Upon a Farm (OFRM) makes organic baby food, smoothies and kid snacks using high-pressure processing instead of heat pasteurization.
NRIX 2026-08-24 Nurix Therapeutics gained $700 million upfront from Roche, a 50% U.S. profit share and Roche-funded global bexobrutideg development,…
 Equity Eagle 3 clicks
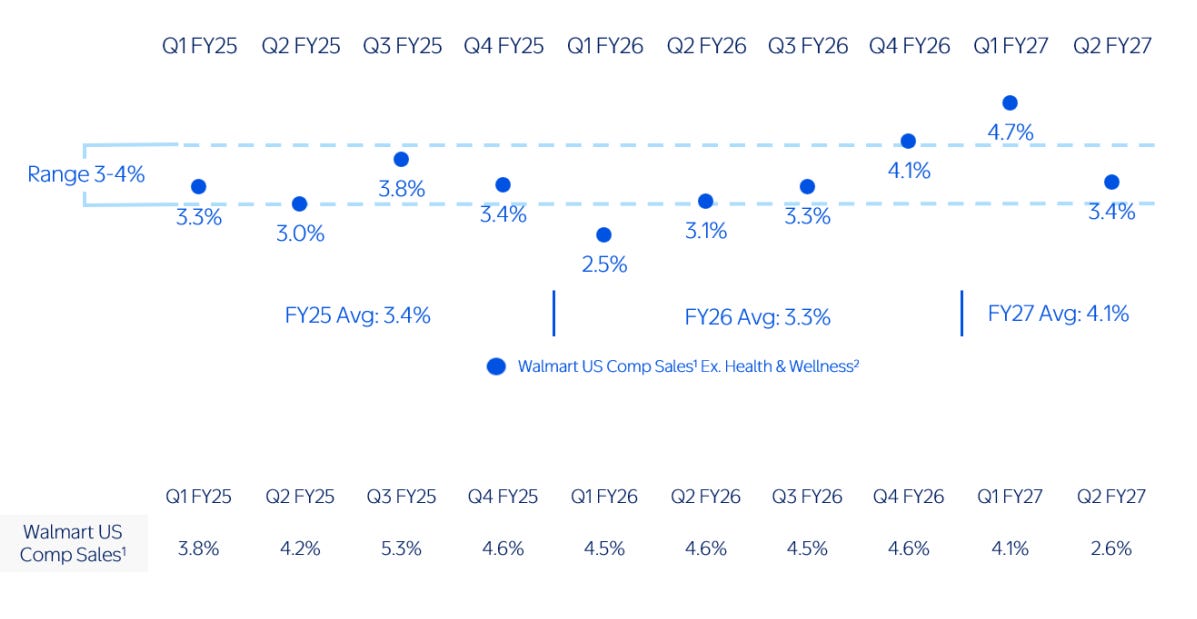
Walmart says Medicare Maximum Fair Price rules will cut FY27 US comps by 125 basis points, while pharmacy margins and prescription volumes…
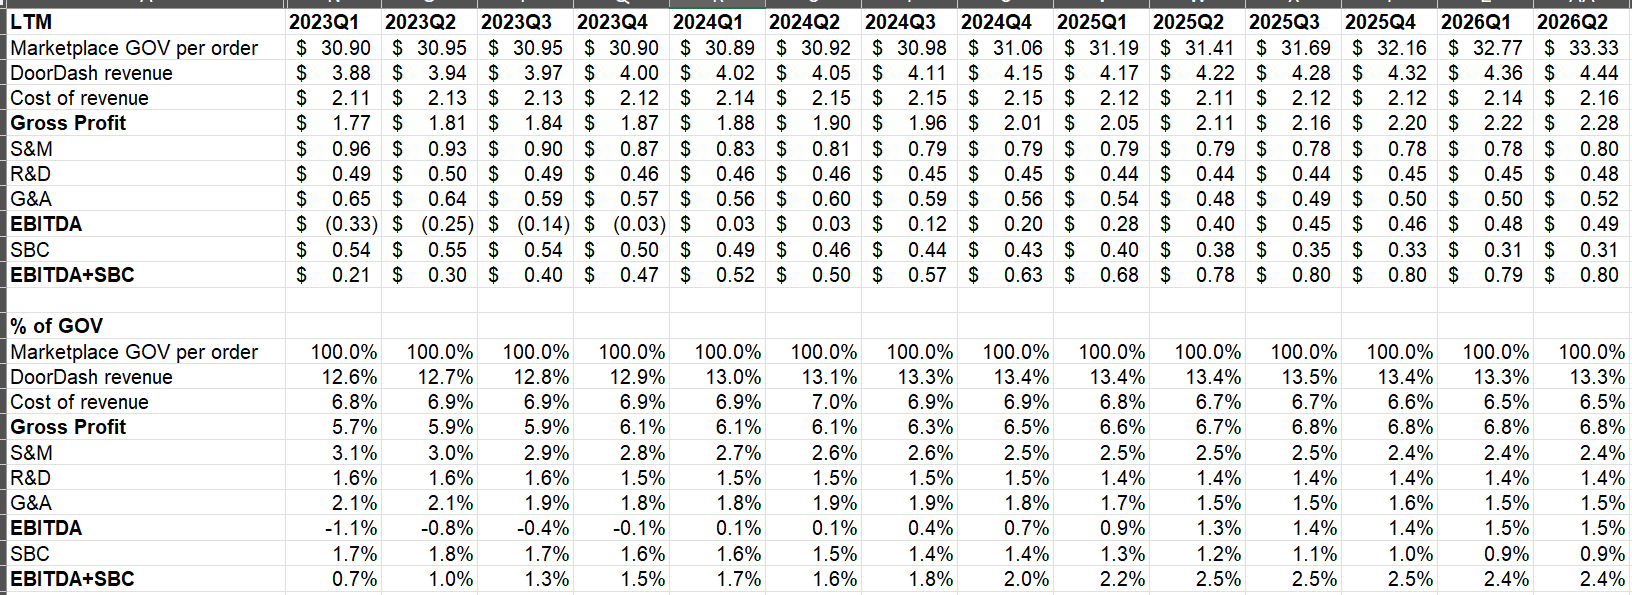
Instacart’s per-order unit economics provide a benchmark for assessing DoorDash’s LTM profitability and operating model.
NBIS 2026-08-20 Nebius posted 454% revenue growth and a 41% EBITDA margin, while Meta’s $27 billion agreement supports its AI infrastructure backlog.
 The Quality Growth Investor 1 click
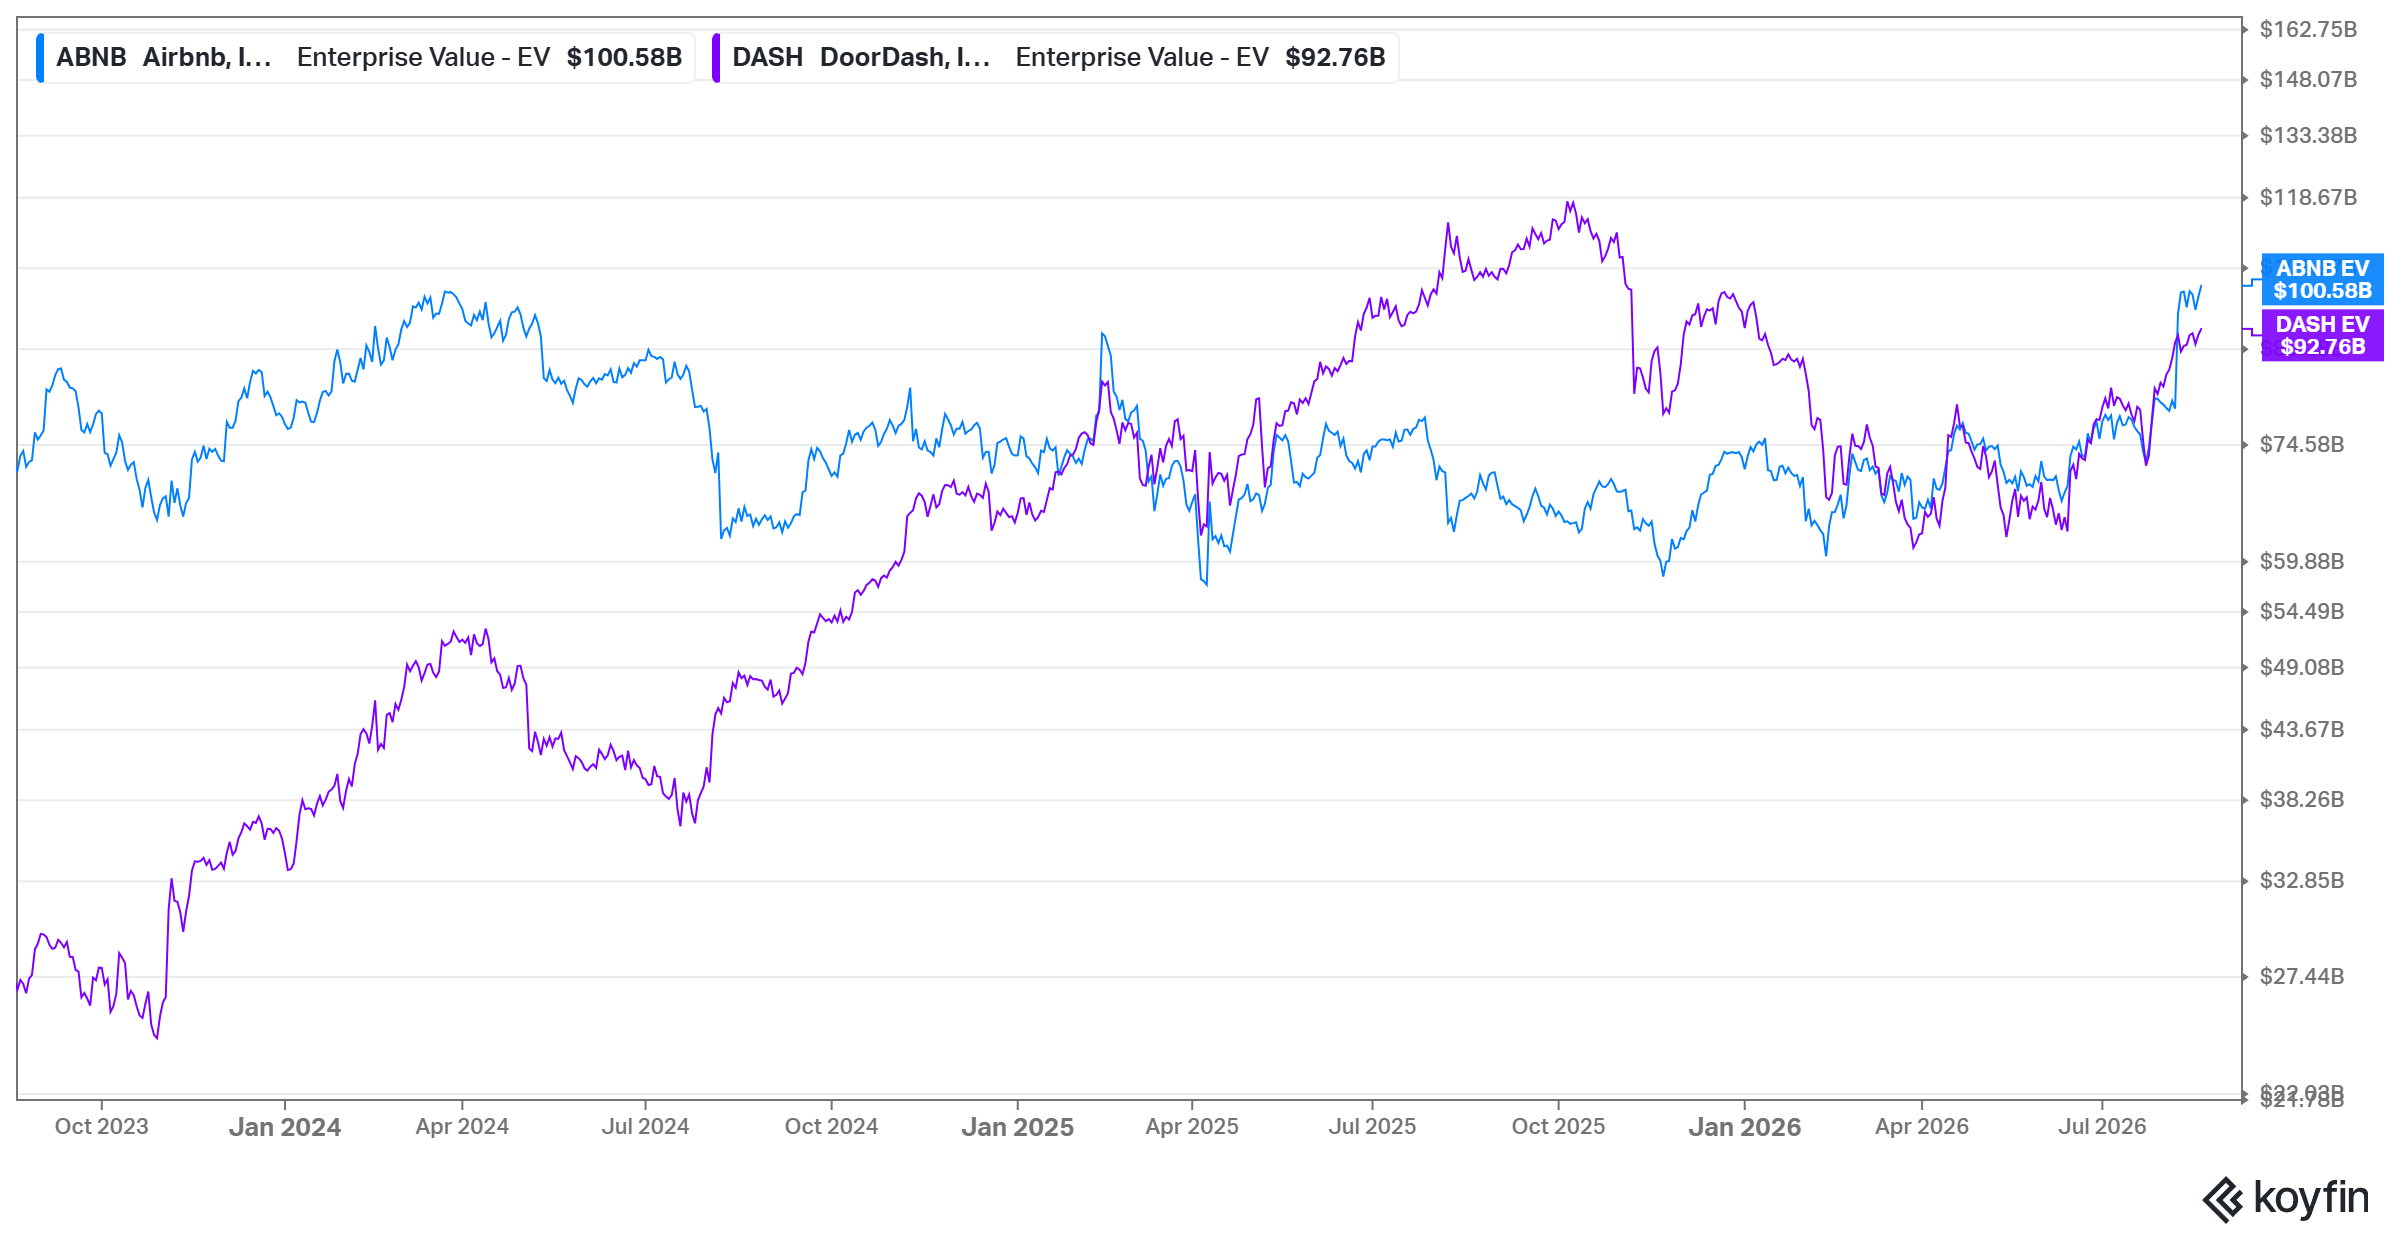
Airbnb shares have risen about 50% since October 2025, prompting a revised 2026 model and return assumptions at the current price.
CRWV 2026-08-19 CoreWeave’s Q2 converted backlog into sales, expanded margins and lifted operating leverage as active contracts topped half of its $104.2…
 Future Stack Investment

IREN awarded each co-CEO roughly 9 million RSUs, about 2.5% of shares and $400 million, in exchange for no further equity grants until…

Nubank's 140 million customers, 20% efficiency ratio and 30% ROE frame whether its high-teens P/E reflects a scalable fintech or a maturing…
E.W. Scripps, Team Internet, Monro, doValue and Inter & Co feature as special-situation trades involving mergers, asset sales, leverage and…
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai Equity Eagle
 Eudaemon Research
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.