Jumia
Jumia’s January 2028 $7/$15 call spread risks $1.15 for up to $6.85 if cost cuts and marketplace growth deliver adjusted EBITDA and cash-flow breakeven in Q4 2026.
Jumia’s January 2028 $7/$15 call spread risks $1.15 for up to $6.85 if cost cuts and marketplace growth deliver adjusted EBITDA and cash-flow breakeven in Q4 2026.
Meanwhile disintermediation by OEMs going direct is accelerating. See recent commentary from partners $CSCO, $PANW $DELL, etc. $PLUS has zero discernable benefit from $NVDA and AI.
Answer: aggressive revenue booking, financing sales, selling products at/ below cost to boost revenue and hoping to “then try to build it back up over time” per CEO. Contrast $PLUS performance w competitor and industry leader $CDW.
$PLUS Numbers don’t add up. 50% sales $CSCO product (sales -13% MRQ, guided -11%). MRQ $PLUS sales +13% (reported yesterday). Earnings call question: “OEM Cisco have talked about bottlenecks, weak orders. You’ve been unscathed…how are you outperforming the market significantly?”
$EXLS Highly innovative founder-CEO rapidly taking share w AI-based services. High-teens topline growth w expanding margins, higher value-add mix to attractive end-markets. 17x P/E yet to reflect business transformation. 100% FCF to buybacks. Winning customers from $ACN $DXC $WIT
$OII Niche leader in subsea robotics at 12x P/E. Offshore rig count accelerating (70% share), A&D growing DD, new autonomous tech a major growth driver in other end markets (lifts, etc). Investor day next week will showcase products and new LT targets. >50% NTM upside, IMO.
@TheMuffinMan28 SRS is a PE rollout, bit of a hodgepodge of assets. Concentration in landscaping, pool and roofing. No exclusive relationships (GMS is for $AWI, regional duopoly across most categories). End customers are small homebuilders (more competitive, less scale benefit for distributors).
$GMS Underfollowed building products distributor, HSD growth, favorable mix shift/ margin, tracking to beat estimates, trading at 10x EPS, 7x EBITDA. Peers at >50% higher multiples. $HD just acquired lower quality peer SRS for 17x EBITDA. GMS = $240 or +150% at that multiple.
$LYTS Very attractive acq of EMI following successful prior M&A blueprint--significant cross-selling op, cost reduction, expands product set which further solidifies dominant national position. Seeing +50% upside to shares from here.
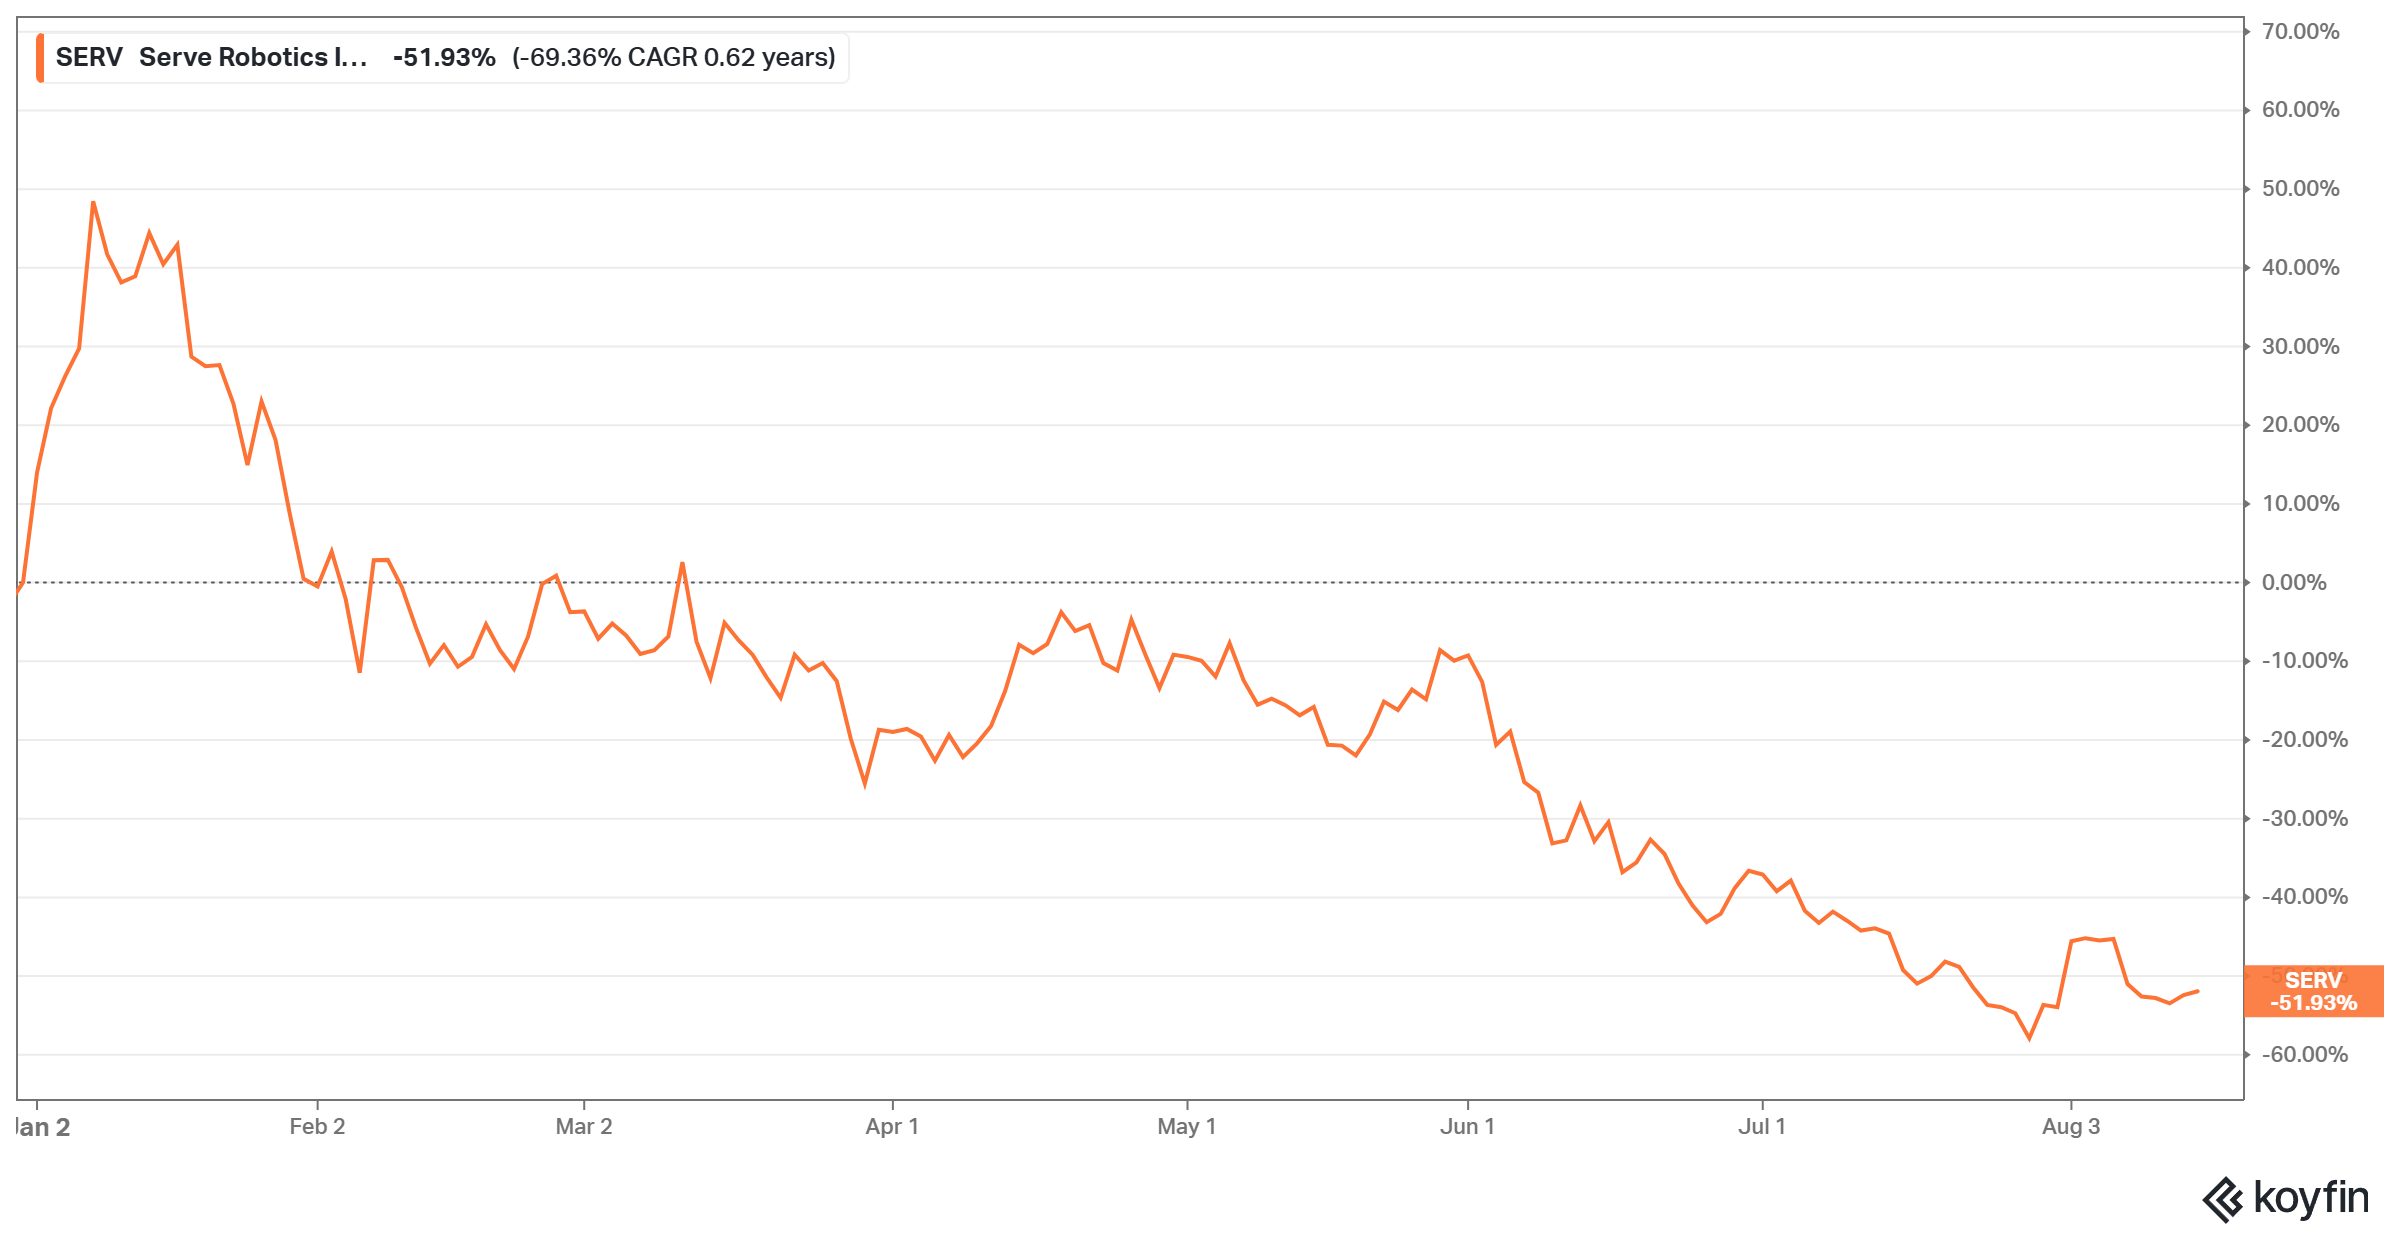
DoorDash’s integrated autonomous-delivery strategy contrasts with Uber’s 2026 divestment of Serve Robotics, its former delivery-robot…
E.W. Scripps, Team Internet, Monro, doValue and Inter & Co feature as special-situation trades involving mergers, asset sales, leverage and…

Hyperscalers’ off-balance-sheet lease and purchase obligations rose from roughly $1 trillion to $1.5 trillion, turning the AI buildout into…
HubSpot trades near its 2020 share price despite quadrupled revenue and $750 million in free cash flow, with Breeze AI upside weighed…

Steve Eisman argues the AI boom hinges on Anthropic and OpenAI’s importance to hyperscalers, while weighing software, CoreWeave and Cisco…

DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.

CoreWeave and Nebius cite AI compute shortages and higher-priced GPU renewals, but older-chip utilization and depreciation vary across…
Macy’s and Kohl’s face renewed short cases as their recent reratings ignore fading store-refresh gains, credit-card earnings exposure and…
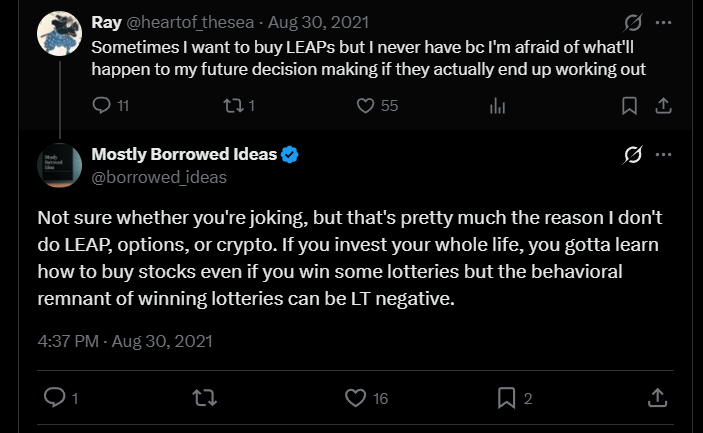
Options strategies will manage portfolio risk after Meta, Alphabet and Amazon calls drove gains, while Lululemon LEAPs produced an 80% loss.
Zoetis’s U.S. companion-animal revenue fell 6% as dermatology competition drove rebates and discounts, pushing full-year net pricing to…
 COUR · long
Coursera's combination with Udemy creates an online learning platform serving over 270 million learners with hundreds of thousands of…
Copart faces a near-term lift from pricier AV repairs and total losses, but shrinking accident volumes could eventually force its…

GFL’s proposed acquisition of Secure follows 19% revenue growth at Secure and 14.8% EBITDA growth at GFL, with Permian produced-water and…
Entravision’s ATS revenue rose 230% to $182.8 million in Q2, but shares fell from above $14 to about $8 after management forecast…
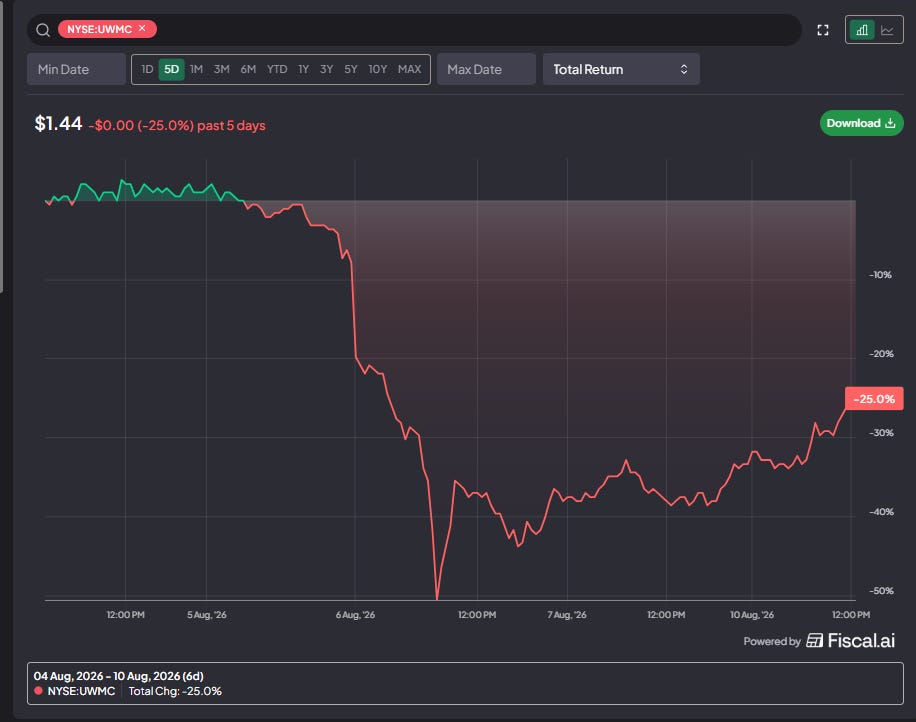
UWMC booked a roughly $600 million Q2 hedging loss tied to TWO months after the deal collapsed, contributing to an expensive capital raise.

Glenn Schorr and Ken Worthington discuss risks in private-credit software loans, agentic AI at retail brokers, crypto use cases and bank…
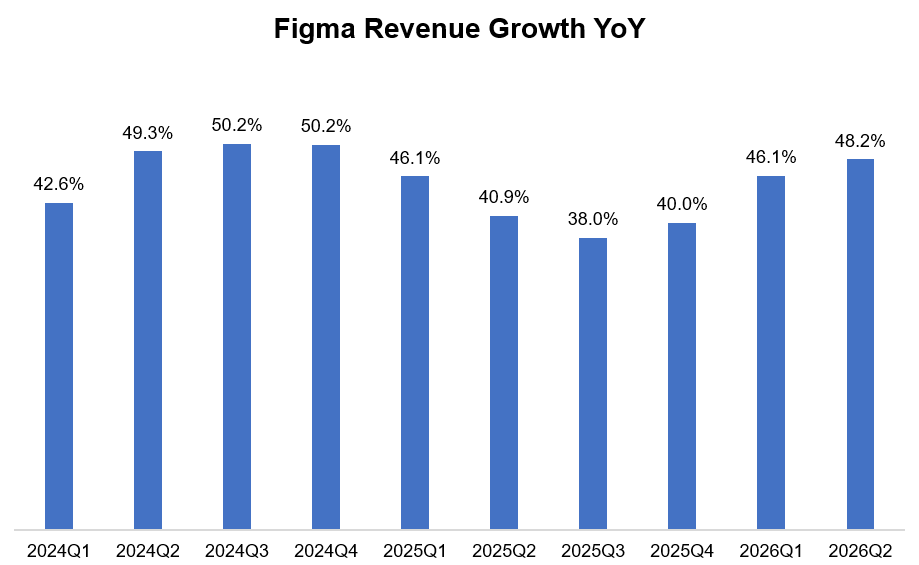
Figma raised its 2026 revenue growth guide to 39%, but a roughly 1% sequential 3Q outlook and unchanged $125-135 million operating-income…
Alphabet's Google Cloud swung from a $3.1 billion operating loss in 2021 to $13.9 billion profit in 2025 as Search revenue grew 13.2%.
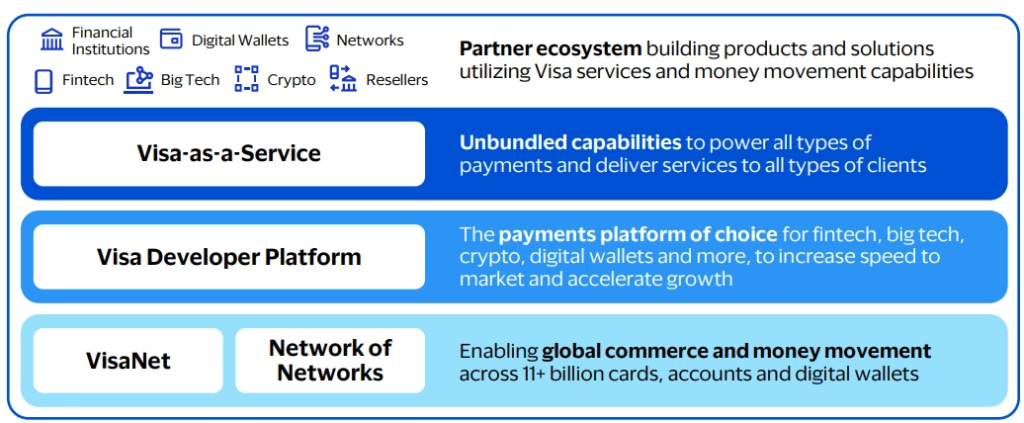
Visa and Mastercard have absorbed digital wallets and BNPL into their networks, using global merchant acceptance to turn supposed…
Navient trades near 40% of tangible book as Gator Financial Partners argues private student-loan growth and restructuring can reverse its…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.